The Short Answers
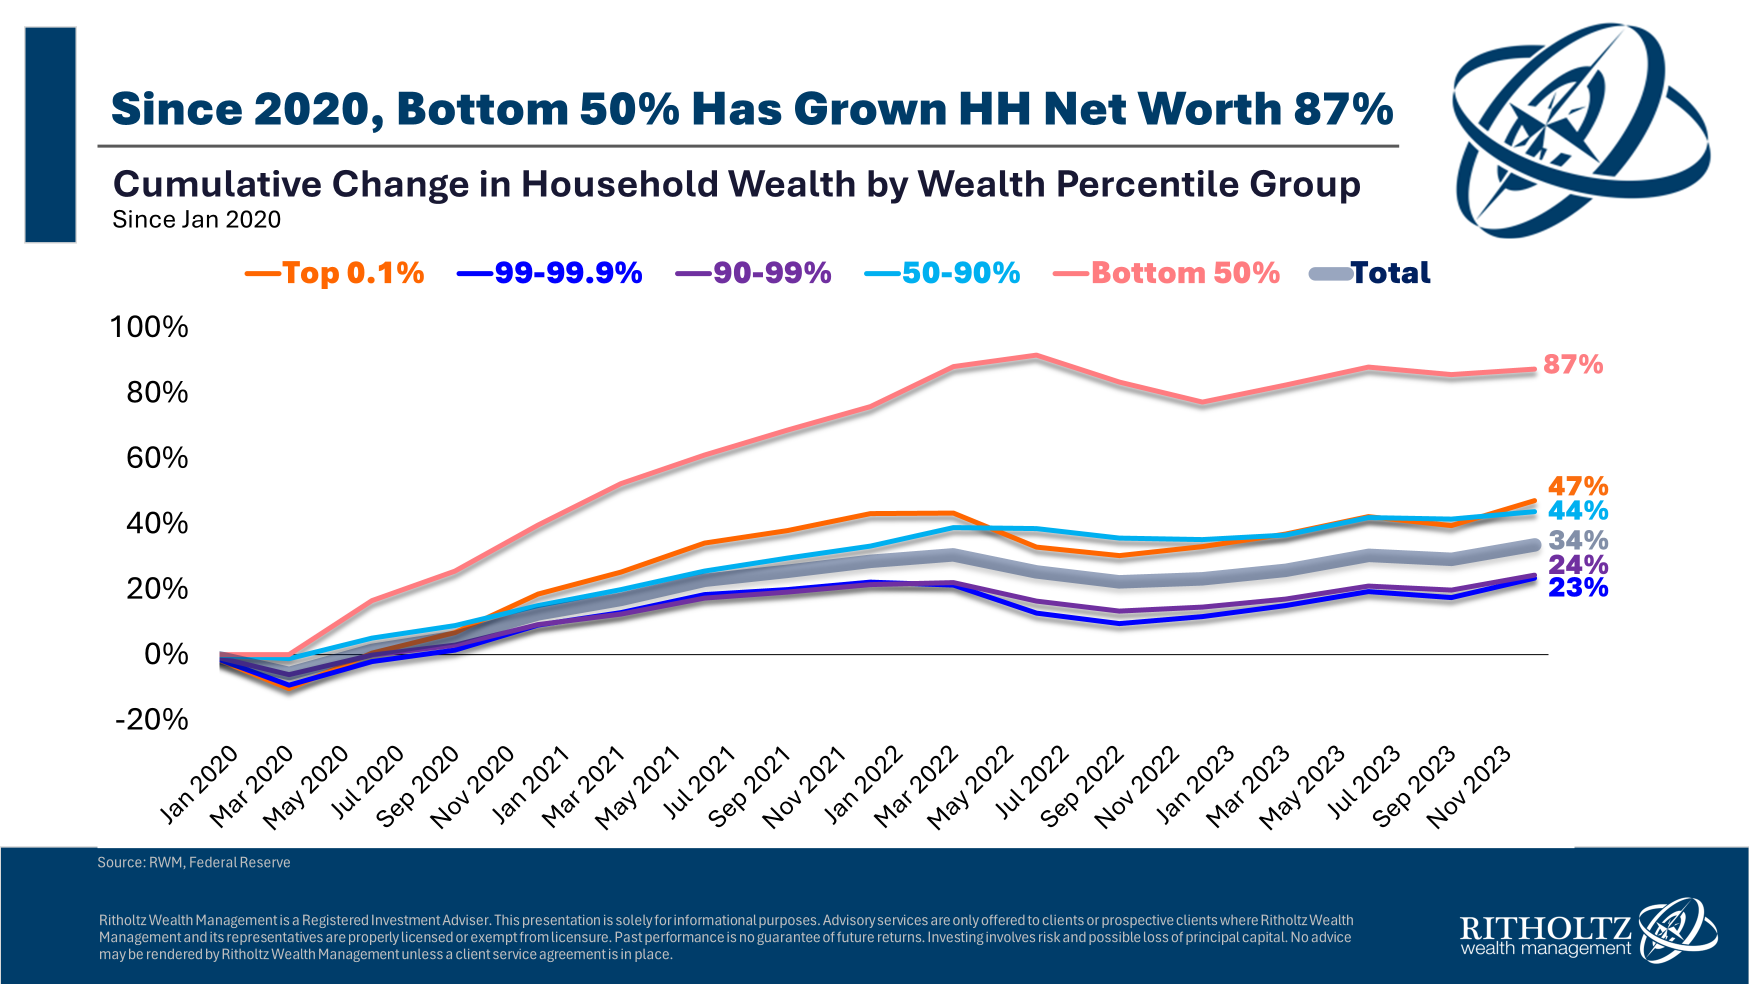
- The top 1% in the U.S. hold more wealth than the entire bottom 90% combined, a gap that has widened since the 1980s.
- Wealth inequality in the US is driven by tax policies favoring capital gains, asset appreciation, and inherited wealth—none of which are evenly distributed.
- Automatic stabilizers like unemployment insurance and Social Security do little to address wealth gaps because they target income, not assets.
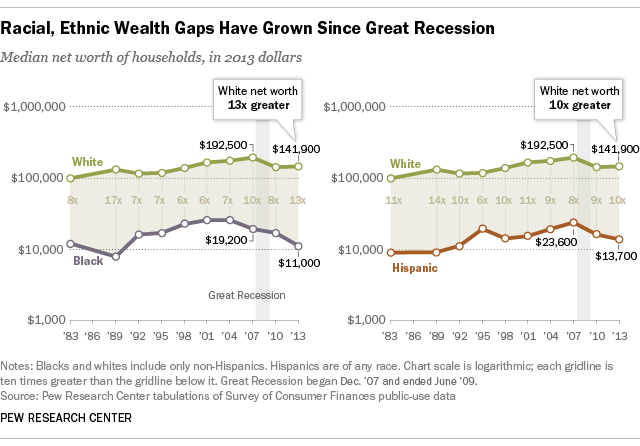
- Housing costs account for over 30% of the wealth gap between races, with Black households holding just 10 cents for every dollar of white family wealth.
- Corporate lobbying and campaign donations directly shape policies that benefit asset holders, creating a feedback loop of inequality.
- No major party has a coherent plan to reverse wealth inequality in the US—reforms like wealth taxes face structural opposition from those who benefit.
Deep Dive: The Full Picture
The wealth inequality in the US isn’t an accident of market forces; it’s the outcome of deliberate policy choices. Since the Reagan era, marginal tax rates for the highest earners have plummeted from over 70% to under 40%, while capital gains taxes—favoring assets like stocks and real estate—have been slashed repeatedly. The result? The richest 0.1% pay an effective tax rate of around 8% on their investments, compared to 15% for the bottom 20%. This isn’t just about revenue; it’s about structural bias toward those who already own assets. The problem deepens when you consider how wealth begets wealth. A family that inherits $1 million can invest it in appreciating assets (stocks, private equity, real estate) with minimal risk. Meanwhile, a family earning $50,000 annually must allocate most of their income to rent, healthcare, and basic needs—leaving little to nothing for investments that could break the cycle. The Federal Reserve’s own data shows that 90% of white families own stocks, compared to just 40% of Black families. This isn’t a coincidence; it’s the result of decades of redlining, predatory lending, and financial exclusion.The Context You Need
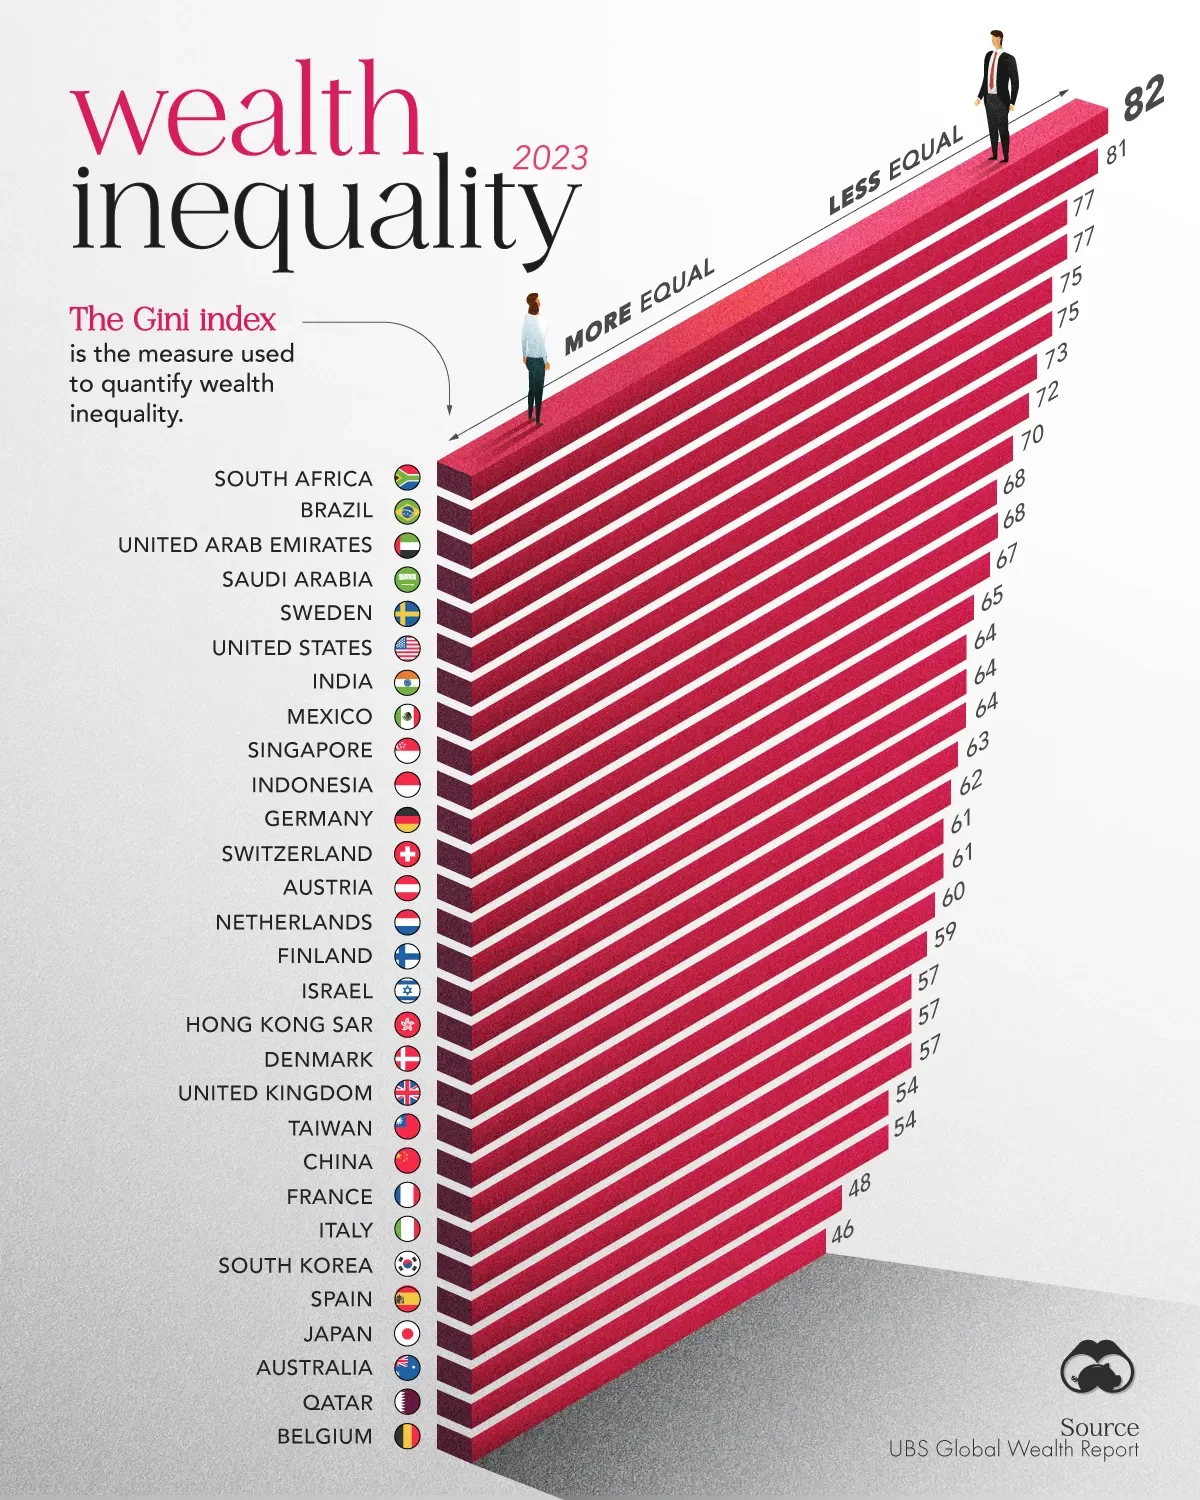
To understand wealth inequality in the US, you must look beyond GDP numbers. The U.S. economy is the world’s largest, yet its wealth distribution ranks among the most unequal in the developed world—worse than Germany, Canada, or Japan. The key difference? America’s religious faith in unregulated markets as the great equalizer. But markets don’t distribute wealth; they amplify existing disparities. When a CEO’s compensation package includes stock options that vest over decades, while a teacher’s pension is tied to stagnant public funding, the system isn’t neutral—it’s tilted. The myth of meritocracy obscures the reality: wealth inequality in the US is hereditary. A 2022 study by the Federal Reserve found that 60% of wealth inequality is explained by inheritance, not lifetime earnings. The top 10% of earners receive $1.5 trillion annually in unearned income—dividends, rent, capital gains—while the bottom 50% rely on wages that have barely kept pace with inflation since the 1970s. This isn’t just about dollars; it’s about who gets to write the rules of the economy.The Mechanics
The engine of wealth inequality in the US runs on three gears: tax policy, asset inflation, and political capture. Take capital gains taxes: an investor who buys a home for $500,000 and sells it for $2 million pays just 15% on the $1.5 million gain. Meanwhile, a worker earning $70,000 pays 22% in payroll taxes alone. The disparity is even starker for stocks—the top 1% of stockholders own 35% of all shares, and their gains are taxed at lower rates than their income. Then there’s housing, the single largest asset for most Americans. Zoning laws in cities like San Francisco and New York restrict new construction, driving up prices. A family that bought a home in 1980 might see its value triple; a renter in the same city sees their share of income swallowed by rent. The racial dimension is brutal: Black families have a net worth of $24,100, while white families average $188,200—a gap driven by centuries of discriminatory housing policy, from redlining to subprime lending. When wealth is concentrated in a few hands, the entire economy lurches toward instability, as seen in the 2008 crash, when the top 1% lost just 35% of their wealth, while the bottom 90% lost 38%.Details That Change the Picture
The wealth inequality in the US isn’t just about the ultra-rich; it’s about who gets to participate in the economy. Consider the financialization of retirement: 401(k)s and IRAs have replaced pensions, shifting risk from corporations to individuals. But only 56% of private-sector workers have access to a retirement plan, and those who do must navigate volatile markets. Meanwhile, the top 1% can afford financial advisors, tax shelters, and alternative investments—private equity, hedge funds, and real estate syndications—that generate double-digit annual returns with minimal risk. The data on wealth inequality in the US is clear but often buried. For example, the top 0.1% own more than the entire middle class—a group of roughly 120 million Americans. Their wealth isn’t just larger; it’s more liquid and more leveraged. While a middle-class family might have a mortgage and a car loan, the ultra-rich hold multiple properties, yachts, and portfolios that appreciate independently of economic downturns. This isn’t speculation; it’s structural dominance."Wealth inequality isn’t a bug in the system—it’s the system. The rules are written by those who already have the most to gain from them."
—Thomas Piketty, Capital in the Twenty-First Century
| Metric | Top 1% vs. Bottom 50% |
|---|---|
| Share of total wealth | 35% vs. 2.6% |
| Inheritance as % of wealth | 60%+ vs. <5% |
| Stock ownership | 90% vs. 10% |
Conclusion
The wealth inequality in the US isn’t a temporary blip; it’s a feature of how power operates. The system isn’t broken—it’s optimized for the wealthy. Tax loopholes, inherited advantages, and political influence create a feedback loop where the rich get richer, and everyone else plays catch-up. The question isn’t how this happened; it’s why no major institution has the will to fix it. Reform isn’t impossible, but it requires breaking the cycle of extraction. Wealth taxes, stronger unions, and democratic control over financial markets could reshape the balance—but only if the public demands it. The alternative? A future where economic mobility is a relic, and the American Dream is reserved for those who already own the ladder.Comprehensive FAQs
Q: How does wealth inequality in the US compare to other developed nations?
The U.S. has the most extreme wealth inequality among advanced economies, with the top 1% holding ~35% of all wealth—far higher than Germany (~25%) or France (~28%). The gap is driven by weaker social safety nets, lower taxes on capital, and greater reliance on private markets for retirement and healthcare.
Q: Do higher taxes on the rich actually reduce wealth inequality?
Historical evidence suggests they do—but only if paired with spending on public goods. The 1950s saw lower inequality when top marginal tax rates hit 90% and proceeds funded education and infrastructure. Today, wealth taxes (like those in Spain or South Africa) have reduced concentration—but U.S. political resistance makes reform unlikely without mass pressure.
Q: Why don’t more Americans support policies to address wealth inequality?
Cultural narratives frame inequality as "motivation" or "opportunity," while systemic factors (like inherited wealth) are downplayed. Additionally, media ownership is concentrated among the wealthy, shaping public discourse. Studies show that when people directly experience inequality (e.g., through healthcare costs), support for redistribution rises—but abstract debates often fail to move the needle.
Q: How does racial wealth inequality fit into the broader picture?
Racial wealth gaps amplify overall inequality. Black families hold $10 in wealth for every $100 held by white families—a divide rooted in slavery, Jim Crow, redlining, and predatory lending. Closing this gap would reduce national wealth inequality by ~20%, but policies like reparations or targeted housing reforms face fierce opposition from those who benefit from the status quo.
Q: Can technology or automation actually worsen wealth inequality?
Yes. AI and automation benefit capital over labor—replacing jobs while increasing corporate profits. The top 1% own ~70% of all AI-related patents, and platforms like Amazon or Google extract value from workers without sharing gains. Without regulation, wealth inequality in the US could become even more extreme as tech monopolies dominate entire industries.
Q: What’s the most effective policy to reduce wealth inequality?
Experts cite three levers:
- Wealth taxes (e.g., 2-4% annual levy on fortunes over $50M).
- Worker ownership (e.g., mandating employee stock in corporations).
- Public investment (e.g., free college, universal childcare).
