The Complete Overview of Wealth Distribution in the US
The wealth distribution in the US is a study in extremes. As of recent data, the median net worth of a white household is nearly ten times that of a Black household, and the top 0.1% own more than the entire bottom 90% combined. These figures aren’t just numbers—they reflect a system where inheritance, asset appreciation, and corporate ownership play outsized roles. The richest 1% saw their share of national wealth rise from 25% in 1980 to over 40% today, while the bottom 50%’s share has shrunk. What makes this distribution particularly volatile is its sensitivity to market fluctuations. During the 2008 financial crisis, the wealth of the top 1% dropped by 36%, but it rebounded swiftly—far faster than the recovery for most Americans. The pandemic years repeated this pattern: while billionaires like Jeff Bezos and Elon Musk saw their fortunes surge, millions of service workers faced layoffs and eviction threats. The wealth distribution in the US isn’t static; it’s a dynamic, often brutal reflection of economic power.Historical Background and Evolution
The modern era of wealth inequality in the US traces back to the late 20th century, when policies like Reagan-era tax cuts and deregulation began favoring capital over labor. The top marginal tax rate, which had been as high as 91% in the 1950s, plummeted to 28% by 1988. Simultaneously, financial innovations—such as private equity, hedge funds, and leveraged buyouts—allowed the ultra-wealthy to extract value from public companies while shielding themselves from traditional taxation. These shifts didn’t happen in a vacuum; they were the result of lobbying efforts by industries that stood to gain the most. The 1990s and 2000s saw further consolidation. The dot-com boom and subsequent bust demonstrated how wealth could concentrate in the hands of a few tech moguls, while the 2008 crisis revealed the fragility of the system. Bailouts for banks and Wall Street firms—funded by taxpayer dollars—only deepened public resentment, fueling movements like Occupy Wall Street. Yet despite periodic outcries, structural changes remained limited. The wealth distribution in the US continued its upward trajectory, now accelerated by the rise of Big Tech and the gig economy.Core Mechanisms: How It Works
At its core, wealth distribution in the US is driven by three interconnected forces: tax policy, asset ownership, and labor market dynamics. The federal tax code, for instance, treats capital gains—like stock appreciation—at lower rates than ordinary income. This favors investors over workers, as the wealthy derive a larger share of their income from assets rather than salaries. Meanwhile, the estate tax exempts the majority of estates from inheritance taxes, allowing wealth to compound across generations without redistribution. Asset ownership is another critical lever. Homeownership remains the primary wealth-building tool for middle-class Americans, but systemic barriers—like redlining, predatory lending, and rising housing costs—have made it inaccessible to many. The top 10% of households own roughly 87% of all stocks, further entrenching inequality. When markets rise, this group benefits disproportionately; when they fall, their losses are cushioned by diversified portfolios. The result is a system where wealth begets more wealth, while lack of assets creates a cycle of deprivation.Key Benefits and Crucial Impact
Proponents of the current wealth distribution in the US argue that it incentivizes innovation and capital investment, driving economic growth. High-net-worth individuals, they claim, create jobs, fund startups, and contribute to philanthropy on a scale that government couldn’t match. There’s truth to this: billionaires like Mark Zuckerberg and Warren Buffett have donated billions to education and healthcare initiatives. Yet the benefits of this system are unevenly distributed, with the majority of Americans seeing little trickle-down effect. The impact on social mobility is perhaps the most contentious aspect. Studies show that the US has one of the lowest rates of intergenerational wealth mobility among developed nations. A child born into the bottom 20% of earners has less than a 10% chance of reaching the top 20%. This stagnation isn’t just a moral failing—it’s an economic one. When large segments of the population lack financial security, consumer demand stagnates, and long-term growth suffers. The wealth distribution in the US today isn’t just a reflection of past policies; it’s a predictor of future instability."Wealth inequality is the great counterfeit of our time. It makes us believe that we live in a meritocracy when, in fact, we live in a system rigged to reward those who already have." — Rachel Maddow, Political Commentator
Major Advantages
- Economic dynamism: Concentrated wealth can fuel entrepreneurship and high-risk investments that drive innovation, such as Silicon Valley’s tech boom.
- Philanthropic leverage: Ultra-high-net-worth individuals can direct billions toward causes like medical research or education, filling gaps left by government budgets.
- Global competitiveness: A strong upper class can attract talent and capital, positioning the US as a leader in finance, technology, and culture.
- Tax revenue efficiency: Wealthy individuals and corporations contribute disproportionately to tax bases, funding public services like infrastructure and defense.
- Market liquidity: High-net-worth investors provide liquidity to markets, supporting businesses and job creation through stock purchases and venture capital.
- Political influence: Wealthy donors shape policy debates, often pushing for deregulation and tax cuts that benefit capital over labor.

Comparative Analysis
| Metric | United States | European Union (Average) |
|---|---|---|
| Top 1% Wealth Share | ~40% | ~25% |
| Intergenerational Mobility | Low (child poverty persistence) | Moderate to High (stronger social safety nets) |
| Progressive Taxation | Regressive (lower top rates) | Progressive (higher top rates, wealth taxes) |
Future Trends and Innovations
The wealth distribution in the US is likely to remain a dominant political and economic issue in the coming decades. Rising awareness of inequality—amplified by social media and movements like Black Lives Matter—will continue pressuring policymakers to address systemic barriers. Potential shifts include expanded social safety nets, higher taxes on capital gains, and reforms to estate taxation. However, resistance from entrenched interests may limit progress, leaving the status quo intact for the foreseeable future. Technological disruption could also reshape the landscape. Automation threatens to displace millions of middle-class jobs, while AI and algorithmic trading may further concentrate wealth in the hands of those who control these tools. Meanwhile, younger generations—who increasingly reject traditional wealth-building models—may push for alternatives like universal basic income or cooperative ownership. The question isn’t whether wealth distribution will change, but how quickly and in whose favor.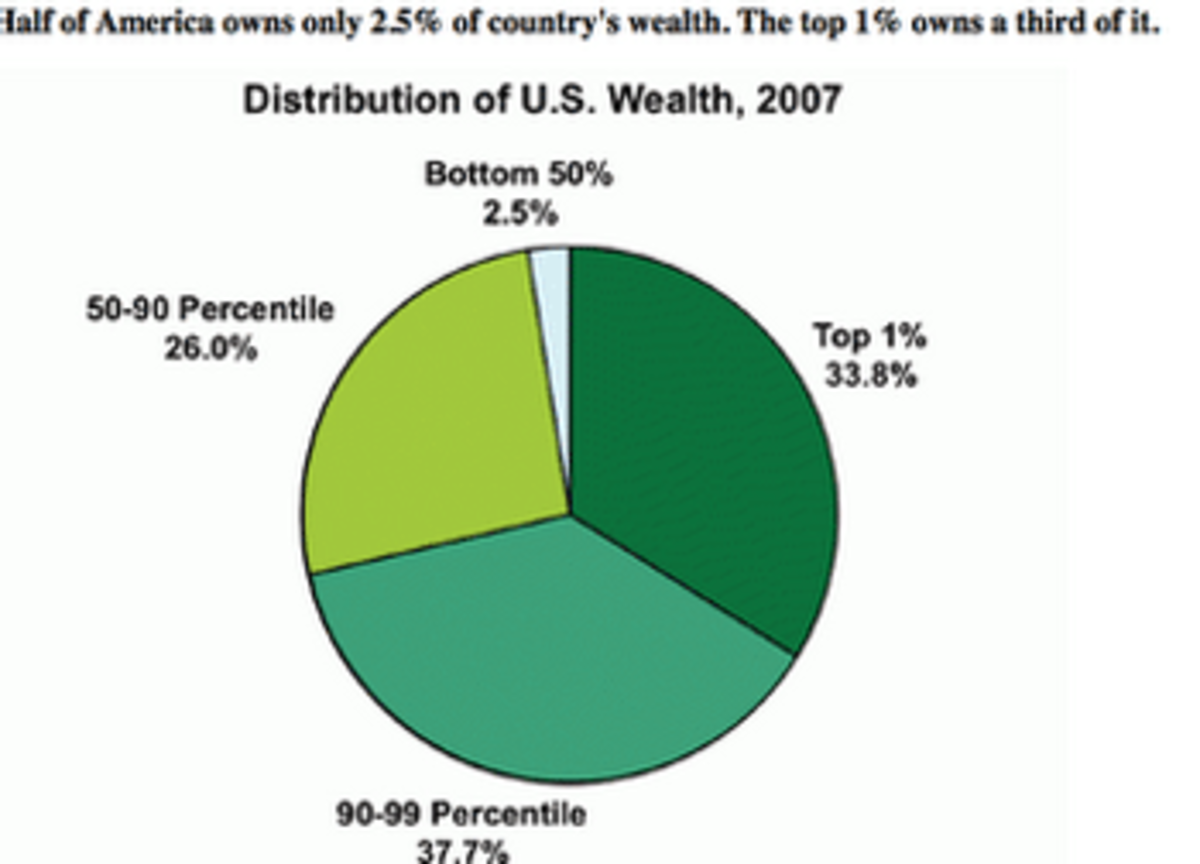
Conclusion
The wealth distribution in the US is a product of deliberate policy choices, not inevitable market forces. From tax cuts to financial deregulation, each decision has reinforced the advantages of the few over the many. The consequences are visible in every corner of American life: from the gentrification of urban neighborhoods to the decline of small-town main streets. Ignoring this imbalance risks deeper social fractures, as trust in institutions erodes and political polarization intensifies. Yet there’s reason for cautious optimism. Public opinion is shifting, with growing support for wealth taxes and stronger labor protections. The challenge lies in translating this sentiment into lasting policy change. The alternative—a future where the ultra-rich wield even greater influence—is not just economically unsustainable, but democratically dangerous. The time to act is now, before the wealth distribution in the US becomes irreversible.Comprehensive FAQs
Q: How does wealth distribution in the US compare to other developed nations?
A: The US has the most unequal wealth distribution among developed nations, with the top 1% holding roughly 40% of all wealth—far higher than in countries like Germany or Sweden, where progressive taxation and stronger labor protections reduce disparity.
Q: What role does inheritance play in wealth inequality?
A: Inheritance accounts for a significant portion of wealth accumulation, particularly among the top 10%. The estate tax exempts most estates, allowing families to pass down generational wealth without redistribution, reinforcing inequality.
Q: Can wealth distribution in the US improve without major policy changes?
A: Unlikely. While cultural shifts—like increased focus on financial literacy—can help, structural change requires tax reform, stronger labor unions, and policies that promote asset ownership among lower-income groups.
Q: How does student debt affect wealth distribution?
A: Student debt disproportionately burdens younger generations, delaying homeownership and wealth accumulation. This creates a cycle where future earners start with less, widening the gap between older, wealthier cohorts and younger workers.
Q: What are the biggest misconceptions about wealth inequality?
A: One common myth is that inequality is solely due to laziness or lack of effort. In reality, systemic barriers—like access to capital, education, and fair wages—play a far larger role. Another misconception is that high inequality drives economic growth, when evidence suggests it stifles consumer demand and long-term stability.
