7 Things Worth Knowing About Warren Buffett’s Net Worth in 1980
Buffett’s financial standing in 1980 wasn’t just a reflection of past successes but a blueprint for future dominance. To grasp its significance, we must examine the mechanics behind the number—how he got there, what it represented, and why it mattered in an era of stagflation and corporate upheaval. The details reveal a man who understood that wealth, in his world, was less about timing the market and more about owning it.1. Berkshire Hathaway’s Stock Was the Core of His Wealth
By 1980, Berkshire Hathaway’s Class A shares—of which Buffett owned a majority—were the primary driver of his net worth. The company’s stock had appreciated significantly since Buffett took control in the late 1960s, though its value was still largely tied to its textile operations. What set Berkshire apart was Buffett’s ability to reinvest profits into other ventures, a strategy that would later pay dividends. The stock’s price in 1980 was reportedly around $300 per share, but its intrinsic value—based on Buffett’s side investments—was far higher. This duality was critical: outsiders saw a struggling mill; insiders saw a vehicle for acquiring undervalued businesses. The gap between market price and true value was where Buffett’s genius lay. The textile division itself was a liability, draining cash but providing a platform for Buffett to deploy capital elsewhere. He had already begun shifting Berkshire’s focus toward insurance underwriting and equity investments, though these wouldn’t yet dominate the balance sheet. The net worth figure for 1980 must account for this asymmetry: the public saw one thing, but Buffett saw the potential of a financial alchemy he was only beginning to master.2. The Coca-Cola Investment Was a Game-Changer
In 1980, Buffett’s purchase of a 7% stake in Coca-Cola for roughly $1 billion (a then-record for a single investment) sent shockwaves through Wall Street. This wasn’t just another stock pick—it was a statement. The deal, finalized in 1988 but initiated in 1980, was a bet on brand power, global distribution, and consumer loyalty. For Buffett, Coca-Cola represented the kind of economic moat he sought: a company with pricing power, recurring revenue, and a product that transcended economic cycles. The investment alone would later account for a significant portion of his net worth, but in 1980, its impact was less about immediate returns and more about signaling a shift in strategy. What’s often overlooked is how this investment reshaped Buffett’s public image. Before Coca-Cola, he was seen as a value investor who bought distressed assets. Afterward, he became synonymous with buying blue-chip brands. The timing was perfect: Coca-Cola’s stock was undervalued relative to its earnings, and Buffett’s patience would be rewarded as the company’s growth outpaced expectations. By 1980, he wasn’t just accumulating wealth; he was building a legacy.3. Buffett’s Partnerships Were the Engine of Growth
Buffett’s net worth in 1980 wasn’t solely his own—it was a product of the partnerships he’d formed decades earlier. In the 1950s and 60s, he’d pooled capital with investors like Walter Schloss and later, more prominently, with limited partners through Buffett Partnership Ltd. These partnerships allowed him to deploy larger sums than he could on his own, and by 1980, the returns had been staggering. Some partners had seen their investments grow hundreds of times over, though Buffett had long since dissolved the partnerships to focus on Berkshire Hathaway. The success of these early ventures demonstrated his ability to generate alpha consistently, a track record that attracted institutional confidence. The transition from partnerships to Berkshire Hathaway was seamless. The capital he’d managed for others now belonged to him and his shareholders. This was the year he began consolidating his empire, using Berkshire’s stock as currency to acquire other businesses. The net worth figure for 1980 must include not just his direct holdings but the implied value of these relationships—trust, reputation, and access to capital that few could replicate.4. Inflation and Market Volatility Tested His Discipline
The late 1970s and early 1980s were a period of economic turbulence, with double-digit inflation and erratic stock markets. Buffett’s net worth in 1980 was a testament to his ability to navigate these headwinds. While many investors panicked or chased speculative plays, Buffett doubled down on cash-rich companies with durable competitive advantages. His focus on businesses that could raise prices without losing customers—like Coca-Cola or See’s Candies—protected his portfolio from inflation’s erosive effects. The S&P 500 struggled in this environment, but Buffett’s carefully selected holdings outperformed. What’s striking is how Buffett’s approach contrasted with the era’s conventional wisdom. While others sought to hedge against inflation with commodities or real estate, Buffett stuck to equities, believing that patient ownership of great businesses would outperform any short-term tactic. His net worth in 1980 wasn’t just a product of luck; it was the result of a contrarian mindset that paid off when others faltered.5. The Washington Post Deal Solidified His Reputation
In 1974, Buffett had begun acquiring shares in The Washington Post Company, a move that would later prove pivotal. By 1980, his stake had grown, and the company’s performance under Katharine Graham had made it a standout holding. The Post wasn’t just a media company; it was a symbol of Buffett’s ability to identify businesses with intangible assets—brand, talent, and market position—that traditional financial metrics often overlooked. The investment also demonstrated his willingness to hold positions for decades, a rarity in an age of quarterly earnings pressure. The Washington Post deal was more than an investment; it was a vote of confidence in Buffett’s judgment. As his net worth in 1980 climbed, so did the respect of his peers. The Post’s success reinforced the idea that Buffett wasn’t just buying stocks but ownership stakes in enduring institutions. This was the year his reputation as a long-term thinker became inseparable from his financial success.6. Taxes and Corporate Structure Played a Hidden Role
Buffett’s net worth in 1980 was also shaped by the tax advantages of his corporate structure. By holding assets within Berkshire Hathaway, he minimized personal tax liabilities while allowing the company to reinvest profits at a lower cost. This was a critical advantage in an era of high marginal tax rates. The use of tax-efficient vehicles—like insurance float from underwriting operations—allowed him to deploy capital more aggressively than individual investors could. Without these structural benefits, his wealth accumulation might have looked very different. The interplay between personal wealth and corporate strategy is often underappreciated. Buffett didn’t just invest; he engineered his holdings to work for him in ways that maximized after-tax returns. This was the year he began refining Berkshire’s tax-efficient operations, ensuring that his net worth grew not just from market appreciation but from the compounding effects of smart structuring.7. The Psychological Factor: Patience as a Competitive Advantage
“Someone’s sitting in the shade today because someone planted a tree a long time ago.” —Warren BuffettBuffett’s net worth in 1980 was the culmination of decades of patience—a trait that set him apart from his peers. While others sought quick profits, Buffett was willing to wait years, even decades, for the right opportunity. This psychological edge was as important as any financial metric. His ability to resist the urge to trade or time the market allowed him to accumulate holdings that would appreciate exponentially over time. The Coca-Cola investment, the Washington Post stake, and even Berkshire’s textile operations were all part of a long-term vision that required discipline most investors lacked. In 1980, Buffett wasn’t just rich; he was wealthy in a way that few could replicate. His net worth wasn’t a fluke but the result of a mindset that treated investing as a marathon, not a sprint. This was the year the world began to take notice—not because he was the richest man in the room, but because he was building something that would outlast generations.
How These Facts Connect
The story of Warren Buffett’s net worth in 1980 is more than a financial snapshot; it’s a masterclass in how wealth is created through discipline, structure, and foresight. Each element—from Berkshire’s stock to the Coca-Cola bet, from partnerships to tax efficiency—was a piece of a larger strategy that prioritized ownership over speculation. Buffett didn’t chase trends; he built platforms. His net worth wasn’t just a reflection of market performance but of his ability to identify and nurture businesses that would thrive regardless of economic conditions. What’s most revealing is how these factors reinforced one another. The success of his early partnerships gave him the capital to take larger risks, like Coca-Cola. The tax advantages of Berkshire allowed him to reinvest profits at scale, while his patience ensured he held onto winners long enough for compounding to work its magic. The Washington Post deal wasn’t just an investment; it was a statement about his ability to spot intangible value. Together, these elements created a feedback loop where success bred more success, setting the stage for the Berkshire empire that would follow.| Factor | Impact on Net Worth | Long-Term Legacy |
|---|---|---|
| Berkshire Hathaway Stock | Primary wealth driver; undervalued asset | Foundation for future acquisitions |
| Coca-Cola Investment | Signaled shift to blue-chip brands | Proved brand power as enduring value |
| Partnerships | Leveraged capital for larger bets | Built reputation as a trusted manager |
| Tax Efficiency | Minimized drag on returns | Allowed aggressive reinvestment |
Conclusion
Warren Buffett’s net worth in 1980 was a turning point, not because it was the peak of his career but because it represented the convergence of all the principles that would define his legacy. This was the year he stopped being a value investor and became an architect of wealth on a scale few could imagine. The numbers—whether $100 million or slightly higher—pale in comparison to what they symbolized: a rejection of short-term thinking in favor of long-term ownership, a mastery of corporate structure, and an unshakable belief in the power of compounding. What’s most enduring about this period isn’t the exact figure but the mindset behind it. Buffett didn’t get rich by being right all the time; he got rich by being right about the things that mattered most—business quality, patience, and the willingness to think differently. In 1980, he wasn’t just accumulating wealth; he was building a framework that would allow him to do so for decades to come. The lesson for investors, then and now, is simple: true wealth isn’t about timing the market but owning it.Comprehensive FAQs
Q: How did Warren Buffett’s net worth compare to other billionaires in 1980?
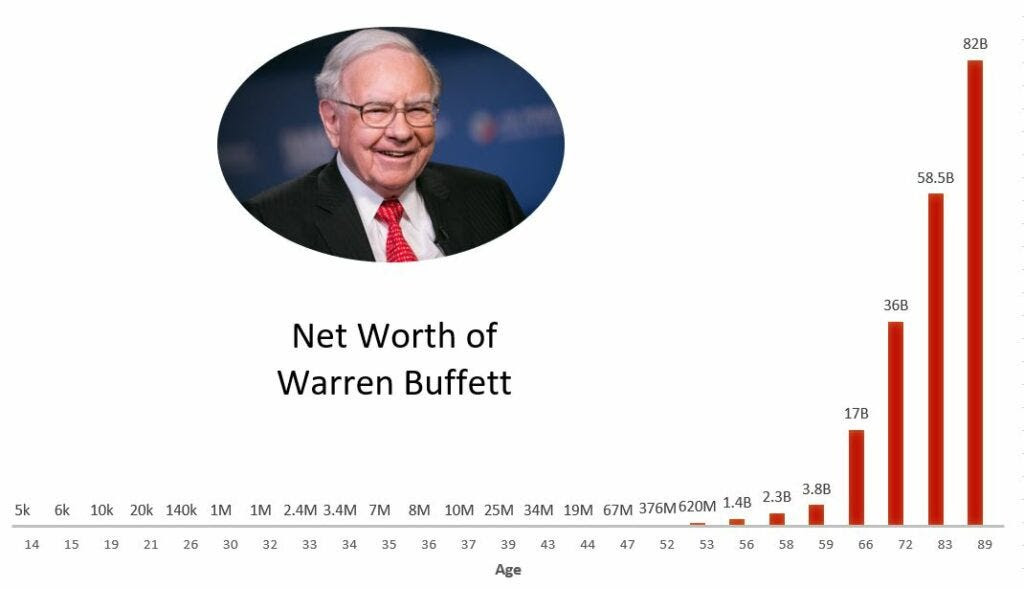
In 1980, Buffett’s net worth was estimated to be in the range of $100 million to $200 million, placing him among the wealthiest individuals in the U.S. However, he wasn’t yet in the same league as oil barons like the Rockefellers or media moguls like Rupert Murdoch. His wealth was still largely tied to Berkshire Hathaway and private investments, whereas others derived their fortunes from more visible industries. By the late 1980s, his net worth would surpass theirs as his investments in Coca-Cola, GEICO, and other companies began to pay off exponentially.
Q: What was Berkshire Hathaway’s stock price in 1980, and how did it contribute to Buffett’s wealth?
Berkshire Hathaway’s Class A shares traded around $300 per share in 1980, but their intrinsic value—based on Buffett’s side investments and cash holdings—was significantly higher. The stock’s price was artificially depressed because most investors focused on the struggling textile division rather than the company’s potential as a holding vehicle. Buffett’s majority ownership meant that as the stock’s value appreciated (or as he reinvested profits into other businesses), his net worth grew disproportionately. The textile operations were a distraction; the real value lay in Berkshire’s ability to deploy capital elsewhere.
Q: Did Warren Buffett’s net worth in 1980 include his stake in The Washington Post?
Yes, Buffett’s stake in The Washington Post Company was a material part of his net worth in 1980. He had begun acquiring shares in the mid-1970s, and by 1980, his holdings were substantial enough to influence the company’s stock price. The Post was more than an investment; it was a validation of Buffett’s ability to identify businesses with strong intangible assets. His stake would later grow, and the company’s performance under Katharine Graham made it one of his most successful long-term holdings.
Q: How did inflation affect Warren Buffett’s net worth in 1980?
Inflation in the late 1970s and early 1980s was a headwind for many investors, but Buffett’s focus on businesses with pricing power—like Coca-Cola and See’s Candies—protected his portfolio. Unlike investors who chased commodities or real estate to hedge against inflation, Buffett stuck to equities, believing that great companies could raise prices and maintain margins regardless of economic conditions. His net worth grew because his holdings appreciated in real terms, not just nominal ones.
Q: Were there any major mistakes or setbacks in Buffett’s net worth growth around 1980?
While Buffett’s track record in 1980 was strong, there were a few areas where his judgment was tested. One notable example was his initial hesitation to invest in gold or other commodities during the inflationary period, a stance that some critics argued was shortsighted. Additionally, Berkshire’s textile operations continued to drain cash, though Buffett saw this as a necessary evil to fund other investments. These weren’t failures but trade-offs in a strategy that prioritized long-term growth over short-term fixes.
Q: How did Warren Buffett’s net worth in 1980 compare to his net worth in the 1970s?
Buffett’s net worth grew significantly from the 1970s to 1980, thanks to the success of his partnerships and early investments in Berkshire Hathaway. In the early 1970s, his wealth was in the tens of millions, but by 1980, it had ballooned due to the appreciation of his stock holdings, the Coca-Cola investment, and the performance of his insurance underwriting operations. The shift from partnerships to Berkshire as his primary vehicle was a key factor in this growth, as it allowed him to deploy capital on a larger scale.
Q: What role did Charlie Munger play in Buffett’s net worth growth by 1980?
Charlie Munger, Buffett’s longtime partner and vice chairman of Berkshire Hathaway, played an indirect but critical role in his net worth growth by 1980. Munger’s legal and business acumen helped Buffett navigate corporate structures, tax efficiency, and deal negotiations. While Munger wasn’t a public figure in Buffett’s investment decisions at this stage, his influence was foundational. Their partnership would later become one of the most celebrated in business history, but by 1980, Munger’s contributions were already shaping Buffett’s ability to execute his vision.
Q: How accurate are estimates of Warren Buffett’s net worth in 1980?
Estimates of Buffett’s net worth in 1980 vary due to the private nature of many of his holdings and the lack of real-time transparency. Figures around the $100 million to $200 million range are widely cited, but these are rough approximations. Berkshire Hathaway’s financial disclosures were less detailed in those years, and some assets—like private investments—weren’t publicly tracked. For context, Buffett’s net worth would become far more transparent in later decades as Berkshire’s operations expanded and regulatory requirements increased.
