
The Complete Overview of Warren Buffett’s Bailout Legacy
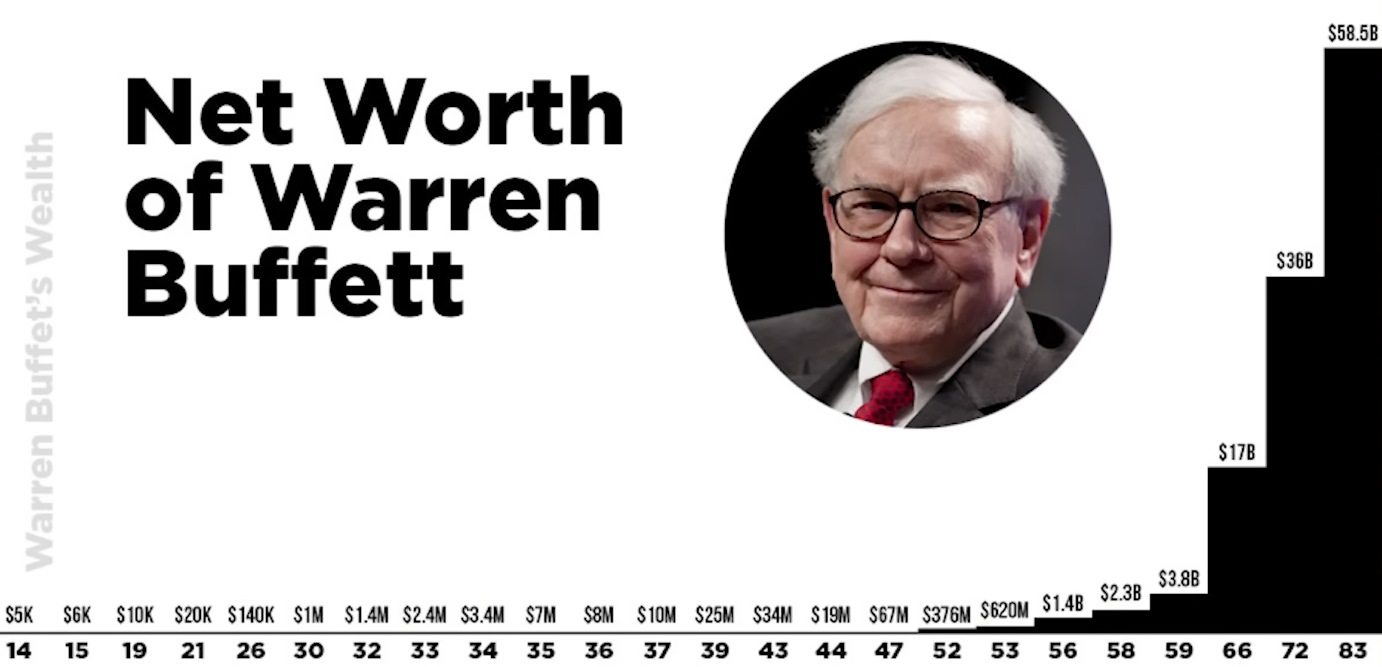
Warren Buffett’s involvement in financial rescues isn’t a recent phenomenon. His "warren buffet net worth bailout" interventions have spanned over four decades, from propping up struggling insurers in the 1990s to his high-profile 2008 moves. What distinguishes these actions isn’t just their timing but their strategic alignment with Berkshire Hathaway’s core principles: buying assets at distressed prices, demanding operational improvements, and holding positions for decades. Buffett’s bailouts aren’t impulsive; they’re part of a long-term wealth preservation strategy that has allowed his net worth to balloon from $1 billion in 1985 to over $130 billion today. The 2008 crisis, in particular, cemented his reputation as a financial fireman—a figure willing to deploy capital not just for profit, but to prevent systemic collapse. The "warren buffet net worth bailout" narrative extends beyond dollars and cents. It’s a story of influence without control: Buffett’s letters to shareholders and public statements often carried more weight than regulatory edicts. When he criticized banks for excessive leverage in 2002, his warnings were dismissed—until the 2008 crash proved him right. His bailouts weren’t just transactions; they were moral arbitrage, leveraging his capital to enforce discipline on Wall Street. Even today, as discussions about modern financial safety nets rage, Buffett’s approach remains a counterpoint to traditional bailout models—one that prioritizes private capital efficiency over government-led redistribution.Historical Background and Evolution
Buffett’s first major "warren buffet net worth bailout" came in 1998, when he rescued General Re (a reinsurance subsidiary of Berkshire Hathaway) from a liquidity crunch by buying back its shares at a premium. This wasn’t charity; it was a circular investment that reinforced Berkshire’s balance sheet while stabilizing a key sector. The move foreshadowed his later crisis interventions, proving that even in distress, Buffett could turn a profit while serving a public good. Fast forward to 2008, and his strategy evolved. Instead of buying entire companies, he targeted systemically important institutions—Goldman Sachs, Bank of America, and GE—with injections that ranged from $3 billion to $5 billion. These weren’t loans; they were equity stakes that gave him a say in management, a rarity in traditional bailouts. The "warren buffet net worth bailout" of 2008 was particularly telling. While the U.S. government’s Troubled Asset Relief Program (TARP) was mired in political debates, Buffett’s capital arrived with no strings attached—except for his insistence on better risk management. His $5 billion into Goldman Sachs, for example, wasn’t just a lifeline; it was a strategic bet that the bank would emerge stronger. Buffett’s approach highlighted a critical flaw in public bailouts: they often lacked private-sector accountability. His interventions forced banks to confront their balance sheets head-on, a lesson that would later influence regulatory reforms like the Dodd-Frank Act. Even today, analysts cite Buffett’s 2008 moves as a case study in how private capital can outpace government speed in crises.Core Mechanisms: How It Works
At its core, the "warren buffet net worth bailout" operates on three pillars: capital deployment, governance influence, and long-term holding. Buffett doesn’t just write checks; he structures deals to align incentives. His 2008 investments in Goldman Sachs, for instance, came with a warrant that gave Berkshire the right to buy additional shares at a fixed price—effectively locking in upside while providing immediate liquidity. This wasn’t philanthropy; it was financial engineering that rewarded Buffett for taking risk. Similarly, his 2011 purchase of $5 billion in Bank of America stock wasn’t a bailout in the traditional sense. It was a strategic bet on the bank’s recovery, combined with a demand for cost-cutting measures that benefited shareholders. The "warren buffet net worth bailout" mechanism also relies on reputation capital. Buffett’s name alone can stabilize markets. When he announced his 2008 investments, stock prices of distressed banks rallied immediately, not because of the money itself, but because investors trusted his judgment. This halo effect is a critical component of his strategy—it turns his net worth into a liquidity amplifier. Unlike governments, which often face skepticism about bailouts, Buffett’s interventions are seen as value-additive. His approach also avoids the moral hazard of traditional bailouts: instead of rewarding reckless behavior, he conditions capital on structural reforms. This has made his "warren buffet net worth bailout" model a preferred option for institutions that can’t or won’t seek public aid.Key Benefits and Crucial Impact
The most immediate benefit of Buffett’s "warren buffet net worth bailout" strategy is market stabilization without taxpayer burden. His 2008 moves prevented the collapse of major financial institutions, but they also preserved jobs and economic activity that would have been lost if those firms had failed. Unlike TARP, which required congressional approval and was plagued by political delays, Buffett’s capital arrived within days, filling the gap until government programs could scale. This speed isn’t accidental; it’s a function of private capital mobility. Buffett’s net worth allows him to act as a force multiplier in crises, deploying resources faster than bureaucracies can. Beyond immediate stabilization, Buffett’s "warren buffet net worth bailout" approach has reshaped corporate governance. His insistence on transparency and risk management in the banks he aided led to cultural shifts in Wall Street. For example, his demands at Goldman Sachs post-2008 contributed to the bank’s later emphasis on shareholder-friendly policies, such as buybacks and dividends. This governance spillover is one of the most underrated impacts of his bailouts—proving that private capital can enforce discipline where regulation fails. Even today, when central banks hesitate to intervene, investors look to Buffett’s playbook as a template for crisis response."The best thing to hold may be cash, and we will be holding a lot of cash. We are not interested in buying businesses just because they are cheap. That is not our approach. We are interested in buying businesses that we can understand and that have favorable long-term prospects." — Warren Buffett, 2008 Shareholder Letter
Major Advantages
- Speed over bureaucracy: Buffett’s capital moves faster than government programs, filling gaps in liquidity during crises.
- Governance leverage: His investments come with demands for operational improvements, unlike traditional bailouts that lack accountability.
- No taxpayer cost: Unlike public bailouts, Buffett’s interventions are funded by private wealth, avoiding political backlash.
- Long-term alignment: His holdings are designed for decades, ensuring stability rather than short-term fixes.
- Market signal effect: His actions send a confidence boost to investors, often triggering broader rallies in distressed sectors.
Comparative Analysis
| Warren Buffett’s Bailout Model | Traditional Government Bailouts |
|---|---|
| Funded by private capital (Berkshire Hathaway’s net worth) | Funded by taxpayer money (e.g., TARP, ECB programs) |
| Conditions tied to governance reforms | Often lacks strict accountability mechanisms |
| Deployed within days of crisis onset | Subject to political delays (weeks/months) |
| Focuses on systemic risk reduction | Often targets individual institutions without broader impact |
| Creates moral incentive (private capital at risk) | Can encourage moral hazard (banks take excessive risks post-bailout) |
Future Trends and Innovations
As central banks explore private-public hybrid bailout models, Buffett’s "warren buffet net worth bailout" strategy is gaining traction. The European Central Bank’s 2020 pandemic-era bond purchases, for example, were partly inspired by Buffett’s crisis playbook—using private capital as a catalyst for public intervention. Looking ahead, the rise of family offices and sovereign wealth funds adopting Buffett-like approaches suggests a shift toward privatized crisis management. These entities, with net worths rivaling nations, may increasingly act as first responders in financial distress, reducing reliance on slow-moving governments. Another innovation could be structured bailout funds, where Buffett’s model is replicated by institutional investors. Imagine a $100 billion crisis response fund managed by Berkshire-like principles—deploying capital only in exchange for governance reforms. This could democratize the "warren buffet net worth bailout" approach, making it accessible to smaller institutions. The challenge? Scaling without losing Buffett’s discipline and patience. As markets grow more complex, the line between philanthropy and profit in bailouts will blur further—but Buffett’s legacy ensures that private wealth will remain a critical tool in financial warfare.
Conclusion
Warren Buffett’s "warren buffet net worth bailout" isn’t just a financial tactic; it’s a paradigm shift in how crises are managed. His ability to combine capital, influence, and long-term thinking has made him the ultimate financial stabilizer—a role that governments struggle to replicate. The 2008 crisis proved that private wealth can act as a force for systemic resilience, but it also exposed the limitations of public bailouts. As we face new economic challenges—from AI-driven disruptions to geopolitical tensions—Buffett’s playbook offers a blueprint for resilience. The question isn’t whether his model will evolve, but how quickly others will adopt it. The "warren buffet net worth bailout" isn’t just about money. It’s about leverage—of reputation, of patience, and of a willingness to take calculated risks when others falter. In an era where governments are stretched thin and markets demand speed, Buffett’s approach may well define the next generation of financial safety nets. One thing is certain: the Sage of Omaha didn’t just bail out banks. He redefined what a bailout could be.Comprehensive FAQs
Q: How much did Warren Buffett contribute to the 2008 financial bailout?
Buffett’s direct contributions during the 2008 crisis totaled around $15 billion across investments in Goldman Sachs, Bank of America, GE, and other institutions. This represented a significant portion of Berkshire Hathaway’s net worth at the time, demonstrating his commitment to stabilizing markets.
Q: Did Buffett’s bailouts make him money?
Yes, but not in the way most investors would expect. While his 2008 investments in Goldman Sachs and Bank of America didn’t yield massive short-term gains, they preserved capital and positioned Berkshire for long-term upside. For example, his Goldman stake later appreciated as the bank recovered, and his Bank of America investment was sold at a profit in 2011. The real return, however, was systemic stability—a non-financial but critical asset.
Q: Why didn’t Buffett take TARP funds?
Buffett avoided TARP for two reasons: speed and control. Government programs were bogged down in bureaucracy, whereas his private capital could be deployed immediately. Additionally, TARP came with political strings (e.g., executive compensation caps), which Buffett saw as counterproductive. His approach was to inject capital without imposing external governance, trusting that market forces would correct missteps.
Q: Has Buffett bailed out any non-financial companies?
While Buffett’s "warren buffet net worth bailout" focus has been on financial institutions, he has indirectly stabilized non-financial sectors through Berkshire’s diversified holdings. For example, his 2020 investments in airlines (Delta, Southwest) during the COVID-19 crisis were a form of bailout—though framed as long-term bets rather than rescue operations. These moves highlighted his willingness to support struggling industries when he saw value.
Q: What’s the difference between Buffett’s bailouts and traditional philanthropy?
Buffett’s interventions are strategic, not altruistic. Unlike philanthropy, which seeks social good without expectation of return, his "warren buffet net worth bailout" efforts are profit-motivated with a public benefit side effect. He demands governance changes, equity stakes, or operational improvements—ensuring that his capital creates value for Berkshire while stabilizing the broader economy.
Q: Could other billionaires replicate Buffett’s bailout model?
In theory, yes—but scale and reputation matter. Buffett’s net worth (~$130 billion) and decades-long track record give him unique leverage. Most billionaires lack his institutional trust or the ability to deploy capital without triggering market panic. That said, as more family offices and sovereign wealth funds adopt Buffett-like strategies, we may see a rise in privatized bailout models in future crises.
Q: Did Buffett’s bailouts prevent a worse recession?
Indirectly, yes. His 2008 interventions prevented the collapse of major financial institutions, which would have triggered a deeper recession. While economists debate the exact impact, Buffett’s moves reduced systemic risk by ensuring liquidity in key sectors. His approach was a complement to government actions, not a replacement—proving that private and public capital can work in tandem during crises.
Q: What’s the biggest criticism of Buffett’s bailout strategy?
The most common critique is that his "warren buffet net worth bailout" model favors the wealthy. By relying on private capital, he effectively subsidizes systemic stability for a select few while leaving broader economic recovery to governments. Critics argue that without public bailouts, smaller institutions and individuals bear the brunt of crises—a dynamic that played out in 2008 when Buffett’s interventions helped Wall Street but did little for Main Street.
