
The Complete Overview of Walmart Check Deposit
Walmart’s approach to check deposits reflects its dual role as both a retailer and a financial services provider. The system operates on two primary tracks: in-store cashing at any Walmart location and mobile deposits via the Walmart MoneyCard app. The former is the older, more widely recognized method, where customers hand over a check to a cashier in exchange for immediate funds—minus a fee. The latter, introduced more recently, allows users to snap a photo of the check through the app, with funds typically available within minutes. Both methods cater to different needs, from those who need physical cash to those who prefer digital transactions. What sets Walmart apart is its no-questions-asked policy for deposits up to a certain limit, though this isn’t universally true across all stores. The service also extends beyond its own MoneyCard holders: anyone with a valid ID can cash a check at Walmart, making it a go-to for gig workers, freelancers, or anyone waiting on a paper payment. However, the lack of transparency around fees—some stores charge $4, others $6, and a few waive fees for certain transactions—means customers often pay more than necessary. The system’s efficiency comes at a cost, and that cost isn’t always clearly communicated upfront.Historical Background and Evolution
The origins of Walmart’s check deposit service trace back to the early 2000s, when the company began offering third-party check cashing as a way to attract unbanked and underbanked consumers. At the time, Walmart was expanding its financial services beyond its in-house Walmart MoneyCard (launched in 2009) to include payroll card programs and prepaid debit options. Check cashing was a natural extension—it filled a void for customers who needed quick access to funds but lacked relationships with traditional banks. The service gained traction as Walmart’s store footprint grew, particularly in rural and underserved areas where banks were scarce. The real inflection point came with the rise of mobile banking and digital payments in the 2010s. Walmart responded by integrating mobile check deposits into its MoneyCard app, allowing users to deposit checks remotely without visiting a store. This move aligned with broader industry trends, as retailers like 7-Eleven and CVS also introduced similar services. However, Walmart’s scale—with over 4,700 U.S. locations—gave it a decisive edge. Today, the service is a cornerstone of Walmart’s financial ecosystem, processing hundreds of millions in transactions annually, according to industry estimates. Its evolution mirrors the broader financial inclusion movement, where retailers increasingly serve as de facto banks for those excluded from the traditional system.Core Mechanisms: How It Works
The process for depositing a check at Walmart depends on whether you’re using the in-store method or the mobile app. For in-store deposits, customers visit any Walmart location with a valid check and a government-issued ID. The cashier verifies the check, deducts the fee (typically $4–$6, though some stores offer discounts for frequent users), and hands over cash on the spot. The check is then held for up to 10 business days before being forwarded to the issuer for payment. Mobile deposits, available exclusively to Walmart MoneyCard holders, involve uploading a photo of the check through the app. Funds are usually available within one business day, though some checks clear faster. One often-overlooked feature is Walmart’s direct deposit integration for certain payroll providers. Employees of participating companies can have their paychecks automatically deposited onto their Walmart MoneyCard, bypassing the need for physical check deposits altogether. This hybrid model—combining in-person, mobile, and direct deposit options—makes Walmart’s service uniquely adaptable. However, the lack of a single, nationwide fee structure means costs can vary by region, and some stores may impose additional restrictions, such as limits on the number of checks cashed per day.Key Benefits and Crucial Impact
For millions of Americans, Walmart’s check deposit service is more than a convenience—it’s a financial safety net. The ability to convert a paper check into cash in minutes is invaluable for those living paycheck to paycheck, especially in emergencies. Unlike payday lenders, which often charge exorbitant interest rates, Walmart’s fees are fixed and predictable. This reliability has made the service a staple for gig economy workers, such as Uber and DoorDash drivers, who frequently receive payments via check or cash app. The service also plays a role in reducing reliance on high-cost alternatives like check-cashing stores or pawnshops, which can charge up to 3–5% of the check’s value. The impact extends beyond individual users. By providing a low-barrier entry point to financial services, Walmart helps bridge the gap for the unbanked, who often lack the credit history or documentation required for traditional accounts. Studies suggest that access to such services can improve financial literacy over time, as users become more comfortable managing transactions. Yet the service isn’t without criticism. Advocacy groups argue that the fees—while lower than those of payday lenders—still disproportionately affect low-income households. The lack of transparency in fee structures also leaves room for confusion, with some customers unaware they’re paying more than necessary."For people who don’t have bank accounts, Walmart is often the only game in town. The fees aren’t cheap, but the alternative—waiting days for a check to clear or dealing with a predatory lender—is worse." — Mechele Mink, financial inclusion expert and former CFPB advisor
Major Advantages
- Speed: In-store deposits provide cash in minutes, while mobile deposits clear within one business day—far faster than traditional bank processing times.
- Accessibility: No bank account required for in-store cashing; only a valid ID and the check itself.
- Widespread availability: Over 4,700 Walmart locations nationwide, including many in rural areas with limited banking options.
- Fee transparency (when known): Unlike payday lenders, Walmart’s fees are fixed and disclosed upfront, though they vary by location.
- Integration with Walmart MoneyCard: Mobile deposits and direct deposit options streamline recurring payments for frequent users.
- Emergency cash access: Ideal for unexpected expenses when traditional banking isn’t an option.
Comparative Analysis
| Feature | Walmart Check Deposit | Traditional Bank Check Deposit | Payday Lender Check Cashing |
|---|---|---|---|
| Processing Time | Minutes (in-store) / 1 business day (mobile) | 2–5 business days | Same-day (with high fees) |
| Fees | $4–$6 per check (varies by location) | $0 (for account holders) or $5–$15 (for non-customers) | Up to 3–5% of check value (e.g., $50 fee on a $1,000 check) |
| Account Required | No (in-store); Yes (mobile via MoneyCard) | Yes (checking/savings account) | No |
| Availability | All Walmart locations (24/7 for in-store) | Bank business hours | Limited to payday lender locations |
Future Trends and Innovations
Walmart’s check deposit service is likely to evolve in response to two major trends: regulatory pressure and technological innovation. As states tighten restrictions on payday lending and check-cashing fees, Walmart may face calls to standardize its pricing or offer fee waivers for certain transactions. The company has already experimented with discounted fees for frequent users, a model that could expand if regulators push for more consumer protections. Simultaneously, advancements in AI-driven fraud detection could speed up mobile deposits, reducing the one-day hold for high-risk checks. Another potential shift is deeper integration with fintech partnerships. Walmart has already collaborated with companies like Green Dot to expand its MoneyCard offerings, and future tie-ups could introduce features like instant check verification or cross-platform deposits (e.g., linking to external bank accounts). The rise of buy now, pay later (BNPL) services also suggests Walmart may explore hybrid models, where check deposits feed directly into installment payment plans. For now, the service remains a practical workaround for the unbanked—but its future could redefine how retail and finance intersect.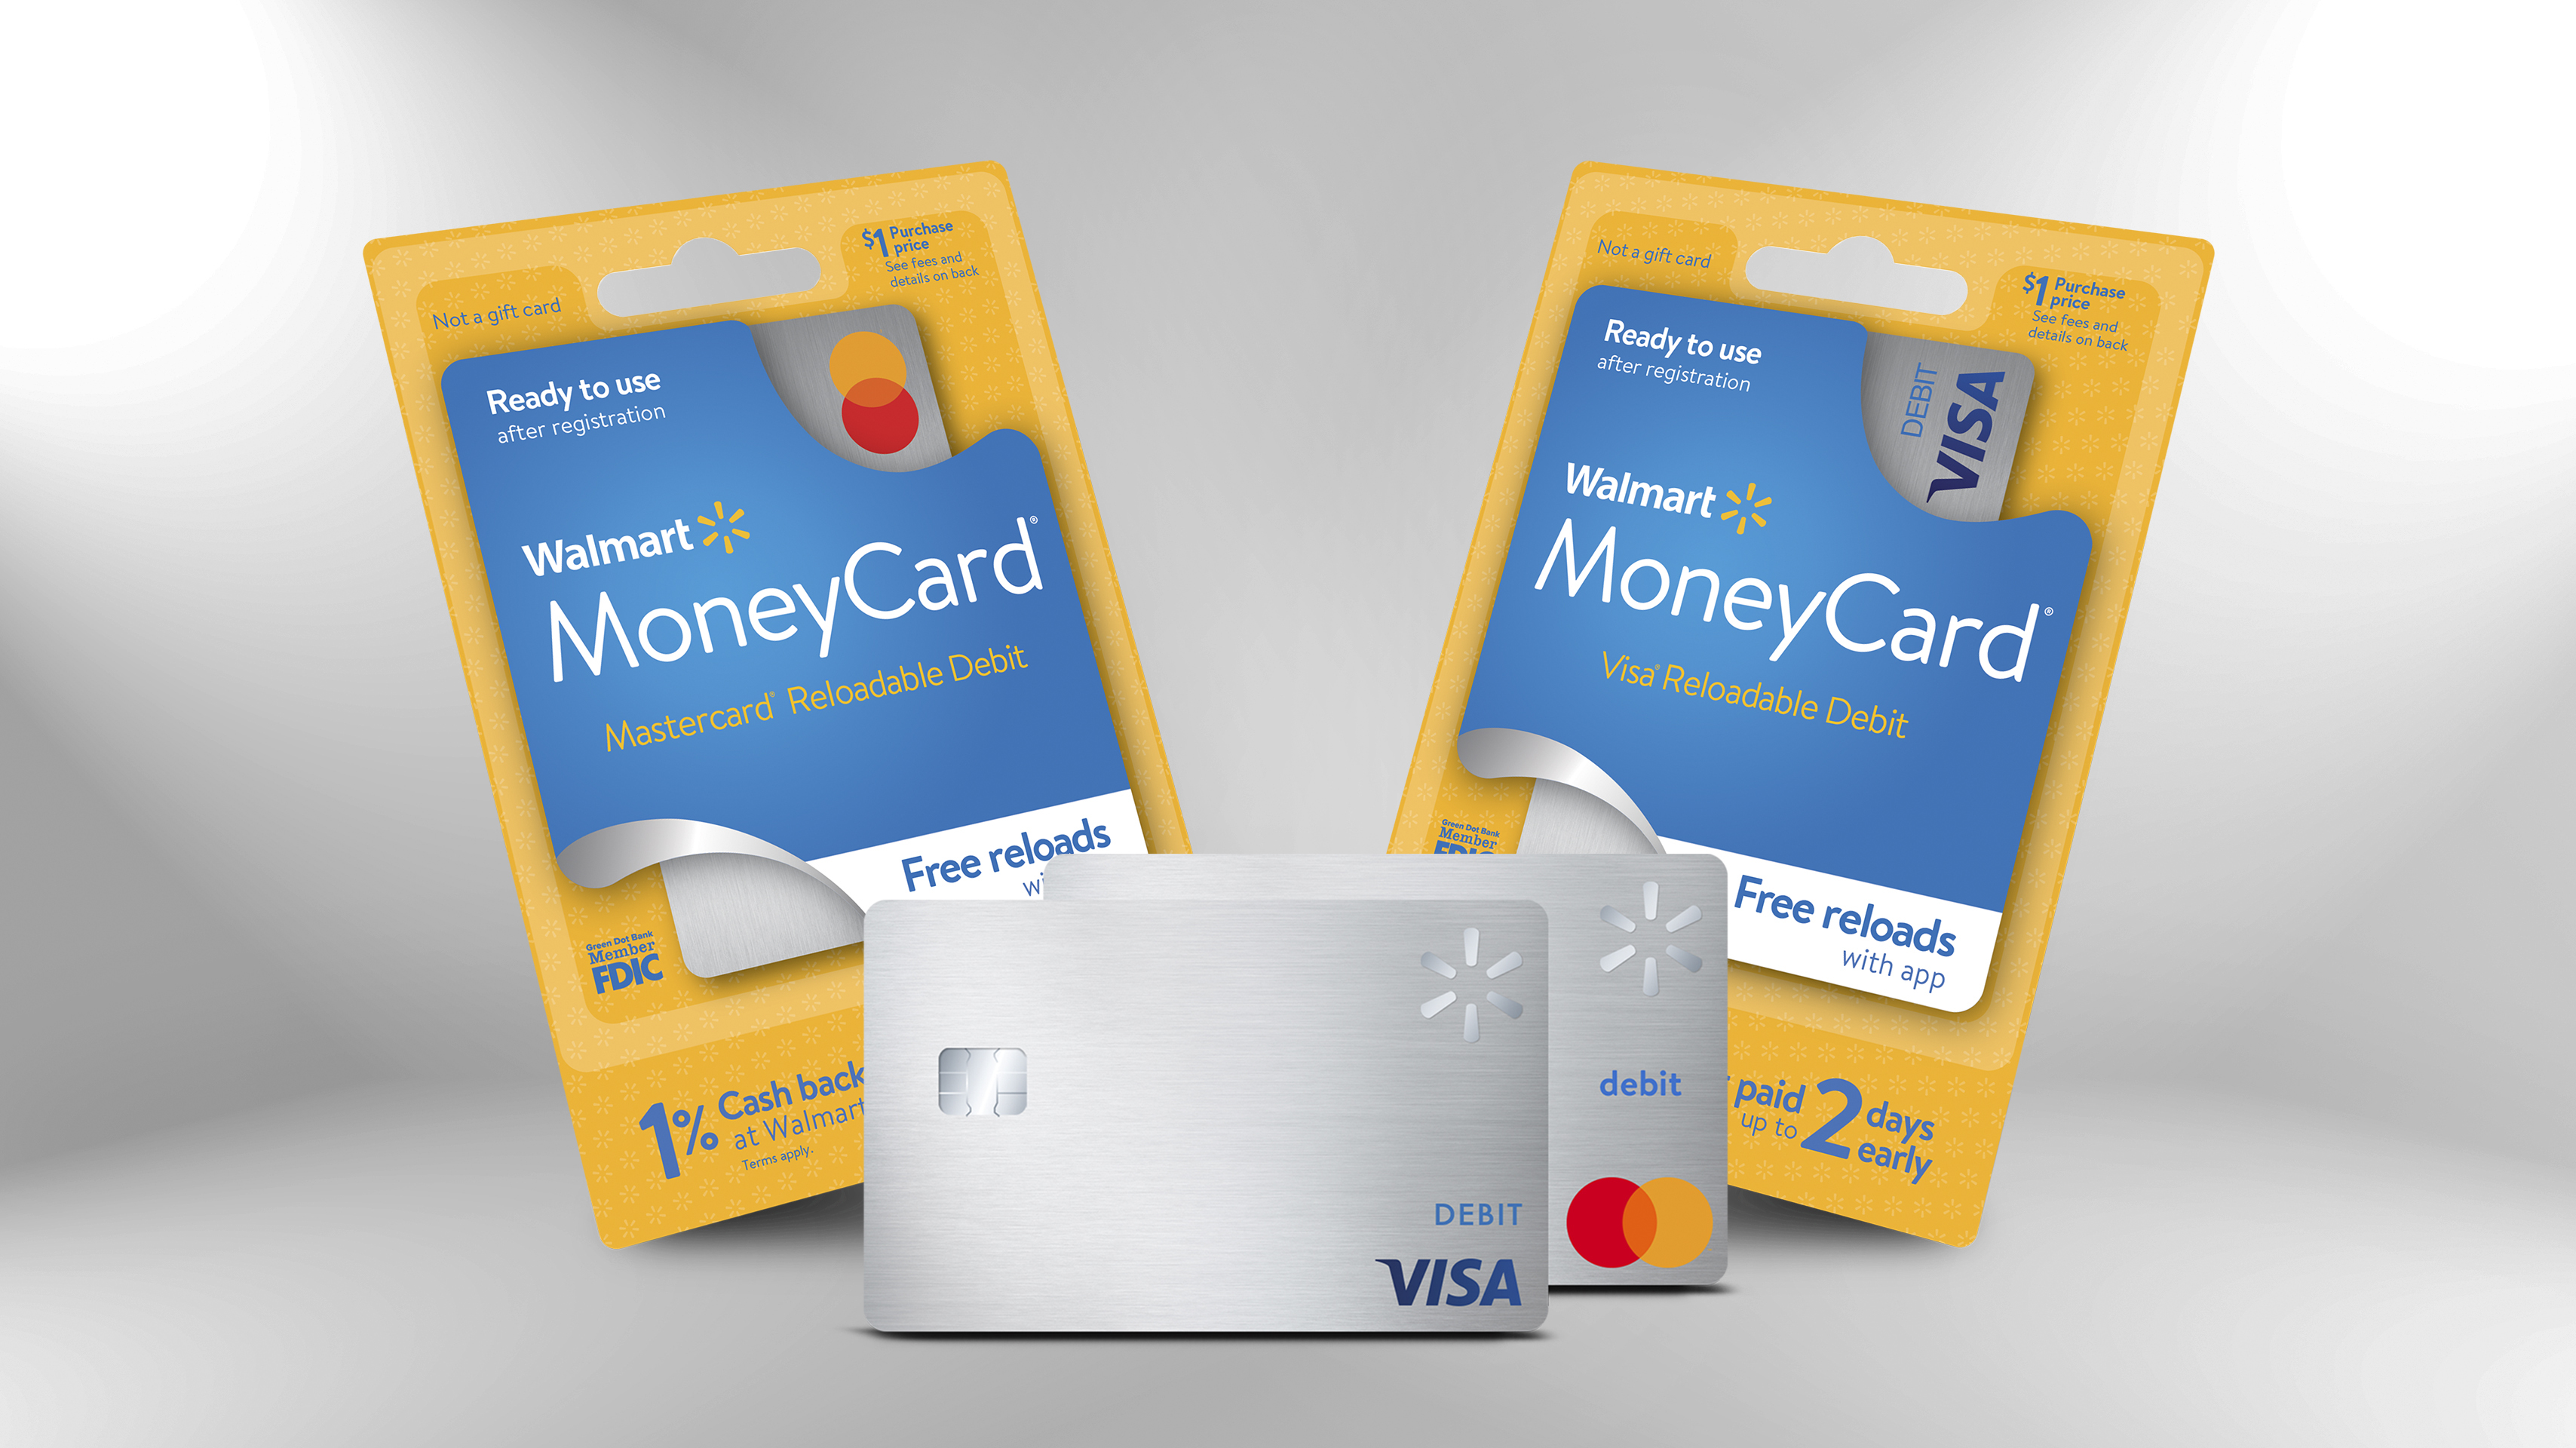
Conclusion
Walmart’s check deposit service is a testament to the power of retail as a financial gateway. It offers speed, accessibility, and a lifeline for those excluded from traditional banking—but at a cost that, while lower than alternatives, still demands scrutiny. The lack of uniformity in fees and the occasional opacity around policies highlight the need for clearer communication from Walmart. For users, the key is understanding the options: in-store vs. mobile, fee structures by location, and whether linking to a bank account could save money in the long run. As financial services continue to blur the lines between retail and banking, Walmart’s role will only grow. The service isn’t perfect, but for millions, it’s a necessary compromise between convenience and cost. The challenge ahead lies in balancing profitability with affordability—ensuring that Walmart’s financial offerings remain accessible without becoming another drain on low-income households.Comprehensive FAQs
Q: Can I deposit a check at Walmart without a Walmart MoneyCard?
A: Yes. Walmart allows anyone with a valid ID to cash a check in-store, regardless of whether they have a Walmart MoneyCard. Fees apply, but no account is required. Mobile deposits, however, are restricted to MoneyCard holders.
Q: How long does it take to get cash from a Walmart check deposit?
A: In-store deposits provide cash immediately after verification. Mobile deposits via the app typically make funds available within one business day, though some checks may clear faster. The actual check processing time with the issuer can take up to 10 business days.
Q: Are Walmart check deposit fees the same at every location?
A: No. Fees can vary by store, typically ranging from $4 to $6, though some locations may offer discounts for frequent users or waive fees for certain transactions. Always ask the cashier for the exact fee before proceeding.
Q: Can I deposit a check from another state at Walmart?
A: Yes, but there may be additional verification steps. Walmart accepts checks from any issuer, but out-of-state checks might require extra ID checks or hold periods. The bank or company issuing the check ultimately determines processing times.
Q: What happens if my Walmart check deposit is rejected?
A: Rejections usually occur due to insufficient funds, expired checks, or fraud flags. If this happens, the fee may still apply, and you’ll need to contact the issuer to resolve the issue. Walmart’s app or customer service can guide you through the process.
Q: Does Walmart offer direct deposit for paychecks?
A: Yes, through its Walmart MoneyCard payroll program. Certain employers partner with Walmart to automatically deposit paychecks onto the card, eliminating the need for physical check deposits. Check with your employer or Walmart’s payroll services for eligibility.
Q: Are there alternatives to Walmart for fast check deposits?
A: Yes. Other retailers like 7-Eleven, CVS, and Walgreens offer similar services, though fees and processing times vary. Banks and credit unions may also provide same-day check deposits for account holders, often with lower or no fees. Apps like Cash App or Venmo can also deposit checks quickly if linked to a bank account.
