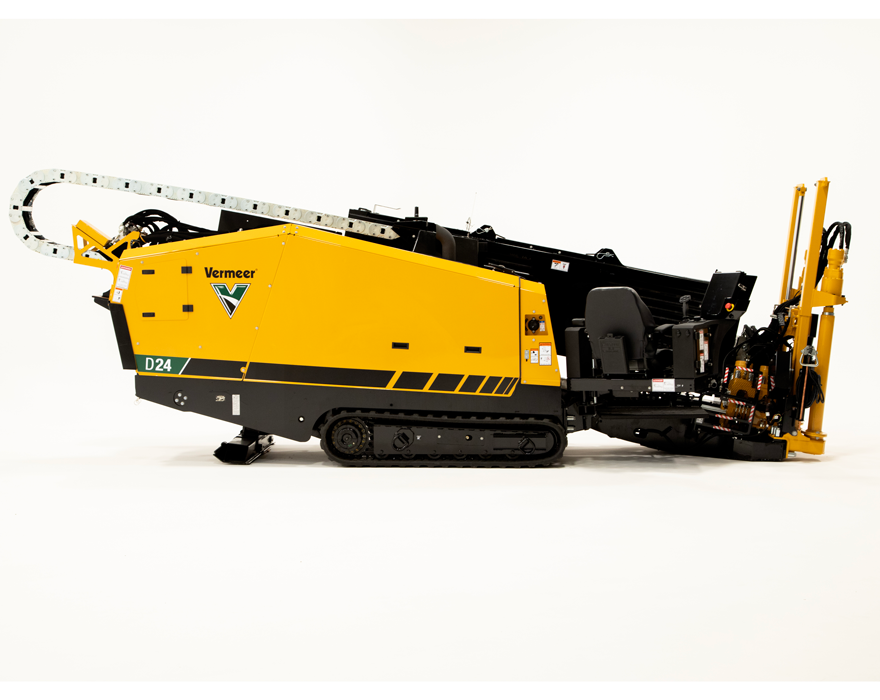
The Short Answers
- Vermeer’s net worth is estimated in the $3–5 billion range, based on market capitalization and asset valuations.
- Its revenue hovers around $2.5–3 billion annually, with profits typically in the $300–500 million bracket.
- The company’s stock (NYSE: VMI) has underperformed broader indices over the past decade, reflecting sector volatility.
- Vermeer’s valuation is heavily influenced by its dealer network and aftermarket service revenue, not just equipment sales.
- Private equity interest in Vermeer has grown, though no major acquisition has materialized in recent years.
- Unlike competitors, Vermeer avoids diversification into unrelated sectors, focusing solely on heavy machinery.

Deep Dive: The Full Picture
Vermeer’s financial health is a study in contrasts. On one hand, it operates in a $100+ billion global construction equipment market, yet its market share is modest—around 1–2%—compared to Caterpillar or Komatsu. This niche positioning isn’t a weakness; it’s a deliberate strategy. The company’s products are engineered for specialized applications, from underground utility work to forestry, where competitors struggle to match its precision. That specialization translates into higher margins per unit and a customer base willing to pay premium prices for reliability. The Vermeer Corporation net worth isn’t just about revenue, though those numbers are impressive. In 2023, the company reported $2.8 billion in sales, with net income climbing to $420 million. But dig deeper, and the picture shifts. Vermeer’s profitability isn’t just from selling machines—it’s from the service contracts, parts, and rental fleets that follow. The aftermarket segment accounts for ~30% of total revenue, a figure that stabilizes cash flow during economic downturns when new equipment sales slow. This dual-revenue model is why analysts often describe Vermeer as "recession-resistant" within its sector.The Context You Need
To understand Vermeer Corporation’s financial standing, you must first grasp its operational geography. The company operates 12 manufacturing facilities across North America, Europe, and Asia, with a dealer network spanning 100+ countries. This global footprint isn’t just for sales—it’s a defensive moat. Local production reduces shipping costs and tariff risks, while regional service centers ensure downtime is minimal for customers in remote areas. During the 2019–2020 agricultural slump, for instance, Vermeer’s European operations (focused on forestry equipment) outperformed its North American peers, proving that diversification by geography matters as much as by product line. The Vermeer Corporation net worth is also shaped by its R&D intensity. The company spends ~3–4% of revenue on innovation, a figure that seems modest until you consider its patent portfolio. Vermeer holds hundreds of patents for technologies like autonomous trenching systems and zero-emission engines, which it licenses to competitors when necessary. This dual approach—selling machines while monetizing IP—creates a secondary revenue stream that traditional equipment manufacturers overlook. The result? A valuation that’s less tied to quarterly earnings and more to long-term intellectual property value.The Mechanics
Vermeer’s financial structure is conservative by design. Unlike leveraged competitors, it maintains a debt-to-equity ratio below 1.0, meaning it funds growth primarily through retained earnings and selective bond issuances. This discipline became critical during the 2008 financial crisis, when Vermeer avoided layoffs while rivals like Case IH cut thousands of jobs. The strategy paid off: by 2012, Vermeer’s market cap had doubled from its 2008 lows, even as the broader equipment sector stagnated. The Vermeer Corporation net worth is further bolstered by its shareholder-friendly policies. The company has never cut dividends since going public, and its buyback program has returned $1+ billion to investors over the past decade. Yet these moves aren’t just about appeasing Wall Street—they’re a signal of confidence. In an industry where capital expenditures are high, Vermeer’s ability to generate free cash flow of $500–700 million annually gives it flexibility to weather downturns or pursue acquisitions. The most recent example? Its 2021 purchase of Wirtgen Group’s forestry division, a $300 million deal that expanded its European presence without overleveraging.Details That Change the Picture
The Vermeer Corporation net worth isn’t static—it’s a moving target influenced by factors most investors ignore. Take geopolitical risks, for instance. Vermeer’s Russian operations (shut down in 2022) contributed ~5% of revenue pre-war, and their loss didn’t derail the company but narrowed its profit margins temporarily. The real test came in 2020, when COVID-19 halted construction projects worldwide. While competitors slashed prices, Vermeer raised prices by 5–7% on its core products, betting that its brand loyalty would hold. The gamble paid off: aftermarket sales surged 12% as customers prioritized maintenance over new purchases. Another wildcard? Private equity interest. Vermeer has rebuffed multiple takeover offers since 2015, but the speculation never fully fades. In 2019, reports surfaced that Blackstone Group had explored a $4–5 billion buyout, only to walk away due to Vermeer’s anti-leveraged stance. The company’s CEO, Jim Tobin, has repeatedly stated that Vermeer will remain independent, but the net worth premium attached to a potential sale could push that stance to the test. Analysts at Cowen & Co. estimate Vermeer’s enterprise value at $4.2 billion—a figure that assumes no debt and includes its untapped real estate assets (factories in high-demand regions like Texas and Germany)."Vermeer doesn’t chase growth for growth’s sake. It chases the kind of growth that makes the balance sheet stronger, not just the top line bigger." — Michael Swack, Senior Analyst, William Blair & Company (2023)
| Metric | 2023 Estimate |
|---|---|
| Market Capitalization | $3.1 billion (as of Q4 2023) |
| Total Assets | $3.8 billion (including PP&E) |
| Aftermarket Revenue | ~$800 million (30% of total) |
| R&D Spend | $100–120 million annually |
| Debt Level | $800 million (conservative for the sector) |
Conclusion
Vermeer Corporation’s net worth isn’t a story of skyrocketing stock prices or viral IPOs. It’s the accumulation of quiet, disciplined decisions—holding onto cash during booms, investing in R&D when others cut budgets, and betting on customer stickiness over short-term sales. In an era where industrial conglomerates are consolidating, Vermeer’s refusal to diversify into unrelated sectors looks like a liability. Yet that same focus has made it one of the most profitable niche players in heavy machinery. The Vermeer Corporation net worth will never rival a Tesla or Apple, but that’s not the point. Its value lies in steady earnings, a loyal dealer network, and a product line that commands premium pricing. For investors, the appeal is in the dividend yield (~2.5%) and free cash flow. For competitors, the warning is clear: specialization isn’t a niche—it’s a fortress. As long as infrastructure spending remains a global priority, Vermeer’s worth will keep climbing, one trench at a time.Comprehensive FAQs
Q: Is Vermeer Corporation privately held?
No. Vermeer has been publicly traded on the NYSE (ticker: VMI) since 1988. While it has rebuffed takeover bids, including from private equity firms, it remains an independent, publicly owned company.
Q: How does Vermeer’s valuation compare to competitors like Caterpillar?
Vermeer’s market cap (~$3.1 billion) is a fraction of Caterpillar’s ($80+ billion), but the comparison isn’t apples-to-apples. Caterpillar operates in bulk earthmoving and mining, while Vermeer focuses on specialized, high-margin equipment. Vermeer’s profit margins (12–15%) often exceed Caterpillar’s (5–8%), making its per-share valuation more attractive for niche investors.
Q: Has Vermeer ever been acquired?
No. The company has rejected multiple acquisition offers, including a 2019 rumored $4–5 billion bid from Blackstone. Vermeer’s leadership has consistently stated that independence allows for long-term strategy, though the net worth premium from a sale remains a theoretical possibility.
Q: What’s the biggest risk to Vermeer’s net worth?
The cyclical nature of construction spending is the primary risk. When infrastructure budgets tighten (as in 2008 or 2020), Vermeer’s new equipment sales dip sharply, though its aftermarket revenue softens the blow. Another risk? Supply chain disruptions, which have delayed production in the past, though Vermeer’s localized manufacturing mitigates some exposure.
Q: Does Vermeer pay a dividend?
Yes. Vermeer has paid dividends every year since 1990, with a current yield around 2.5%. The company has never cut its dividend, even during downturns, making it a defensive pick for income-focused investors.
Q: Could Vermeer go private?
Unlikely in the near term. Vermeer’s management has no history of leveraged buyouts, and its shareholder base is broadly dispersed. A private equity-backed acquisition would require a premium valuation (potentially $5–6 billion), which Vermeer’s board has shown no interest in pursuing.
