
Common Myths About What Is Net Worth on a Balance Sheet
The first misconception is that net worth equals cash on hand. Many assume that if a company or individual has liquid assets, their net worth is equivalent to that bank balance. In reality, what is net worth on a balance sheet includes illiquid assets—real estate, inventory, or long-term investments—that can’t be converted to cash immediately. A tech firm with $500 million in R&D assets and $100 million in cash might have a net worth far exceeding its liquidity, yet investors often fixate on the latter. Another widespread error is treating net worth as synonymous with market value. A publicly traded company’s net worth on its balance sheet may differ sharply from its market capitalization, especially if the stock is overvalued or undervalued. For individuals, appraising assets like a family home or collectibles introduces subjectivity. The balance sheet’s net worth is an accounting construct, not a valuation—though the two can diverge significantly. The third myth is that net worth is a measure of profitability. A business with high net worth might still be unprofitable if its assets are depreciating faster than revenue grows. Conversely, a lean but cash-flow-positive company could have modest net worth but strong operational health. The balance sheet’s net worth is a snapshot of equity, not efficiency.Myth 1: Net worth is the same as cash reserves
The idea that what is net worth on a balance sheet mirrors available cash is a holdover from oversimplified financial literacy. Cash is a current asset, but net worth aggregates all assets—current and non-current—minus liabilities. A private equity firm might list $2 billion in assets (including illiquid stakes) but only $50 million in cash, yet its net worth would reflect the full portfolio value, not just liquidity. This confusion arises because cash is tangible and immediately usable, while net worth encompasses deferred value. For example, a manufacturing company’s net worth includes property, plant, and equipment (PPE) valued at historical cost minus depreciation. If the PPE is sold for more than its book value, the net worth increases—but the cash impact lags. The two metrics serve different purposes: cash measures liquidity; net worth measures equity.Myth 2: Net worth equals market capitalization for public companies
Public companies often face the misconception that their balance sheet net worth aligns with market cap. In reality, market cap is driven by investor sentiment, growth expectations, and multiples, while net worth is a conservative accounting figure. A company like Berkshire Hathaway, with a market cap in the hundreds of billions, might report a balance sheet net worth significantly lower due to conservative asset valuations and off-balance-sheet items. This disconnect is especially pronounced in sectors like tech, where intangible assets (patents, brand value) aren’t fully captured on the balance sheet. For individuals, the gap widens when assets like art or private equity stakes are appraised below market rates. The balance sheet’s net worth is a baseline; market perceptions can inflate or deflate it independently.Myth 3: High net worth means financial health
A bloated net worth doesn’t guarantee solvency. Consider a company with $10 billion in assets but $9 billion in debt—its net worth is $1 billion, yet it’s technically insolvent if it can’t service obligations. Similarly, an individual with a high net worth might be asset-rich but cash-poor, unable to meet short-term needs. What is net worth on a balance sheet is a starting point, not a verdict on financial well-being. The risk is compounded by leverage. A real estate investor with $50 million in property but $45 million in mortgages has a net worth of $5 million—but if interest rates rise, refinancing could become impossible. Net worth is a static measure; liquidity and cash flow are dynamic. The two must be assessed together.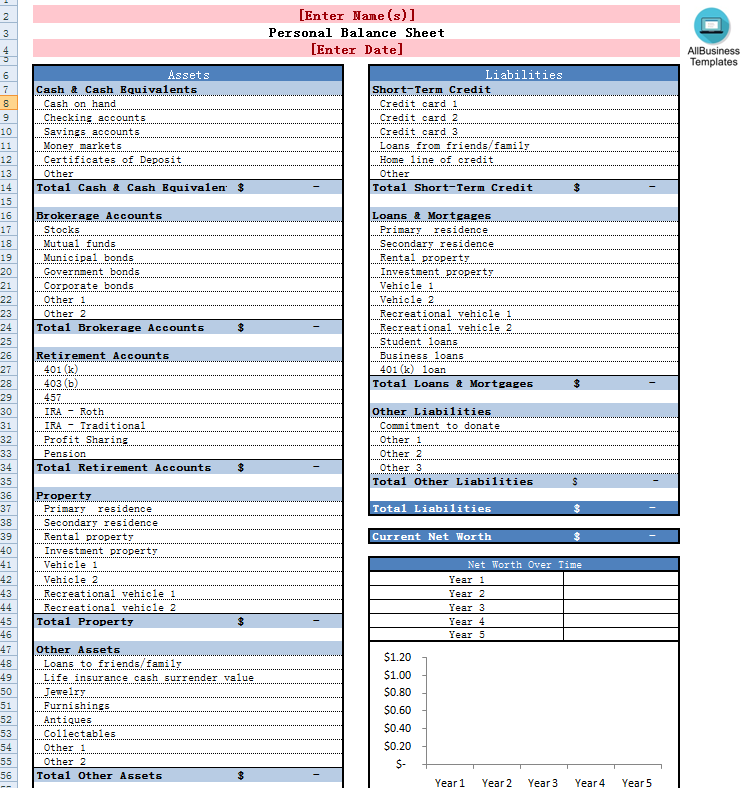
What Holds Up to Scrutiny
At its core, what is net worth on a balance sheet is the residual claim on assets after liabilities are settled. For a corporation, it’s shareholders’ equity; for an individual, it’s the difference between owned assets and owed debts. This definition is rooted in double-entry accounting, where every asset has a corresponding liability or equity entry. The net worth figure emerges from the balance sheet equation: Assets = Liabilities + Equity (Net Worth) The equity section—often labeled "shareholders’ equity" for companies or "owner’s equity" for sole proprietors—directly reflects net worth. It’s not a guess; it’s the result of recorded transactions, depreciation adjustments, and retained earnings. This precision is why net worth is a reliable (if sometimes incomplete) indicator of financial position. Yet even this clarity has limits. Balance sheets use historical cost accounting, meaning assets like land or machinery are recorded at purchase price minus depreciation, not current market value. For individuals, personal assets like a home may be undervalued or overvalued depending on appraisal methods. The net worth figure is thus a blend of objective accounting and subjective estimation."Net worth is the financial equivalent of a fingerprint—unique to each entity, shaped by its history, and only as accurate as the data behind it. The challenge isn’t calculating it; it’s interpreting what it truly represents in a given context." — Robert Kiyosaki (adapted from Rich Dad Poor Dad principles)
| Common Belief | What the Evidence Says |
|---|---|
| Net worth = cash available | Net worth includes all assets (liquid and illiquid) minus liabilities. Cash is only one component. |
| High net worth = financial stability | Net worth alone doesn’t account for leverage, liquidity, or cash flow. A highly leveraged entity with high net worth may still face insolvency risks. |
| Balance sheet net worth matches market value | For public companies, market cap often diverges due to investor sentiment. For individuals, appraised values may not reflect true market conditions. |
Why the Confusion Persists
The primary source of confusion is the dual role of net worth: it’s both a financial metric and a psychological benchmark. People equate net worth with success, security, or status, but the balance sheet’s version is a technical construct. The disconnect arises because personal finance often blends emotional and practical interpretations—what someone feels they’re worth versus what the books say. Accounting standards also play a role. Generally Accepted Accounting Principles (GAAP) and International Financial Reporting Standards (IFRS) prioritize consistency over market realism. Assets are recorded at cost, not fair value, creating a lag between economic reality and reported net worth. For individuals, the lack of standardized appraisal methods for personal assets (e.g., jewelry, vehicles) introduces further variability. Finally, the media and popular culture amplify the myth that net worth is a universal measure of wealth. Headlines about billionaires’ net worths ignore the fact that such figures often include unrealized gains, private valuations, or other non-liquid assets. The balance sheet’s net worth, by contrast, is a more grounded—but still imperfect—reflection of true financial standing.
Conclusion
Understanding what is net worth on a balance sheet isn’t about chasing a single number. It’s about grasping the framework that defines it: assets minus liabilities, shaped by accounting rules and real-world valuations. The myths persist because net worth straddles the line between finance and perception—what the books say and what people believe. For investors, the takeaway is to look beyond net worth to cash flow, leverage, and asset quality. For individuals, it’s recognizing that net worth is a tool, not a target. The balance sheet’s net worth figure is a starting point; the story of financial health is told in the details—how assets are used, how debts are managed, and how liquidity is maintained. In an era of instant wealth metrics, the balance sheet remains the most reliable (if often misunderstood) measure of what’s truly owned.Comprehensive FAQs
Q: Can net worth be negative on a balance sheet?
A: Yes. If liabilities exceed assets, the equity (net worth) section will show a negative balance. This indicates insolvency—more debts than the entity can cover with its assets. For companies, it may trigger bankruptcy proceedings; for individuals, it can limit credit access or asset liquidation options.
Q: How often should net worth be updated?
A: For businesses, net worth is updated with every financial reporting period (quarterly or annually). Individuals should reassess theirs annually or after major transactions (e.g., buying property, taking on debt). Frequent updates are less critical unless managing high-risk assets or leveraged positions.
Q: Does net worth include intangible assets like patents?
A: Only if they’re capitalized on the balance sheet. Under GAAP, intangibles acquired externally (e.g., purchased patents) are recorded at cost and amortized over time. Internally developed intangibles (e.g., brand value) are typically expensed and don’t appear as assets. For individuals, intellectual property is rarely included unless it’s a formal business asset.
Q: Why might a company’s net worth fluctuate even if its revenue is stable?
A: Revenue stability doesn’t guarantee net worth stability. Fluctuations can stem from asset revaluations, debt changes, share issuance, or one-time charges (e.g., goodwill impairments). For example, a company writing down inventory or taking on new loans will see its net worth adjust without revenue moving.
Q: Is personal net worth the same as investable net worth?
A: No. Personal net worth includes all assets (e.g., a primary residence, which may not be liquid). Investable net worth excludes non-liquid or restricted assets, focusing only on cash, securities, and easily tradable holdings. The latter is a subset of the former.
Q: How do off-balance-sheet items affect net worth?
A: Off-balance-sheet items (e.g., operating leases, contingent liabilities) don’t directly impact net worth but can influence financial health. For instance, a company with high off-balance-sheet debt may appear solvent on paper but face liquidity risks. Net worth reflects only what’s formally recorded, not hidden obligations.
Q: Can net worth be manipulated in financial statements?
A: Legally, no—net worth is derived from recorded assets and liabilities. However, creative accounting (e.g., overstating asset values, understating liabilities) can distort it. Regulators scrutinize such practices, especially in audits. For individuals, appraisal choices (e.g., overvaluing collectibles) can artificially inflate perceived net worth.
