Breaking Down the Numbers
The debt to tangible net worth ratio is calculated by dividing total debt (including mortgages, loans, credit cards, and business liabilities) by tangible net worth—the value of assets you could realistically sell minus debt secured by those assets. The result is a percentage that reveals how much of your net worth is encumbered by obligations. For instance, if your tangible assets (home, car, investments) total £1 million and your debt is £300,000, your ratio is 30%. That’s generally considered healthy. But if debt jumps to £600,000, the ratio doubles to 60%, a red flag. This metric is particularly useful for asset-heavy individuals—think real estate developers, luxury yacht owners, or those with significant private equity holdings. Unlike debt-to-income ratios, which only look at cash flow, the debt to tangible net worth ratio accounts for the collateral backing your obligations. A 40% ratio might feel safe if your assets are liquid (like stocks), but the same ratio could be risky if your debt is tied to illiquid assets (like a commercial property in a declining market).The Verified Baseline
Publicly traded companies disclose debt to tangible net worth in filings, but for individuals, the data is scarce. However, court records and bankruptcy filings occasionally reveal ratios for high-profile cases. For example, a 2019 UK court case involving a collapsed property empire showed a debt to tangible net worth ratio of 87% just before liquidation—far above the 50% threshold where lenders typically tighten terms. The individual’s £20 million portfolio was secured by £17 million in debt, leaving minimal equity. In the corporate world, firms like Blackstone or Bridgewater Associates publish leverage ratios, but their debt to tangible net worth figures are often buried in footnotes. For instance, Blackstone’s reported leverage (debt to equity) is around 5x, but when adjusted for tangible assets, the ratio drops—highlighting how asset composition changes risk profiles. The key takeaway: what is debt to tangible net worth ratio isn’t just about numbers; it’s about asset quality and liquidity.What the Estimates Suggest
Industry estimates suggest that individuals with ratios above 0.6 (60%) face higher refinancing costs and stricter lending terms. Wealth managers often advise clients to keep ratios below 0.4 (40%) for optimal flexibility. However, these benchmarks vary by sector. A private equity firm might operate at 0.7–0.8 due to high-yielding assets, while a family office might target 0.2–0.3 for liquidity. For real estate investors, the ratio can fluctuate wildly. During booms, leverage rises as property values inflate, but recessions expose overleveraged positions. A 2022 study by Savills found that UK property investors with debt to tangible net worth ratios above 0.5 saw equity erosion of 12–18% during the 2020 market correction. The lesson? What is debt to tangible net worth ratio isn’t static—it’s a snapshot of risk at a moment in time.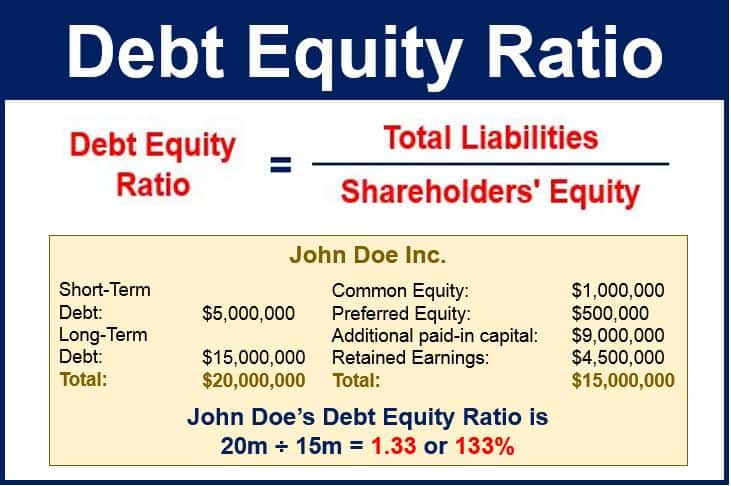
Case Study: A Closer Look
Consider the case of a luxury hotelier who expanded aggressively in the late 2010s. By 2020, their tangible net worth—hotels, land, and art collections—was estimated at £450 million, but £350 million of that was encumbered by debt. That’s a 78% ratio, far above safe thresholds. When COVID-19 hit, occupancy plummeted, and lenders demanded immediate repayments. The hotelier was forced to sell a £100 million yacht (a tangible asset) to cover margins, but the debt to tangible net worth ratio remained perilously high at 65%. The collapse wasn’t just about revenue—it was about asset liquidity. The yacht sale provided cash but didn’t reduce the underlying debt burden. Had the hotelier maintained a ratio below 50%, they might have weathered the storm with refinancing options."The moment your debt exceeds 50% of tangible net worth, you’re no longer in control—you’re at the mercy of asset values. And in downturns, values don’t just drop; they accelerate downward." — Simon Kuper, Partner at Kuper & Co. Wealth Advisory
| Factor | Estimated Impact on Ratio |
|---|---|
| Property market correction (20%) | Ratio increases by 15–20% due to lower asset values. |
| Refinancing at higher rates (3%) | Debt service costs rise, but ratio may stay flat if assets hold. |
| Sale of illiquid asset (e.g., vintage car) | Reduces debt but may not improve ratio if proceeds are reinvested. |
| New loan secured by existing property | Ratio spikes 10–30% depending on loan-to-value. |
| Inflation-driven asset appreciation (5%) | Ratio improves by 5–10% if debt remains unchanged. |
What This Means Going Forward
For individuals and businesses, the debt to tangible net worth ratio is a leading indicator of financial resilience. If your ratio is creeping above 0.4, it’s time to diversify assets or reduce leverage. High-net-worth families often use private credit lines to refinance debt before ratios become problematic. Meanwhile, investors in volatile sectors (like tech or commodities) may accept higher ratios if their assets have high upside potential. The metric also explains why lenders scrutinize tangible assets before approving loans. A £1 million home with a £600,000 mortgage has a 60% ratio—but if the home is in a declining market, the lender may demand a haircut (reducing the loan-to-value). Understanding what is debt to tangible net worth ratio helps borrowers anticipate these moves.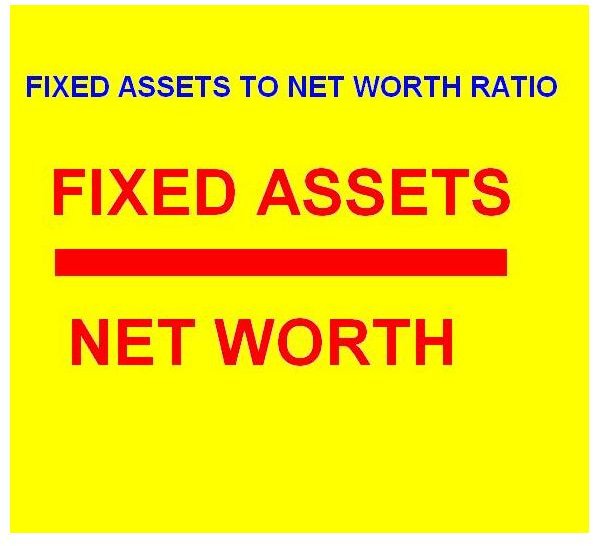
Conclusion
The debt to tangible net worth ratio is more than a number—it’s a barometer of financial vulnerability. Ignoring it can lead to forced sales, margin calls, or even insolvency. The good news? It’s one of the few metrics that forces a hard look at asset quality, not just income. For those with significant wealth tied to real estate or private investments, monitoring this ratio should be as routine as tracking stock portfolios. The takeaway isn’t to fear leverage entirely, but to structure debt in ways that align with asset liquidity. A 60% ratio might be acceptable for a blue-chip property portfolio, but deadly for a speculative venture. The key is context—and knowing what is debt to tangible net worth ratio is the first step toward managing it wisely.Comprehensive FAQs
Q: How often should I calculate my debt to tangible net worth ratio?
A: At least quarterly, especially if you have significant debt or volatile assets. High-net-worth individuals often review it monthly during market downturns or major transactions.
Q: Does this ratio apply to businesses as well as individuals?
A: Yes, but the calculation differs. For businesses, tangible net worth excludes goodwill and intangibles, focusing on physical assets and liquid reserves. Public companies report this as debt to tangible book value.
Q: Can a high ratio ever be a good thing?
A: Rarely, but in high-leverage, high-return strategies (like private equity or distressed asset investing), a ratio above 0.6 might be justified if the expected return on assets exceeds the cost of debt. However, this is speculative and risky.
Q: What’s the difference between this ratio and debt-to-equity?
A: Debt-to-equity compares debt to total equity (including intangibles like retirement accounts), while debt to tangible net worth excludes illiquid or subjective assets. The latter is stricter and more conservative.
Q: How do I improve a high ratio without selling assets?
A: Options include refinancing at lower rates, paying down high-interest debt, or adding liquid assets (like cash or marketable securities) to the tangible net worth denominator. Some also consolidate loans to reduce interest costs.
Q: Are there industries where high ratios are normal?
A: Yes. Real estate developers, private equity firms, and leveraged buyout (LBO) operators often maintain ratios between 0.7 and 0.9 due to high-yielding assets. However, these are high-risk, high-reward scenarios.
