The Short Answers
- A qualified institutional buyer must have a net worth of at least $100 million (or equivalent in other currencies) in assets under management.
- This threshold applies to entities, not individuals—private wealth managers or high-net-worth individuals do not qualify under this definition.
- Exemptions exist for certain pension funds, insurance companies, and foreign investors with equivalent regulatory recognition.
- The SEC’s Rule 144A governs QIB status, but state securities laws may impose additional requirements.
- Net worth is typically calculated based on total assets under management, not personal net worth.
- Failure to meet the threshold can result in restrictions on purchasing unregistered securities.
Deep Dive: The Full Picture
The concept of a qualified institutional buyer emerged from the need to create a tiered market structure where sophisticated investors could trade securities without the burdensome registration requirements imposed on public offerings. The a qualified institutional buyer must have a net worth of at least $100 million was codified in Rule 144A of the Securities Act of 1933, a rule that carved out an exemption for private placements. This exemption was a response to the inefficiencies of the public markets, where issuers faced high compliance costs and retail investors often lacked the sophistication to evaluate complex instruments. Over time, the threshold has remained largely stable, though its real-world application has evolved. The $100 million figure was chosen to reflect the scale at which institutions could reasonably be expected to conduct due diligence and absorb losses without materially disrupting markets. However, the definition has broadened to include not just capital but also the type of assets under management. For example, a hedge fund with $150 million in assets but primarily trading illiquid securities might still qualify, whereas a family office managing $120 million in liquid equities could face scrutiny if its investment strategy doesn’t align with institutional norms.The Context You Need
The regulatory framework for QIBs is rooted in the Securities Act of 1933 and its amendments, particularly Rule 144A, which was introduced in 1990. The rule was designed to facilitate private placements to institutional investors, allowing companies to raise capital more efficiently while still complying with securities laws. The a qualified institutional buyer must have a net worth of at least $100 million was set to ensure that only investors with the resources to evaluate and bear risk were included in these transactions. This threshold isn’t static. The SEC periodically reviews and adjusts definitions, though changes are rare. For instance, inflation or shifts in market structure could prompt a reassessment, but political and industry resistance often slows such adjustments. Additionally, the Dodd-Frank Act introduced further layers of oversight, particularly for larger institutional investors, though it did not directly alter the QIB net worth requirement. The stability of the $100 million figure belies its importance: it remains a bright-line test that separates institutional investors from all others.The Mechanics
The calculation of net worth for QIB eligibility is precise. The SEC defines it as the total assets under management (AUM) by the institution, not its personal or corporate net worth in the traditional sense. This means a private equity firm with $120 million in committed capital would qualify, while a corporation with $120 million in shareholders’ equity but no investment management arm would not. The focus on AUM ensures that only entities actively managing significant capital pools are included, reinforcing the rule’s intent to target sophisticated investors. There’s also a minimum ownership requirement: QIBs must own at least $100 million in securities of issuers that are not affiliated with them. This prevents entities from artificially inflating their AUM by holding securities of their own subsidiaries or related parties. The SEC’s guidance emphasizes that the calculation must be fair and reasonable, meaning institutions cannot exclude liabilities or use creative accounting to meet the threshold. Audited financial statements are often required to verify compliance, adding another layer of scrutiny.Details That Change the Picture
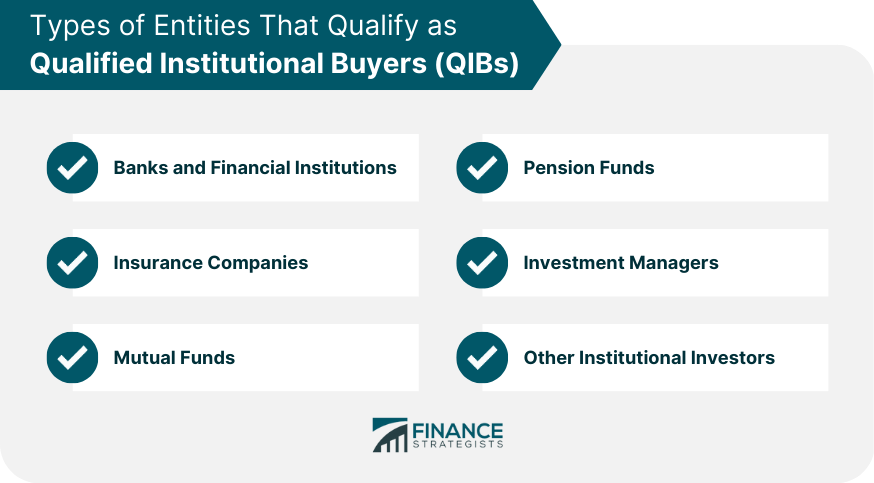
Not all institutional investors are created equal. While the a qualified institutional buyer must have a net worth of at least $100 million is the baseline, certain entities receive deemed QIB status without meeting the numerical threshold. For example, banks, savings institutions, insurance companies, and registered investment companies are automatically qualified, regardless of their AUM. This exemption reflects their inherent sophistication and the regulatory oversight they already undergo. Similarly, foreign institutional investors recognized by their home jurisdictions—such as the UK’s National Savings and Investments or Japan’s Government Pension Investment Fund—are often granted equivalent status under reciprocal agreements. The threshold also varies by jurisdiction. In the European Union, for instance, the MiFID II framework defines eligible counterparties with similar but not identical criteria, often tied to professional investor status rather than a fixed net worth. Meanwhile, Canada’s prospectus exemptions for institutional investors may reference $5 million CAD as a threshold, illustrating how global standards diverge. These differences create complexities for cross-border transactions, where institutions must navigate multiple regulatory landscapes to maintain QIB eligibility."The $100 million threshold isn’t just about money—it’s about signaling to the market that an investor operates with the discipline and resources to engage in unregistered transactions without destabilizing securities markets."
— SEC Division of Corporation Finance, 2022 Interpretive Guidance
| Entity Type | Net Worth Requirement |
|---|---|
| Private Equity Funds | $100M+ in committed capital (verified via audited financials) |
| Insurance Companies | Automatically qualified (no numerical threshold) |
| Foreign Sovereign Wealth Funds | Equivalent to $100M under reciprocal agreements (varies by country) |
Conclusion
The a qualified institutional buyer must have a net worth of at least $100 million is more than a regulatory hurdle—it’s a marker of institutional credibility. For issuers, it ensures access to a pool of investors capable of absorbing risk without the need for public disclosure. For investors, it opens doors to private markets that remain closed to retail participants. Yet the definition is not monolithic; exemptions, jurisdictional variations, and evolving interpretations mean that compliance requires careful navigation. As markets grow more complex and cross-border transactions become the norm, the QIB framework will continue to adapt. Whether through legislative changes, SEC reinterpretations, or global harmonization efforts, the core principle remains: institutional investors must demonstrate not just capital, but the operational maturity to participate in exempt securities transactions. For those on the cusp of qualification, the threshold isn’t just a number—it’s a rite of passage into the upper echelons of global finance.Comprehensive FAQs
Q: Can a single high-net-worth individual qualify as a QIB?
A: No. The QIB definition applies only to entities—such as funds, corporations, or financial institutions—not individuals, even those with substantial personal wealth. The a qualified institutional buyer must have a net worth of at least $100 million refers to assets under management by an institutional vehicle.
Q: Does the $100 million threshold include liabilities?
A: No. Net worth for QIB eligibility is calculated as total assets under management, not net assets (assets minus liabilities). However, institutions must ensure their AUM calculation is fair and not artificially inflated by excluding legitimate liabilities.
Q: Are there state-level variations to the QIB threshold?
A: While the federal Rule 144A sets the $100 million standard, some states impose additional requirements for intrastate offerings. For example, California’s Regulation D exemptions may have supplementary thresholds, though they typically defer to the federal definition for QIBs.
Q: Can a QIB lose its status if its AUM falls below $100 million?
A: Yes. The SEC expects institutions to continuously meet the threshold. If an entity’s AUM drops below $100 million, it may lose QIB eligibility retroactively, potentially invalidating recent transactions unless corrected promptly.
Q: How does a foreign institutional investor qualify under Rule 144A?
A: Foreign investors must demonstrate equivalent regulatory recognition in their home jurisdiction and meet the $100 million AUM threshold in their local currency (converted to USD at current rates). The SEC may also require audited financials or proof of compliance with home-country securities laws.
Q: What happens if an institution misrepresents its net worth to qualify as a QIB?
A: Misrepresentation can lead to SEC enforcement actions, including fines, mandatory disgorgement of profits, and temporary or permanent bars from participating in exempt transactions. The SEC has historically taken a hard line on fraudulent filings, even if the intent was to access private markets.
Q: Are there any upcoming changes to the QIB net worth threshold?
A: As of 2024, no formal proposals to adjust the $100 million threshold have been announced. However, industry groups have periodically advocated for inflation adjustments, and regulatory reviews under new administrations could prompt discussions. Monitor SEC rulemaking calendars for updates.
