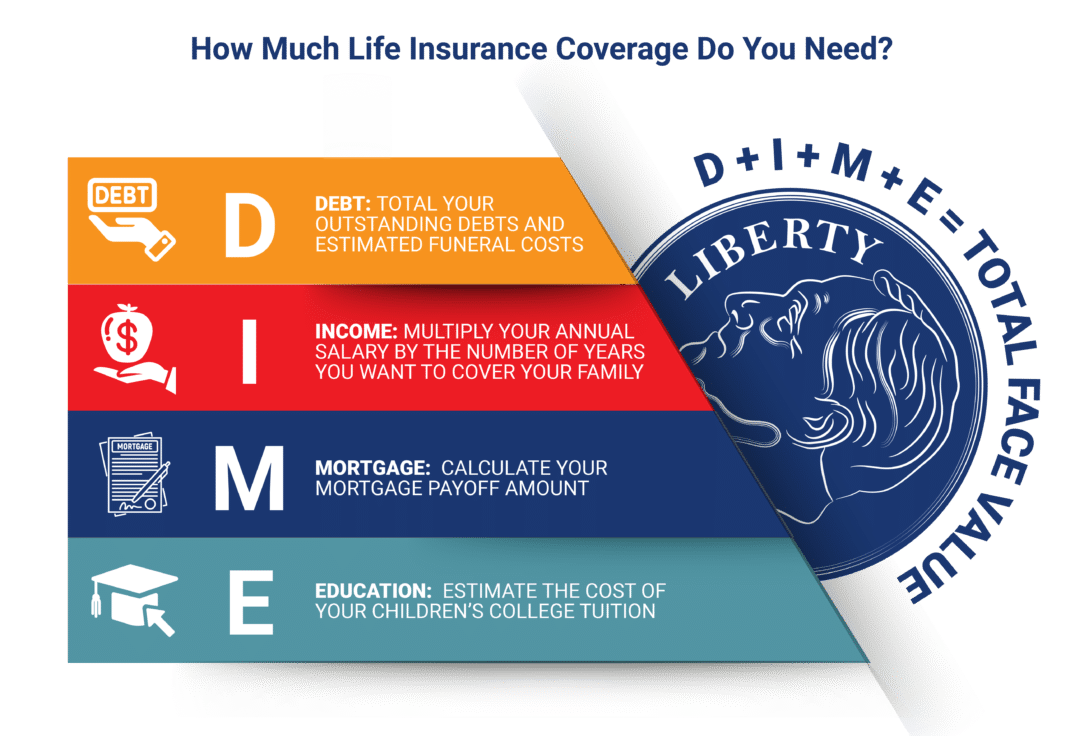
Life insurance policies are often sold as protection, but their
face value—the death benefit—can fundamentally alter a person’s net worth. The numbers don’t lie: a $1 million policy isn’t just a payout; it’s a liquid asset that can offset debts, fund trusts, or even become part of an heir’s taxable estate. Yet most discussions about net worth ignore this critical component, treating life insurance as a side note rather than a core financial instrument.
The disconnect stems from how people view insurance: as a cost, not an investment. But when structured properly, the face value of a life insurance policy can act as a silent wealth multiplier. It’s not about the premiums paid—it’s about the leverage created when that payout arrives. For high-net-worth individuals, this distinction matters more than ever, especially in an era where estate taxes and inflation erode traditional wealth transfer strategies.
The Short Answers
- The face value of life insurance net worth is the death benefit’s impact on an individual’s total assets, including tax implications and liquidity effects.
- Cash-value policies (whole life, universal) build equity over time, but the face value remains the primary driver of net worth changes upon death.
- Term policies offer pure face value at lower cost but don’t accumulate cash value—making them a net worth tool only if structured for specific needs (e.g., debt coverage).
- Estate planning treats the face value differently: payouts can reduce taxable estate size if structured as irrevocable life insurance trusts (ILITs).
Deep Dive: The Full Picture
Life insurance’s role in net worth calculations is frequently misunderstood because it operates in two financial dimensions simultaneously: as a
liability (premiums) and as an asset (death benefit). The face value—what beneficiaries receive—isn’t part of the policyholder’s net worth during their lifetime. But upon death, it becomes an immediate injection of capital that can alter an estate’s value, debt structure, or inheritance distribution. This duality is why financial advisors often describe life insurance as the only asset that grows in value when the owner dies.
The challenge lies in measuring this impact. Traditional net worth statements exclude life insurance face values because they’re contingent on mortality. Yet for families relying on that payout to cover mortgages, education funds, or business continuity, the face value effectively becomes a
guaranteed liquid asset—one that can offset other illiquid holdings like real estate or private equity. The key variable isn’t the policy’s cost but how its payout interacts with the insured’s broader financial picture.
####
The Context You Need
Most people conflate life insurance with savings or investments, but its primary function is
risk transfer. The face value isn’t an investment return; it’s a predefined payout designed to replace lost income or cover expenses. However, when integrated into estate planning, this payout can become a strategic tool for preserving net worth. For example, a policyholder with a $5 million estate might use a $2 million life insurance payout to pay estate taxes, leaving heirs with the full $5 million intact—a scenario where the face value directly enhances net worth for beneficiaries.
Industry data shows that high-net-worth individuals (HNWIs) increasingly treat life insurance as part of their
wealth preservation toolkit, not just a safety net. According to recent surveys, over 60% of HNWIs with estates exceeding $10 million hold life insurance policies primarily for tax efficiency, not income replacement. This shift reflects a growing awareness that the face value of life insurance can function as a tax-advantaged asset, especially when paired with trusts or charitable remainder annuities.
####
The Mechanics
The mechanics of how the face value affects net worth depend on two factors:
policy type and estate structure. Term life policies, for instance, provide a pure face value with no cash accumulation. Their net worth impact is binary: either the payout occurs (boosting the estate’s liquidity) or it doesn’t. Whole life and universal life policies, however, introduce cash value—a secondary component that can be borrowed against or surrendered, further complicating net worth calculations.
Tax treatment is where the face value’s role becomes most critical. Under U.S. law, life insurance proceeds are generally
income-tax-free to beneficiaries, but they may be subject to estate taxes if the policy remains in the insured’s estate at death. This is where irrevocable life insurance trusts (ILITs) come into play: by transferring ownership of the policy to the trust, the face value is removed from the taxable estate, potentially reducing estate taxes by millions. In this context, the face value isn’t just a payout—it’s a tax mitigation vehicle that can preserve net worth for future generations.
Details That Change the Picture
Not all life insurance policies are created equal when it comes to net worth impact. The difference between a $1 million term policy and a $1 million whole life policy isn’t just in premiums—it’s in how each interacts with the insured’s financial ecosystem. Term policies are cheaper but offer no cash value, making them ideal for debt-specific net worth protection (e.g., covering a mortgage). Whole life policies, meanwhile, build cash value over time, which can be tapped during the insured’s lifetime, effectively increasing their net worth while the policy is active.
The catch? Cash value growth is slow and often outpaced by inflation. For many policyholders, the real net worth boost comes from the face value’s role in estate equalization. Families with uneven inheritances might use life insurance payouts to balance distributions, ensuring that all heirs receive equal shares despite differences in other assets. This strategy turns the face value into a net worth equalizer, not just a payout.

"Life insurance isn’t just about leaving money behind—it’s about leaving money behind in the most tax-efficient way possible. The face value becomes the difference between an estate shrinking by 40% to taxes and one that transfers wealth intact."
— Estate planning attorney, 2023
| Policy Type |
Net Worth Impact |
| Term Life |
Pure face value payout; no cash accumulation. Best for debt/liquidity needs. |
| Whole Life |
Face value + cash value growth. Can borrow against or surrender for net worth boost during lifetime. |
| Universal Life |
Flexible premiums; face value adjustable. Cash value tied to market performance. |
| ILIT-Funded Policy |
Face value removed from taxable estate. Primary tool for tax-efficient wealth transfer. |
Conclusion
The face value of life insurance isn’t a static number—it’s a dynamic variable that can either preserve or erode net worth, depending on how it’s structured. For individuals with complex estates, the decision to hold a policy inside an ILIT or as a standalone asset isn’t just about coverage; it’s about optimizing the face value’s role in wealth transfer. The policies that perform best in this regard are those that align the death benefit with the insured’s broader financial goals, whether that’s minimizing taxes, funding a business, or ensuring equal distributions.
The mistake many make is treating life insurance as a one-size-fits-all solution. In reality, its impact on net worth varies wildly based on policy type, ownership structure, and estate planning. The most sophisticated approach isn’t to maximize the face value alone but to integrate it into a cohesive wealth strategy—one where the payout serves as a catalyst for preserving, not just replacing, financial security.
Comprehensive FAQs
#### Q: Does the face value of life insurance count toward my net worth while I’m alive?
A: No. The face value is a future payout and isn’t included in net worth calculations during the policyholder’s lifetime. However, the cash value of permanent policies (whole, universal) is part of your net worth and can be accessed through loans or withdrawals.
#### Q: Can life insurance reduce my taxable estate?
A: Yes, if structured properly. Placing a policy in an irrevocable life insurance trust (ILIT) removes the face value from your taxable estate, potentially saving hundreds of thousands in estate taxes. Without this structure, the payout may be subject to estate tax if your total assets exceed the federal exemption threshold.
#### Q: How does a term policy affect net worth compared to whole life?
A: Term policies offer pure face value protection at lower cost but provide no cash accumulation. Whole life policies include cash value, which grows tax-deferred and can be borrowed against, effectively increasing your net worth over time. However, whole life premiums are significantly higher, so the net worth trade-off depends on your financial priorities.
#### Q: What happens to the face value if I outlive the policy?
A: If you cancel a term policy before death, you receive nothing—the face value is forfeit. With permanent policies (whole, universal), you may recover cash value, but the face value is only paid upon death. Some policies offer return-of-premium riders, which refund premiums if you outlive the term, but these increase costs.
#### Q: Can life insurance be used to equalize inheritances among heirs?
A: Absolutely. Families with uneven asset distributions often use life insurance payouts to balance inheritances. For example, if one heir receives a business and another gets cash, a policy can ensure both receive equal net worth upon the parent’s death.
#### Q: Does the face value affect my credit score or financial ratios?
A: No. Life insurance premiums aren’t factored into credit scores, and the face value doesn’t appear on balance sheets. However, if you take a loan against the cash value of a permanent policy, that debt could impact your debt-to-income ratio, similar to other loans.