
The Short Answers
- Gross for investments is the total value of all assets before accounting for debts or obligations.
- Net worth subtracts liabilities (debts, taxes owed, legal judgments) from gross assets to show real financial capacity.
- Tax authorities and lenders almost always use net worth, not gross totals, for assessments.
- Illiquid assets (real estate, private equity) can distort the difference between net worth and gross for investments.
- High-net-worth individuals often restructure holdings to optimize this gap for tax or inheritance purposes.
Deep Dive: The Full Picture
The difference between net worth and gross for investments lies at the heart of financial transparency. While gross figures dominate headlines—think of a CEO’s "portfolio worth $1 billion"—the net calculation tells a far more precise story. For instance, a hedge fund manager might boast a gross AUM (assets under management) of $15 billion, but after fees, counterparty risks, and pending lawsuits, their net liquidity could be a fraction of that. This gap isn’t just a footnote; it dictates whether the manager can meet margin calls, pay bonuses, or even retain key talent. What’s often overlooked is how this distinction plays out across asset classes. Publicly traded stocks, for example, are straightforward to value, but private companies or art collections may require appraisals that fluctuate wildly. A family office holding a 20% stake in a pre-IPO startup might list that stake at a gross valuation of $50 million—yet if the startup’s burn rate is unsustainable, the net realizable value could plummet. The difference between net worth and gross for investments thus becomes a moving target, especially in volatile markets.The Context You Need
Historically, the gross-net divide was critical in medieval merchant ledgers, where traders recorded total cargo values before deducting loans or damages. Today, the principle persists in modern finance, though the stakes are higher. Consider Warren Buffett’s Berkshire Hathaway: its gross book value might exceed $100 billion, but after accounting for intangible assets, deferred taxes, and contingent liabilities, the net equity picture differs significantly. This isn’t just semantics—it affects how analysts rate the company and how shareholders interpret its financial health. The confusion arises because gross figures are easier to communicate. A politician might tout a "gross investment boom" in their district, while the actual net benefit to residents—after infrastructure costs—could be negligible. Similarly, a family’s gross estate might be $100 million, but after estate taxes and charitable pledges, the heirs receive far less. The difference between net worth and gross for investments thus becomes a battleground for perception versus reality, particularly in public discourse.The Mechanics
At its core, the calculation is simple: gross assets minus liabilities equals net worth. However, the challenge lies in defining what counts as an asset or liability. For instance, a leveraged buyout might inflate gross figures temporarily, but the debt servicing obligations drag down net worth. In private equity, a fund’s gross committed capital might be $10 billion, but after dry powder (uninvested capital) and management fees, the net deployable capital is lower. Tax authorities exploit this distinction rigorously. The IRS, for example, assesses wealth taxes based on net worth, not gross totals. A billionaire with $2 billion in assets but $1.8 billion in mortgages or legal settlements might owe far less in taxes than their gross figure suggests. Similarly, lenders evaluate loan applications using net worth, not the sum of all assets. A real estate developer with $30 million in properties but $25 million in outstanding construction loans will struggle to secure additional financing, despite their gross asset total.Details That Change the Picture
The difference between net worth and gross for investments becomes especially pronounced in illiquid markets. A family holding a controlling stake in a struggling airline might see that stake valued at $200 million on paper, but if the airline’s debt exceeds $180 million, the net worth contribution is minimal. Conversely, a portfolio heavy in cash or blue-chip stocks will show a tighter gap between gross and net figures, as liabilities are minimal. This dynamic also explains why ultra-high-net-worth individuals (UHNWIs) often structure holdings to maximize net worth relative to gross totals. Trusts, offshore entities, and charitable remainder trusts are tools to reduce taxable liabilities, thereby widening the gap between the two metrics. For example, a philanthropist might transfer assets into a foundation, reducing their gross personal holdings while preserving net worth for heirs."The gross number is what you tell the world. The net number is what you tell your banker—and your children." — Financial advisor to a Fortune 500 CEO
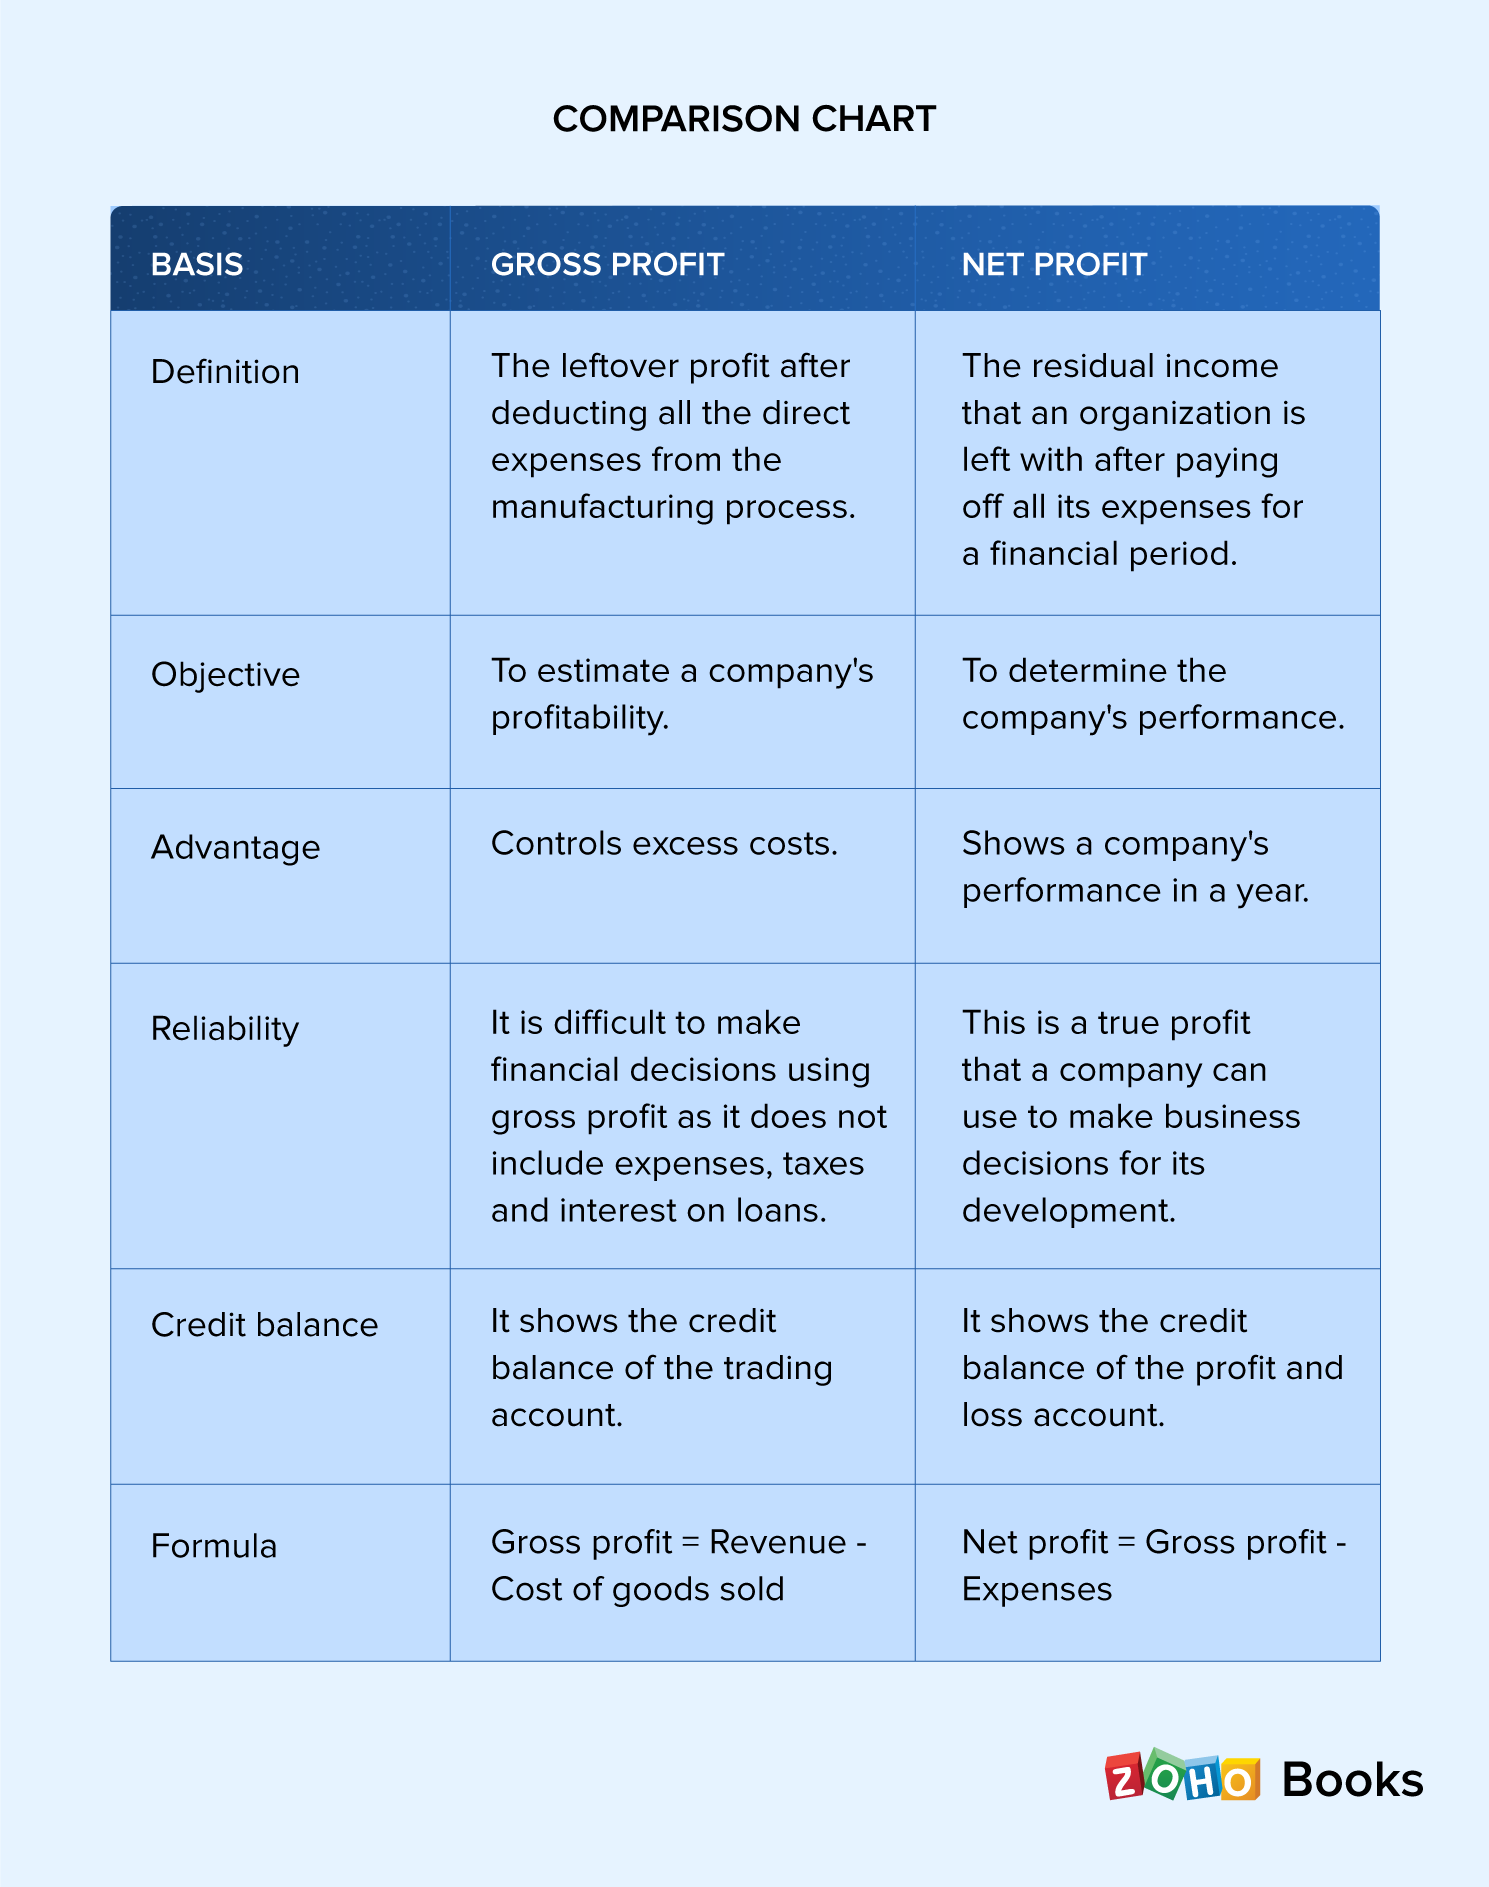
| Metric | Definition |
|---|---|
| Gross Assets | Total value of all investments, property, and holdings without deductions. |
| Net Worth | Gross assets minus all liabilities (debts, taxes, legal obligations). |
| Liquid Net Worth | Net worth excluding illiquid assets (e.g., real estate, private equity). |
| Adjusted Net Worth | Net worth after accounting for inflation, market volatility, or pending legal claims. |
| Reportable Net Worth | Net worth as disclosed to tax authorities or lenders, often after exclusions. |
Conclusion
The difference between net worth and gross for investments isn’t a trivial accounting exercise—it’s the difference between financial illusion and reality. Gross figures dominate narratives, but net worth dictates what can actually be done with those assets. For individuals, this means the gap between perception and action; for institutions, it’s the difference between solvency and insolvency. Ignoring this distinction can lead to poor decisions, whether in estate planning, tax strategy, or investment allocation. Understanding these metrics isn’t just about crunching numbers; it’s about recognizing that wealth isn’t static. A portfolio’s gross value can remain unchanged while its net worth erodes due to market downturns or new liabilities. The key for investors is to track both figures closely—gross to assess scale, net to assess capability—and adjust strategies accordingly.Comprehensive FAQs
Q: Can gross investment figures ever be higher than net worth?
A: Yes, but only if liabilities are negative (e.g., tax refunds or pending settlements). In most cases, gross figures are higher, but the gap reveals financial leverage or risk exposure.
Q: Do lenders care about gross or net worth when evaluating loans?
A: Lenders focus on net worth, as it reflects true liquidity. A high gross total with significant debt may still result in loan denial.
Q: How do taxes affect the difference between net worth and gross for investments?
A: Taxes are a liability that reduces net worth. For example, capital gains taxes or estate duties can shrink net worth significantly, even if gross assets remain unchanged.
Q: Can restructuring assets (e.g., trusts) artificially inflate net worth?
A: No, but it can optimize the gap by reducing taxable liabilities. Trusts, for instance, may shield assets from estate taxes, preserving net worth for heirs.
Q: Why do public figures often highlight gross figures instead of net worth?
A: Gross figures are more impressive and easier to communicate. Net worth, by contrast, requires disclosure of debts—something many prefer to avoid.
Q: How does market volatility impact the difference between net worth and gross for investments?
A: Volatility can widen or narrow the gap. A downturn may reduce gross asset values but also force sales, increasing liabilities and shrinking net worth further.
Q: Are there industries where the difference between net worth and gross for investments is most pronounced?
A: Yes. Real estate, private equity, and leveraged buyouts often show large gaps due to high debt levels. Publicly traded stocks, by contrast, typically have narrower gaps.
Q: Can net worth ever be negative?
A: Yes, if liabilities exceed assets. This is common in highly leveraged businesses or during financial crises.
