The Short Answers
- Fred households typically have net worth levels well below national medians, often clustering around the lower quartile of wealth distribution.
- Nonprofit organizations serving these households rely on a mix of grants, donations, and earned revenue, with financial resilience varying widely by size and mission.
- The net worth gap between Fred households and higher-income groups is exacerbated by systemic barriers like predatory lending, lack of intergenerational wealth transfer, and limited access to high-yield assets.
- Nonprofits with strong community ties often see higher engagement from Fred households, though their own net worth stability depends on donor trends and economic cycles.
- Policy interventions—such as asset-building programs or nonprofit capacity grants—can influence both household net worth and organizational sustainability, but results are uneven.
Deep Dive: The Full Picture
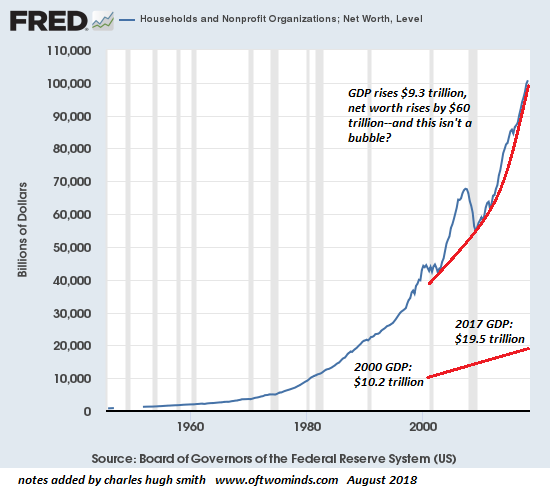
The financial landscape of Fred households is defined by three interconnected factors: limited liquid assets, high levels of debt (particularly in housing and education), and minimal exposure to wealth-generating investments. Studies consistently show that these households accumulate net worth at a fraction of the rate seen in higher-income brackets, a trend that persists across generations. The median net worth for a Fred household—often defined as one earning between $30,000 and $50,000 annually—can be as low as $5,000 to $10,000, according to Federal Reserve data, compared to national averages that hover around $130,000. This disparity isn’t just a matter of income; it reflects deeper structural issues, including the erosion of unionized labor, stagnant wage growth, and the rising cost of essentials like healthcare and childcare. Nonprofit organizations operating within these communities face their own set of financial constraints. While some larger nonprofits boast net assets in the millions—thanks to endowments, corporate partnerships, or government contracts—many grassroots organizations operate on shoestring budgets, with annual revenues barely exceeding $100,000. The net worth level of these nonprofits is often tied to their ability to secure recurring funding, a challenge that has intensified in recent years as philanthropic dollars become more competitive. Smaller nonprofits, in particular, struggle with overhead costs, making it difficult to reinvest in programs that could directly impact Fred household net worth, such as homeownership counseling or financial coaching.The Context You Need
The term fred households and nonprofit organizations net worth level gained traction as economists and policymakers sought to quantify the financial divide between America’s working poor and the broader economy. The concept emerged from research highlighting how households in the lower income tiers—despite steady employment—frequently lack the financial buffers to weather unexpected expenses. Nonprofits, historically the first responders to such crises, have seen their roles evolve from emergency relief to long-term asset-building. Yet this shift requires capital, and the net worth of the organizations themselves becomes a limiting factor. Consider the case of a community development nonprofit aiming to increase homeownership rates among Fred households. The program’s success depends on access to low-interest loans, but the nonprofit’s ability to underwrite these loans is constrained by its own balance sheet. If its net worth is thin, it may struggle to secure partnerships with banks or qualify for grants that could scale the initiative. Conversely, a nonprofit with stronger financial health might offer more robust services—but it may also face pressure to prioritize donors over community needs. The tension between mission and sustainability is a defining feature of this dynamic.The Mechanics
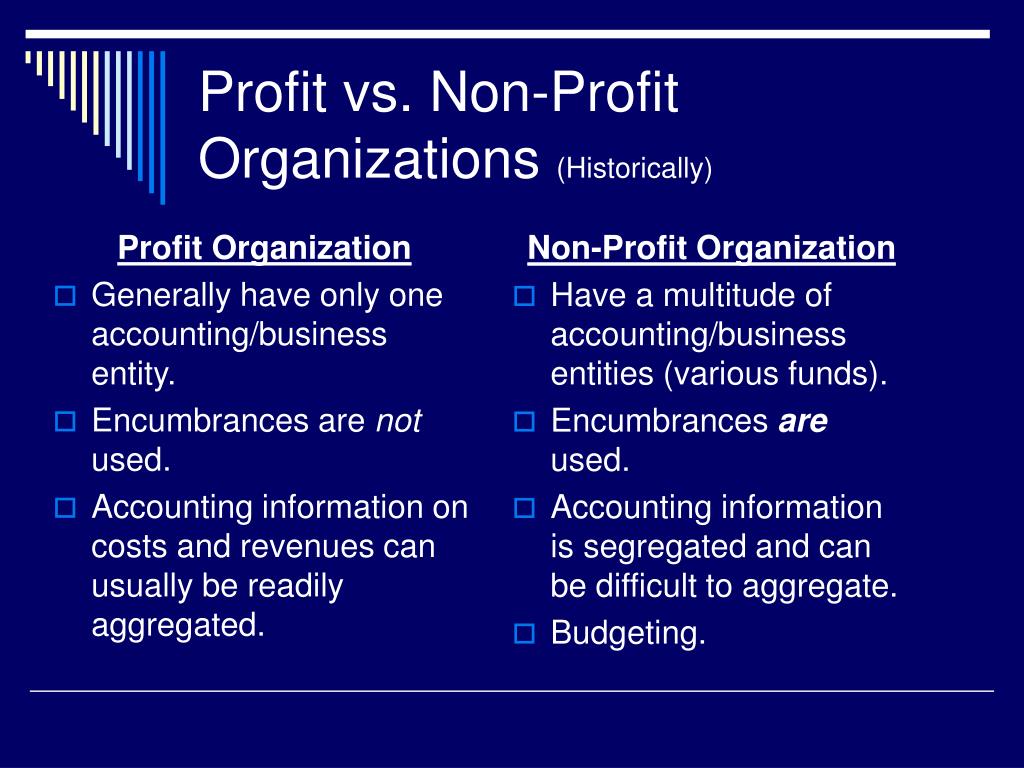
The mechanics of net worth accumulation for Fred households differ sharply from those of higher-income groups. For the latter, wealth often builds through home equity, retirement accounts, and stock portfolios—assets that compound over time. Fred households, by contrast, rarely participate in the stock market and may lack the credit history or collateral to secure mortgages. Their net worth is more likely to consist of tangible but illiquid assets, such as a used car or household goods, which offer little protection against economic shocks. Nonprofits, meanwhile, operate under a different set of financial rules. Their net worth is typically measured by unrestricted funds, endowments, and fixed assets like office buildings or vehicles. Larger nonprofits with diversified revenue streams—think universities or hospitals—can weather downturns more easily, but even they are not immune to the ripple effects of economic instability. Smaller nonprofits, which often serve Fred households directly, are more vulnerable. Their net worth may fluctuate wildly depending on grant cycles, volunteer turnover, or shifts in local economic conditions. When a recession hits, both the households they serve and the nonprofits themselves may find themselves in a downward spiral, with reduced giving capacity and increased demand for services.Details That Change the Picture
One often-overlooked detail is the role of informal asset transfers—such as gifts, loans, or shared resources—within Fred households. While these transactions don’t appear on balance sheets, they play a critical role in smoothing financial shocks. A neighbor helping with a car repair or a family member covering a utility bill can prevent a household from spiraling into debt, indirectly supporting its net worth. Nonprofits that recognize this dynamic often design programs to formalize these exchanges, such as community land trusts or mutual aid networks, which can have measurable effects on household stability. Another critical factor is the geographic concentration of Fred households and nonprofits. In urban areas with high costs of living, nonprofits may struggle to maintain net worth levels sufficient to meet demand, even as they attract more donors. In rural regions, where poverty rates can be just as high but philanthropic infrastructure is weaker, nonprofits may operate with minimal assets, relying on volunteer labor and in-kind donations. The net worth level of these organizations isn’t just a reflection of their financial health; it’s a proxy for the resilience of the communities they inhabit."The net worth of a nonprofit isn’t just about its balance sheet—it’s about its ability to adapt. In a world where Fred households are increasingly squeezed, the organizations that survive will be those that can turn limited resources into scalable impact." — Jane Chen, Executive Director, Community Wealth Fund
| Metric | Fred Households | Nonprofits Serving Them |
|---|---|---|
| Median Net Worth | $5,000–$10,000 | $50,000–$500,000 (varies by size) |
| Primary Wealth Holders | Tangible assets (car, home equity if owned) | Unrestricted funds, endowments, fixed assets |
| Biggest Financial Risk | Medical debt, predatory lending | Grant dependency, donor volatility |
Conclusion
The relationship between Fred households and nonprofit organizations is one of mutual dependency, where the net worth level of each group shapes the trajectory of the other. For households, nonprofits provide critical lifelines—whether through financial counseling, emergency aid, or advocacy—but their long-term impact is constrained by systemic barriers to wealth accumulation. For nonprofits, the communities they serve are both their raison d’être and their greatest financial vulnerability. When Fred households struggle, nonprofits often bear the brunt of the strain, yet their own stability is essential to breaking the cycle of poverty. The data makes one thing clear: no single solution exists. Policy changes—such as expanding access to child tax credits or increasing nonprofit capacity grants—can help, but they must be paired with cultural shifts in how we view wealth and giving. Nonprofits that succeed in raising the net worth of Fred households do so not by treating them as passive recipients, but by treating them as partners in asset-building. The challenge ahead lies in aligning financial systems—both public and private—to recognize that the health of one depends on the health of the other.Comprehensive FAQs
Q: How does the net worth of Fred households compare to the national average?
Fred households typically have net worth levels that are 20–30% below the national median. While the average U.S. household net worth is estimated at around $130,000, Fred households often fall between $5,000 and $20,000, with significant racial and regional variations. This gap is driven by factors like homeownership rates, retirement savings, and exposure to high-interest debt.
Q: Can nonprofits directly increase the net worth of Fred households?
Nonprofits can indirectly boost net worth through programs like financial literacy training, matched savings accounts, or homebuyer education—but direct impact is limited by their own financial constraints. For example, a nonprofit might help a household secure a low-interest loan, but the long-term net worth gain depends on the household’s ability to maintain payments and build equity. Larger-scale interventions, such as policy advocacy for asset-building initiatives, can have broader effects.
Q: What’s the biggest financial threat to nonprofits serving Fred households?
The most significant risk is revenue volatility, particularly reliance on grants and donations that can dry up during economic downturns. Smaller nonprofits are especially vulnerable, as they lack diversified funding streams. Additionally, inflation and rising operational costs (e.g., healthcare for staff, facility maintenance) erode their ability to reinvest in programs that directly benefit Fred households.
Q: Are there nonprofits with high net worth that focus on Fred households?
Yes, but they are often large, well-established organizations with diversified revenue models. Examples include United Way chapters, which may have net assets in the tens of millions, or housing nonprofits with endowments from corporate sponsors. However, even these organizations face pressure to balance mission-driven spending with financial sustainability, especially in high-cost regions.
Q: How does government policy affect the net worth of Fred households and nonprofits?
Policy plays a dual role. Programs like the Earned Income Tax Credit (EITC) or asset-building initiatives (e.g., Individual Development Accounts) can directly increase household net worth by providing liquidity or reducing debt. For nonprofits, policies such as the Low Income Housing Tax Credit (LIHTC) or nonprofit capacity grants can strengthen their financial footing, allowing them to scale programs. However, inconsistent funding or regulatory hurdles can undermine these efforts, particularly for smaller organizations.
