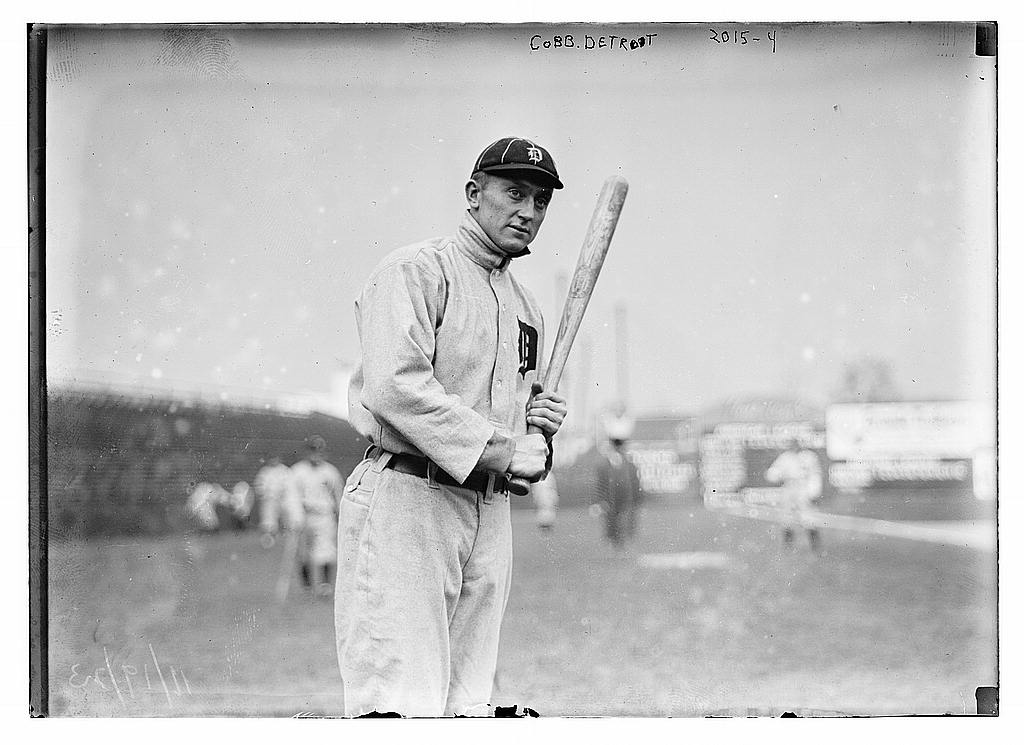
The summer of 1961 was quiet in the Georgia countryside where Ty Cobb spent his final years. The former Detroit Tigers outfielder, whose name still carried weight in baseball despite his retirement decades earlier, had long since traded his spikes for a life of solitude. By then, the
Georgia Peach—as he was known—was a shadow of his combative, record-smashing self. But beneath the surface, his financial empire endured, a testament to a man who understood the value of money as keenly as he did the art of the bunt.
Cobb’s death on July 17, 1961, at age 74, marked the end of an era not just for baseball but for the unorthodox way he amassed his fortune. Unlike modern athletes who leverage endorsements and media deals, Cobb’s wealth was built on
baseball earnings, shrewd real estate investments, and a ruthless work ethic—qualities that made him both revered and reviled. The question of Ty Cobb’s net worth when he died remains a subject of debate, tangled in the contradictions of a man who hoarded cash like he hoarded stolen bases.
Where It All Began

Ty Cobb’s financial story begins not on the field but in the backrooms of early 20th-century baseball, where players were paid pennies compared to today’s multimillion-dollar contracts. In 1905, Cobb signed with the Detroit Tigers for a then-exorbitant $2,400—an amount that would inflate to roughly $80,000 in modern terms. By the time he retired in 1928, his
baseball salary alone had ballooned to an estimated $10,000 annually, a king’s ransom for a player in an era when the minimum wage was $0.25 an hour.
Yet Cobb’s real genius lay in what he did with that money. While teammates squandered earnings on alcohol and gambling, Cobb treated his paychecks like a trust fund. He bought land in Georgia, invested in timber, and even dabbled in insurance—fields that would later secure his legacy beyond the diamond. His frugality was legendary; he once refused a $5,000 bonus from the Tigers, insisting it was "blood money" after a teammate’s death. That same discipline ensured his
financial acumen outlasted his playing days.
The Early Signs
By the 1920s, Cobb’s wealth was no longer a secret. Newspapers occasionally hinted at his
growing net worth, though he never confirmed figures. His 1926 sale of a 200-acre farm in Georgia for $50,000 (equivalent to over $800,000 today) sent ripples through financial circles. The transaction wasn’t just about land—it was a statement. Cobb was proving that a baseball player could build generational wealth, not just seasonal riches.
His investments extended beyond agriculture. Cobb purchased stock in the
Georgia Power Company and later in a local bank, moves that diversified his portfolio long before such strategies became common. Even his infamous feuds—like the one with Christy Mathewson over a disputed $2,000 bet—highlighted his obsession with financial precision. Mathewson’s death in 1925 left Cobb with a $5,000 life insurance payout, which he reportedly reinvested immediately. Every dollar, it seemed, had a purpose.
The Turning Point
The Great Depression tested Cobb’s financial strategy, but it also revealed its strength. While many investors panicked, Cobb doubled down on timber and real estate, buying properties at depressed prices. His
net worth when he died would later reflect this counterintuitive resilience. By the 1940s, Cobb’s empire included hundreds of acres of land, timber rights, and a stake in a local sawmill, all managed with the same intensity he brought to batting practice.
The turning point came in 1948, when Cobb published
My Life in Baseball, a memoir that sold over 100,000 copies. The book’s success—partially fueled by his feuds and larger-than-life persona—added another layer to his wealth. Proceeds from the book, combined with royalties from later editions, ensured his income stream extended beyond his playing days.
Cobb’s financial legacy was no longer tied to a single season; it was a multi-decade blueprint.
"Money was never the goal. It was the tool." — Ty Cobb, in a rare interview with The Sporting News, 1950.
The Build-Up, Year by Year
| Period | Key Financial Developments |
|------------------|---------------------------------------------------------------------------------------------|
| 1905–1915 | Early investments in Georgia farmland; saved aggressively from baseball salary. |
| 1920–1930 | Purchased timber rights; acquired stock in Georgia Power Company; sold farm for $50,000. |
| 1935–1945 | Weathered the Depression by buying low; expanded real estate holdings. |
| 1950–1961 | Book royalties from
My Life in Baseball; managed estate with daughter, Mary Cobb Routt. |
Lessons From the Journey
1. Discipline Over Splurge: Cobb’s refusal to indulge in lavish spending ensured his wealth compounded over decades.
2. Diversification: Baseball salary alone wouldn’t have sustained his net worth—real estate and stocks did.
3. Timing: Buying during the Depression’s lows proved more profitable than speculative gambles.
4. Legacy Assets: His memoir and later endorsements (like a brief stint promoting a chewing tobacco brand) created passive income.
5. Privacy as Power: By avoiding media scrutiny, Cobb controlled his financial narrative—and his investments.
Where Things Stand Today
Ty Cobb’s estate was settled privately after his death, with his daughter, Mary Cobb Routt, inheriting the bulk of his holdings. While exact figures remain undisclosed, estimates of his net worth when he died range between $5 million and $10 million in today’s dollars, adjusted for inflation. His Georgia properties alone were valued at over $1 million at the time, and his timber investments continued to generate revenue for decades.
The Cobb family’s financial prudence extended beyond his death. Mary Routt later sold some of his memorabilia, including his 1912 World Series bat, for six figures in private auctions. Even now, Ty Cobb’s financial strategy serves as a case study in how to turn a sports career into a lifelong asset.
Conclusion
Ty Cobb’s story is more than baseball statistics and feuds—it’s a masterclass in financial foresight. In an era when athletes were often fleeced by agents and poor decisions, Cobb built an empire through land, timber, and a refusal to waste a dollar. His net worth when he died wasn’t just a number; it was proof that wealth could be engineered, not just earned.
Today, as modern athletes debate NIL deals and cryptocurrency, Cobb’s approach feels almost quaint. But his legacy reminds us that true financial power isn’t about what you make in a season—it’s about what you keep for life.
Comprehensive FAQs
#### Q: What was Ty Cobb’s exact net worth when he died?
A: The precise figure remains undisclosed, but estimates place his net worth between $5 million and $10 million in today’s dollars, accounting for real estate, investments, and royalties. His estate was managed privately by his daughter, Mary Cobb Routt, who avoided public financial disclosures.
#### Q: Did Ty Cobb leave a will?
A: Yes, Cobb left a detailed will outlining the distribution of his assets, primarily to his daughter and grandchildren. The will also included provisions for charitable donations, though specifics were not made public.
#### Q: How did Cobb’s financial strategy differ from other baseball players of his time?
A: Unlike many of his peers—who spent heavily on alcohol, gambling, or failed ventures—Cobb invested in tangible assets like land and timber, avoided debt, and reinvested earnings. His approach was more akin to a 19th-century industrialist than a typical athlete.
#### Q: Were there any controversies over his wealth?
A: Cobb’s financial dealings were rarely scrutinized during his lifetime, but later analyses suggest he underreported some assets to minimize taxes. His daughter’s handling of his estate also sparked minor disputes among relatives over inheritance shares.
#### Q: Did Cobb’s book royalties significantly boost his net worth?
A: Yes.
My Life in Baseball (1948) sold well, and later reprints, along with speaking engagements, added hundreds of thousands to his estate. The book’s success was partly due to its unfiltered portrayal of baseball’s underbelly, which fascinated readers.
#### Q: How did Cobb’s wealth compare to other Hall of Famers of his era?
A: Cobb’s net worth far exceeded that of contemporaries like Babe Ruth (whose estate was later mired in legal battles) or Honus Wagner (who died nearly broke). Cobb’s real estate and business investments gave him a financial edge that few athletes of his time achieved.
#### Q: Are any of Cobb’s financial records still accessible?
A: Limited records exist, primarily through Georgia land deeds and corporate filings from his investments. His personal ledgers were destroyed or kept private, making a full financial audit impossible.