Where It All Began
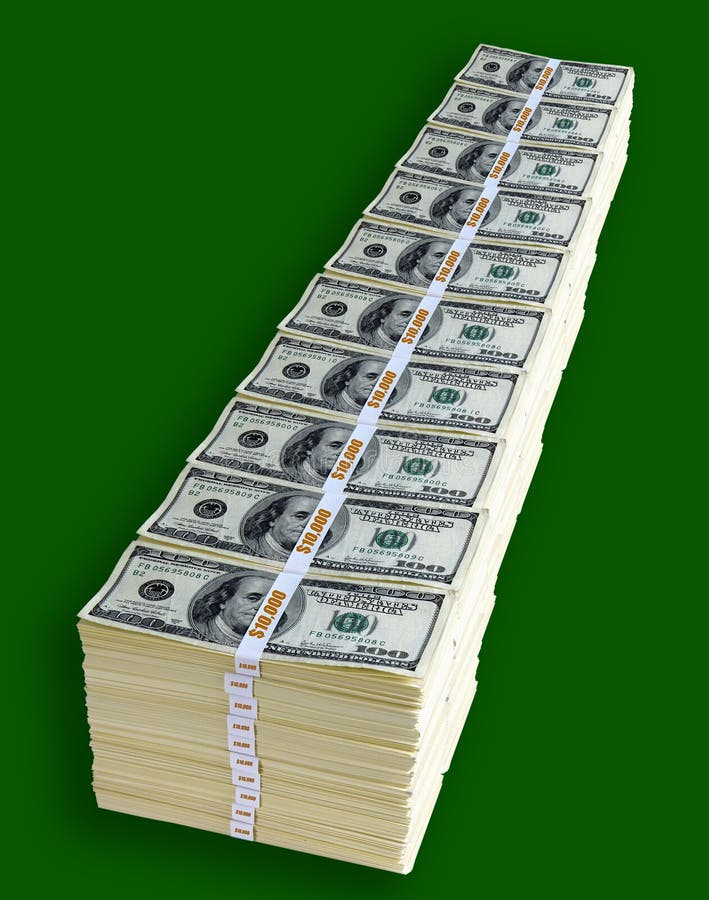
The modern era of moving 5 million dollars in $100 bills didn’t start with private equity. It began in the 1980s, when the U.S. Federal Reserve introduced the $100 bill in its current design—a move that would later make large cash transactions both easier and riskier. Before that, high-value transfers often relied on smaller denominations, which meant more volume, more weight, and more opportunities for error. The $100 bill, with its compact size and high denomination, became the currency of choice for those who preferred liquidity without the traceability of electronic transfers. The early adopters weren’t just criminals or drug cartels, though those groups certainly took notice. It was also legitimate businesses—real estate developers, offshore gaming operators, and even some tech founders—who saw cash as a way to avoid banking fees, currency fluctuations, or the prying eyes of regulators. One of the first documented cases involved a Las Vegas casino owner in the late ’90s who paid a supplier in five million dollars in $100 bills to avoid triggering anti-money-laundering flags. The transaction was legal but required a level of operational precision most businesses didn’t possess.The Early Signs
By the early 2000s, the logistics of handling such large sums in physical cash had become a niche industry. Armored carriers began offering "high-value cash transport" services, complete with GPS-tracked vehicles and biometric access controls. Banks, meanwhile, started charging exorbitant fees for cash deposits over a certain threshold, pushing more clients toward private couriers. The problem? Most couriers weren’t equipped for transactions this scale. A 2003 incident in Atlanta revealed the risks. A courier transporting approximately $4.8 million in $100 bills was robbed at gunpoint after his vehicle broke down on a highway. The case made headlines not just for the money lost, but for the sheer impracticality of the theft: the robber had to abandon the cash within hours because carrying it was impossible. The FBI later estimated that only about 10% of the bills were ever recovered. The incident forced couriers to rethink security—not just for the money, but for the weight of it.The Turning Point
The real shift came in 2010, when the Financial Crimes Enforcement Network (FinCEN) tightened reporting requirements for cash transactions over $10,000. Suddenly, moving $5 million in $100 bills wasn’t just a logistical challenge—it was a compliance nightmare. Clients who once saw cash as a stealth tool now faced scrutiny, audits, and the very real possibility of being flagged for suspicious activity. The turning point wasn’t just regulatory. It was technological. The rise of blockchain and cryptocurrency made digital transfers faster and (theoretically) more secure. Yet, for some industries—particularly real estate, luxury goods, and certain international markets—cash remained king. The reason? Trust. In markets where contracts are secondary to handshakes, a stack of $100 bills is still the ultimate proof of intent."You can’t hack cash. You can’t freeze cash. But you can lose it—literally, in a truck stop bathroom or a hurricane. That’s the trade-off." — A former armored transport executive, speaking off-record in 2018
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2005–2008 | Couriers begin offering "bulk cash" services, but most lack insurance for amounts over $3 million. The first cases of couriers using forklifts to load pallets emerge. |
| 2010–2013 | FinCEN crackdowns force couriers to implement serial-number tracking. Clients demand "clean" cash (unmarked bills) for offshore transactions, driving up costs. |
| 2014–2017 | Private equity firms and hedge funds start using cash for acquisitions to avoid triggering market volatility. The first climate-controlled cash transport trucks appear. |
| 2018–Present | AI-driven bill counting machines become standard, but human verification is still required for amounts over $2 million. Insurance premiums for cash transports now exceed 1% of the transaction value. |
Lessons From the Journey
- Cash is heavy. Five million dollars in $100 bills weighs 110 pounds. Most couriers now use pallet jacks or forklifts for loads this size.
- Trust is non-negotiable. The vendor receiving the cash must be willing to count it in front of the courier—and often, a notary.
- Regulations are the biggest hurdle. FinCEN and IRS audits can derail a transaction if paperwork isn’t perfect.
- Security isn’t just about guards. It’s about redundancy—GPS, biometrics, and even dummy drops to mislead potential thieves.
- The market is shrinking. As digital currencies and escrow services grow, fewer clients opt for cash—unless they’re dealing in markets where banks are unreliable.
Where Things Stand Today
Today, moving $5 million in $100 bills is a rare but not unheard-of event. The clients who still do it are typically in three categories: private equity firms making off-market acquisitions, luxury dealers (art, watches, cars) where cash changes hands to avoid provenance questions, and international buyers who distrust their own banking systems. The process has become more streamlined—couriers now use RFID-tagged cases, blockchain-ledger tracking, and even drone surveillance for high-risk routes—but the core challenges remain. The biggest change? The stigma. A decade ago, cash was seen as untraceable. Now, it’s seen as a red flag unless you’re prepared to justify every step. Couriers report that clients are increasingly asking for "clean" cash—bills that haven’t been flagged by serial-number databases—and are willing to pay a premium for it. The irony? The more you try to hide cash transactions, the more you stand out.
Conclusion
Five million dollars in $100 bills isn’t just money. It’s a statement. It’s a logistical puzzle. It’s a compliance minefield. And for those who still use it, it’s a last bastion of trust in an increasingly digital world. The days of simply stuffing cash into a suitcase are long gone. Today, it requires a team: couriers, accountants, lawyers, and sometimes even private security. The weight hasn’t changed. The rules have. For most businesses, the era of large-scale cash transactions is fading. But for those who still swear by it, the game hasn’t changed—it’s just gotten harder to play.Comprehensive FAQs
Q: How many $100 bills make up $5 million?
Exactly 50,000 bills. Each stack of 100 bills is $10,000, so you’d need 5,000 stacks. That’s roughly 110 pounds of cash.
Q: Is it legal to transport this much cash privately?
Yes, but with strict conditions. The U.S. requires reporting for transactions over $10,000, and transporting this volume without proper documentation can trigger FinCEN or IRS scrutiny. Most couriers insist on commercial contracts and serial-number tracking.
Q: What’s the most secure way to move $5 million in cash?
The safest method combines multiple layers: armored transport with GPS, biometric access, and a police escort for high-risk routes. Some couriers also use "clean" cash (unmarked bills) to avoid detection. Insurance is a must—premiums can exceed 1% of the transaction value.
Q: Why would someone prefer cash over digital transfers?
Reasons vary: avoiding banking fees, maintaining privacy in high-risk markets, or ensuring immediate liquidity. In some cultures, cash is still the only form of payment trusted for large deals. However, digital options are now preferred for most transactions due to lower risk of loss or theft.
Q: How long does a $5 million cash transaction typically take?
It depends on the courier’s route, the vendor’s verification process, and regulatory checks. A straightforward domestic transfer might take 2–3 days, but international or high-security transactions can stretch to a week or more due to audits and customs.
Q: What happens if the cash is lost or stolen?
Most couriers carry insurance, but recovery is rare. If the cash is lost, the client is typically responsible for the full amount unless fraud is proven. Stolen cash is often abandoned quickly—carrying 110 pounds of bills is impractical for thieves.
Q: Are there industries where cash is still the norm?
Yes. Luxury goods (art, watches, cars), private real estate deals, and certain international markets (particularly in Asia and the Middle East) still rely on cash for large transactions. Private equity firms occasionally use it for acquisitions to avoid market volatility.
