Walmart’s MoneyCard program was designed as a financial lifeline for millions of unbanked Americans—until it became a flashpoint in the
walmart moneycard dispute. Launched in 2005 as a partnership with Green Dot Corporation, the card promised convenience without credit checks, but its fee structure and operational quirks soon drew scrutiny. By 2018, lawsuits alleging deceptive practices had piled up, forcing Walmart to rethink its approach. The dispute wasn’t just about lost dollars; it revealed deeper issues in how prepaid cards operate at the intersection of retail and finance.
The controversy peaked when regulators and consumer groups accused Walmart of misleading customers about fees, account access, and dispute resolution processes. A
walmart moneycard dispute class-action lawsuit in California, settled in 2021, highlighted how the program’s terms—buried in fine print—left users vulnerable to unauthorized transactions and limited recourse. Meanwhile, Walmart’s internal policies clashed with federal rules, creating a patchwork of protections that favored the retailer over cardholders. The fallout extended beyond courts: Walmart’s reputation as a consumer-friendly brand took a hit, while competitors like Target and Amazon adjusted their own prepaid offerings in response.
Breaking Down the Numbers
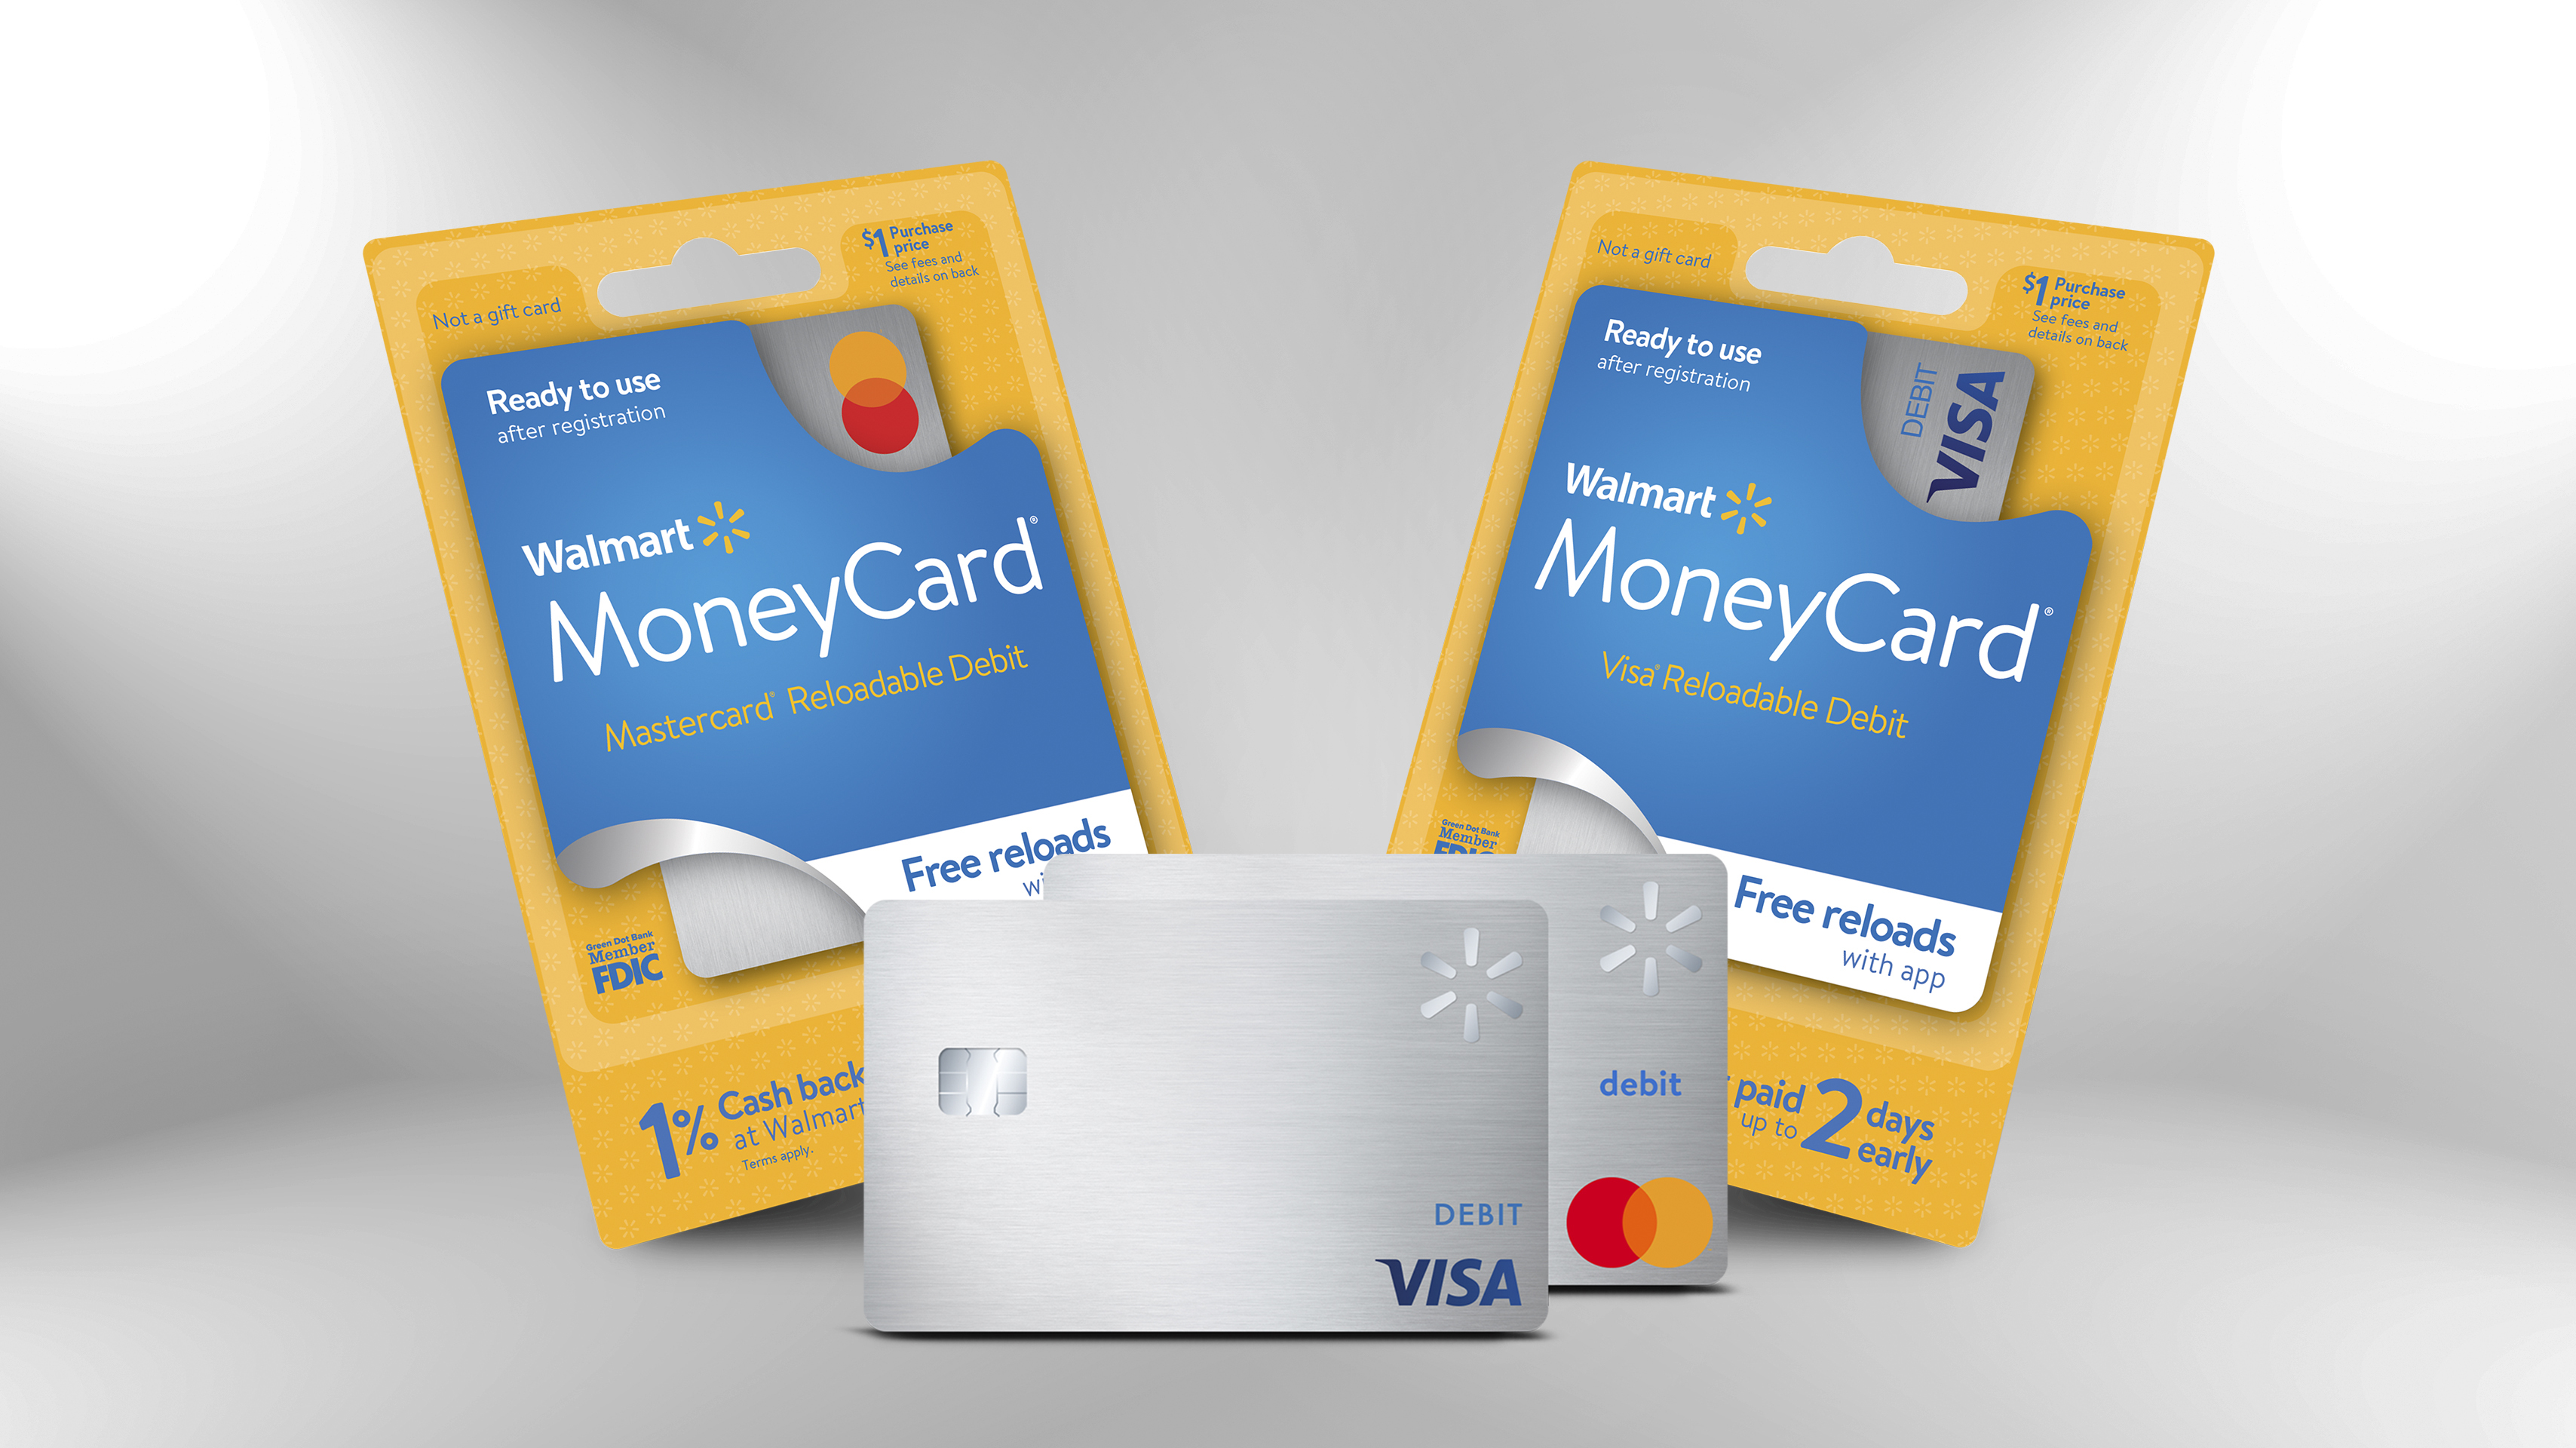
The financial stakes of the
walmart moneycard dispute were substantial, though exact figures remain fragmented. Walmart’s prepaid card program reportedly processed billions annually before the legal challenges surfaced, with fees generating hundreds of millions in revenue. Yet the costs of settlements, regulatory fines, and reputational damage could outweigh those gains. Industry estimates suggest that walmart moneycard disputes contributed to a broader decline in prepaid card trust, with issuers like Walmart and Green Dot facing combined losses in the tens of millions from lawsuits alone.
What’s less discussed is the human cost: millions of low-income users who relied on the MoneyCard for payroll deposits and bill payments. A 2020 Federal Reserve report found that 6% of U.S. households were unbanked, and prepaid cards like Walmart’s were a critical tool for this demographic. The dispute underscored how fee transparency—or the lack thereof—can disproportionately affect those least able to absorb financial setbacks.
####
The Verified Baseline
Public records confirm that Walmart’s MoneyCard program faced at least three major legal challenges. The first, a 2018 class-action lawsuit in California, accused the retailer of failing to disclose fees properly and allowing unauthorized transactions to go unresolved. A second case, filed in 2019, targeted Green Dot’s role in processing the cards, alleging conflicts of interest. Both cases were settled out of court, with terms sealed but reported to include restitution for affected users. Walmart also faced inquiries from the Consumer Financial Protection Bureau (CFPB) over its dispute resolution process, though no formal penalties were disclosed.
Walmart’s response centered on compliance reforms: the retailer restructured fee disclosures and introduced a 24-hour dispute resolution hotline. However, critics argued these changes were reactive, not proactive. The
walmart moneycard dispute became a case study in how retail giants navigate financial services without traditional banking oversight.
####
What the Estimates Suggest
Industry analysts estimate that
walmart moneycard disputes cost Walmart between $10 million and $30 million in settlements and legal fees, though exact figures are proprietary. The broader prepaid card market, valued at over $100 billion annually, saw a shift in consumer behavior post-dispute, with some users migrating to bank-issued debit cards or digital wallets. Green Dot, Walmart’s original partner, reportedly faced its own legal exposure, though its financial statements do not break out prepaid card liabilities separately.
Speculation also swirls around Walmart’s internal calculations: if the MoneyCard’s fee income was a key revenue driver, the dispute may have forced the retailer to re-evaluate its financial services strategy. Some observers suggest Walmart could pivot to partnerships with traditional banks to mitigate regulatory risks, though no such moves have been publicly announced.
Case Study: A Closer Look
Consider the case of Maria Rodriguez, a Texas retail worker whose MoneyCard was hit with a $300 unauthorized charge in 2019. Rodriguez, who relied on the card for her entire paycheck, called Walmart’s customer service for three days before being told the dispute would take “up to 10 business days” to resolve. By then, her rent was late, and the card’s $25 dispute fee—waived only after she escalated to a supervisor—left her deeper in debt. Her experience mirrors dozens of complaints logged in the CFPB’s database, where
walmart moneycard disputes frequently cited delays and lack of clarity.
Rodriguez’s story is emblematic of the systemic issues at play. A 2020 CFPB report found that prepaid card users were three times more likely to face unresolved disputes than traditional bank customers. Walmart’s internal policies, which required manual reviews for certain claims, created bottlenecks that disproportionately affected low-income users.
>
"They treated my money like it was disposable. But it wasn’t—it was my survival."
> —Maria Rodriguez, plaintiff in a walmart moneycard dispute settlement

|
Factor | Estimated Impact |
|--------------------------|-------------------------------------------------------------------------------------|
| Fee transparency | Lost trust; migration to competitors’ cards (estimated 5–10% of users) |
| Dispute resolution delays| Financial strain on low-income users; CFPB complaints spiked by 40% post-2018 |
| Partnership structure | Green Dot’s role questioned; potential liability exposure for both parties |
| Regulatory scrutiny | CFPB inquiries led to policy overhauls, though enforcement remained limited |
| Reputational damage | Erosion of Walmart’s “everyday low prices” brand equity among unbanked consumers |
What This Means Going Forward
The walmart moneycard dispute has reshaped how retailers approach prepaid financial products. Walmart’s settlement and policy changes set a precedent for fee disclosure, but the underlying issue—balancing profitability with consumer protection—remains unresolved. Competitors like Target (with its own prepaid card) and grocery chains now face heightened scrutiny over similar programs, with regulators closely watching for repeat offenses.
For consumers, the dispute serves as a cautionary tale about the risks of relying on non-bank financial tools. While prepaid cards offer accessibility, their lack of federal protections means users must advocate aggressively for their rights. The CFPB’s continued oversight suggests this won’t be the last walmart moneycard dispute-style controversy in the prepaid space.
Conclusion
The Walmart MoneyCard’s rise and fall highlight a critical tension in modern retail: the blurring line between commerce and banking. What began as a noble effort to serve the unbanked became a legal and ethical quagmire, exposing gaps in oversight and corporate accountability. The dispute’s legacy isn’t just about lost lawsuits or fee structures—it’s about who gets protected when the systems designed to help them fail.
As prepaid cards evolve, the lessons from walmart moneycard disputes will determine whether financial inclusion can coexist with fair business practices. For now, the case stands as a reminder that in the intersection of retail and finance, the fine print often writes the rules—and not always in the consumer’s favor.
Comprehensive FAQs
#### Q: Can I still use the Walmart MoneyCard after the dispute?
A: Yes, but with caveats. Walmart restructured the program post-settlement, improving fee disclosures and dispute processes. However, some users report ongoing issues with account access or chargebacks. If you’re affected, contact Walmart’s financial services team directly or file a complaint with the CFPB.
#### Q: Were there any refunds or compensation for affected users?
A: Settlements in walmart moneycard disputes typically included restitution for documented unauthorized charges or fee disputes. Exact amounts varied by case, but some users received partial refunds of fees or disputed transactions. Sealed court documents make precise figures difficult to obtain.
#### Q: How does Walmart’s MoneyCard compare to other prepaid cards?
A: Unlike bank-issued debit cards, Walmart’s MoneyCard lacks federal protections like Error Resolution under Regulation E. Competitors like NetSpend or Chime offer similar features but with different fee structures. The walmart moneycard dispute underscores why some consumers prefer traditional banks despite higher barriers to entry.
#### Q: What should I do if I encounter a walmart moneycard dispute?
A: Act immediately: document all transactions, contact Walmart’s dispute resolution team (now 24/7), and escalate to the CFPB if unresolved. Avoid paying dispute fees unless you’re certain the claim is frivolous. Many users found success by citing the 2021 settlement terms in their complaints.
#### Q: Will Walmart discontinue the MoneyCard program?
A: There’s no indication Walmart plans to exit prepaid financial services entirely. However, the retailer may shift toward bank partnerships to mitigate regulatory risks. The program’s future hinges on balancing profitability with compliance—a lesson learned the hard way through walmart moneycard disputes.

