
Where It All Began
The origins of the term trace back to the post-WWII era, when the U.S. tax code first recognized "wealthy individuals" as a distinct category. Before then, wealth was measured in land, livestock, or family businesses—assets that didn’t translate neatly into liquid numbers. The 1940s saw the rise of modern asset management, as families like the Rockefellers and DuPonts hired the first dedicated wealth advisors. These early managers needed a way to segment clients, and $1 million became the arbitrary but useful benchmark. It was enough to live comfortably but not so large that it attracted regulatory scrutiny. The definition of high net worth individual in the United States, in its infancy, was less about precision and more about signaling: this was the tier where clients could expect personalized service, not just a broker’s generic advice. The real inflection point came in the 1980s, when deregulation and the rise of private banking created a new class of ultra-wealthy clients. Banks like Chase and Goldman Sachs began offering services tailored to those with $5 million or more, while hedge funds set minimum investments at $100,000—an amount that excluded all but the wealthiest. The term high net worth became a euphemism for "someone we can charge premium fees to." By the late 1990s, the dot-com boom and subsequent crash proved that wealth wasn’t static. A $1 million net worth in 1999 might vanish overnight, while a $5 million portfolio could weather the storm. The definition had to evolve—or risk becoming meaningless.The Early Signs
The first red flags appeared in the late 1990s, when financial firms realized their wealth-management models were broken. Clients who had qualified as "high net worth" in the 1980s were now struggling with market volatility, divorce settlements, or unexpected healthcare costs. Meanwhile, a new generation of tech millionaires—many under 40—were flooding into private banks with portfolios that dwarfed the old guard’s. The inconsistency in definitions led to confusion: Was a $2 million net worth enough for premium service, or did it take $10 million? The answer varied by institution, but the underlying problem was clear: the definition of high net worth individual in the United States had outgrown its original purpose. It was no longer just about asset size; it was about risk tolerance, lifestyle expectations, and the ability to sustain wealth across generations. The turning point arrived in 2008, when the global financial crisis exposed the fragility of even the most carefully constructed portfolios. A $5 million net worth in 2007 might shrink to $3 million by 2009, yet the banks that had served these clients still demanded the same minimum balances. The crisis forced a reckoning: if wealth could disappear overnight, what did "high net worth" even mean? Some firms doubled down on static thresholds, while others introduced dynamic criteria—like liquidity ratios or exposure to alternative investments. The definition was no longer just financial; it had become a test of resilience.The Turning Point
The moment the definition of high net worth individual in the United States stopped being about money and started being about power was the 2017 tax overhaul. The law slashed capital gains taxes for the wealthy while leaving middle-class rates largely unchanged, widening the gap between those who could preserve wealth and those who couldn’t. At the same time, private equity firms began offering "carried interest" deals that let managers treat profits as long-term capital gains—effectively turning short-term gains into tax-advantaged assets. The result? A new class of ultra-wealthy individuals whose net worth fluctuated wildly but whose tax burden didn’t. The shift wasn’t just legal; it was cultural. Wealth managers began tracking not just asset size but wealth mobility—how easily a client could convert assets into cash or influence. A $10 million portfolio in real estate might not qualify for the same services as $10 million in liquid investments, even if the total was identical. The definition had fractured. Some firms used $5 million as the cutoff; others demanded $25 million for "platinum" tier access. The inconsistency reflected a deeper truth: in the U.S., wealth isn’t just about what you have, but what you can do with it."The old definition of high net worth was about dollars. The new one is about options—and who gets to decide which options are available." — James Henry, former chief economist at McKinsey & Co.

The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 1980s–1990s | Banks adopt $1M–$5M thresholds; private equity and hedge funds emerge as key wealth drivers. The definition of high net worth individual in the U.S. becomes tied to institutional access. |
| 2000–2007 | Dot-com crash and real estate bubble expose volatility. Firms introduce dynamic criteria (liquidity, investment diversity) alongside static thresholds. |
| 2008–2012 | Post-crisis, banks raise minimums to $5M–$10M. The definition splits: "high net worth" for mass-market advisors vs. "ultra-high net worth" for private banks. |
| 2017–Present | Tax reforms and private equity growth blur lines. Some firms now use $30M+ as the baseline, while others focus on "wealth potential" over static balances. |
Lessons From the Journey
- Wealth thresholds are arbitrary—but the services they unlock aren’t. A $5 million net worth may get you a wealth manager; $50 million gets you a seat on a private jet.
- Geography matters more than ever. A $10 million portfolio in Silicon Valley carries different weight than the same in rural Ohio.
- Inheritance is the great equalizer—or divider. Families that pass wealth across generations often face fewer liquidity constraints than self-made millionaires.
- Tax policy rewrites the rules. The 2017 tax cuts didn’t just reduce rates; they created new wealth-preservation tools for the ultra-rich.
- Private markets now define "high net worth." Access to venture capital, private credit, and unlisted assets often matters more than public portfolio size.
- The definition is becoming less about money and more about exclusion. The fewer people who qualify, the more valuable the "high net worth" label becomes.
Where Things Stand Today
As of 2024, the definition of high net worth individual in the United States is less a fixed number and more a spectrum. The Global Wealth Report estimates that roughly 2.5 million U.S. households qualify as high net worth (using a $1 million+ liquid assets threshold), but the services they receive vary wildly. A $2 million portfolio might get a mid-tier advisor; $20 million could mean a dedicated team with direct access to hedge fund managers. The real divide isn’t at $1 million—it’s at $10 million, where clients gain entry to a world of discretionary accounts, offshore structures, and tax strategies most Americans can’t replicate. What’s changed most isn’t the thresholds, but the assumptions behind them. Today, being "high net worth" often means having a diversified mix of assets—private equity, real estate, art, or even crypto—that traditional banks can’t easily value. It means understanding how to structure holdings to avoid estate taxes or capital gains triggers. And it means navigating a financial ecosystem where the rules are written for those who already know how to play. The definition has become less about how much you have and more about how you’re positioned to keep it.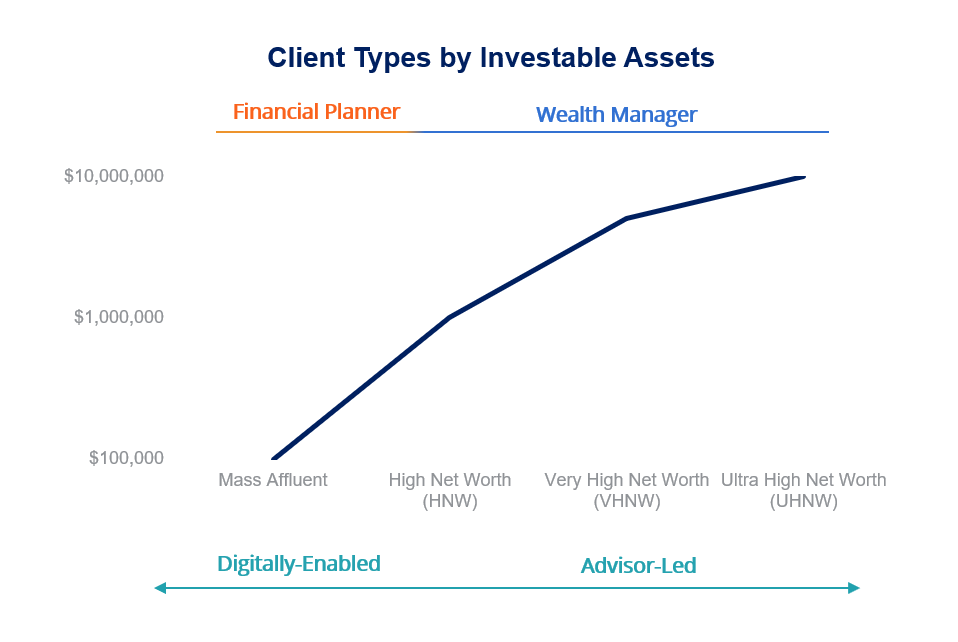
Conclusion
The evolution of the definition of high net worth individual in the United States tells a story larger than numbers. It’s about the quiet ways wealth begets more wealth, how access to the right networks can turn a volatile market into a lifelong advantage, and how tax policy and financial innovation constantly redraw the lines. The thresholds may shift—$1 million today might be $2 million tomorrow—but the underlying dynamic remains: wealth in America isn’t just a measure of income. It’s a measure of opportunity hoarded by those who already have it. For the average American, the definition matters less than the reality: that the system is designed to reward those who can navigate it, not those who simply have the means. The high-net-worth individual of 2024 isn’t just someone with a big bank balance. They’re someone who understands the unspoken rules—and knows how to bend them.Comprehensive FAQs
Q: What’s the most widely accepted definition of high net worth individual in the United States today?
A: There’s no single standard, but most financial institutions use $1 million in liquid assets as the baseline. Private banks often require $5 million or more for premium services, while ultra-high-net-worth designations typically start at $30 million. The key distinction is access: higher thresholds unlock exclusive wealth-management tools, tax strategies, and investment opportunities not available to lower-tier clients.
Q: Does geography affect whether someone qualifies as high net worth?
A: Absolutely. A $5 million net worth in Manhattan may not qualify for the same services as $5 million in Dallas, where the cost of living is lower. Coastal cities like San Francisco and New York have higher implicit thresholds due to real estate and tax burdens. Meanwhile, in states with no income tax (e.g., Texas, Florida), the same portfolio might carry more weight for wealth-preservation purposes.
Q: Can someone be high net worth without a large public portfolio?
A: Yes. Many high-net-worth individuals hold wealth in private equity, real estate, or unlisted businesses, which aren’t reflected in public filings. Banks and wealth managers often assess "investable assets" separately from illiquid holdings. For example, a family-owned business valued at $20 million might not count toward a traditional HNWI threshold unless it’s liquidated—yet the family could still access high-net-worth services based on their overall financial picture.
Q: How do tax policies influence who qualifies as high net worth?
A: Tax laws directly shape wealth accumulation. The 2017 Tax Cuts and Jobs Act, for instance, lowered capital gains rates for the wealthy, making it easier to preserve and grow portfolios. Meanwhile, estate tax exemptions (now $13.6 million per individual) allow families to pass wealth intergenerationally without triggering penalties. These policies effectively raise the bar for who can sustain high-net-worth status, as middle-class families face higher effective tax rates on income and investments.
Q: Are there non-financial factors that determine high-net-worth status?
A: Increasingly, yes. Wealth managers now evaluate wealth mobility, risk tolerance, and lifestyle alignment alongside asset size. For example, a client with $10 million in volatile assets (e.g., crypto, startups) might face stricter scrutiny than one with $10 million in bonds and blue-chip stocks. Additionally, social capital—connections to private networks, alumni associations, or exclusive clubs—can indirectly boost a client’s perceived "high-net-worth" standing, even if their portfolio is technically below a firm’s stated threshold.
Q: How has the rise of fintech and digital assets changed the definition?
A: Fintech has democratized some aspects of wealth management (e.g., robo-advisors, fractional investing), but it hasn’t erased the high-net-worth divide. Digital assets like Bitcoin and NFTs complicate valuations, as banks struggle to assess volatility and regulatory risks. Some private banks now treat crypto holdings as a separate asset class, which can either raise or lower a client’s perceived net worth depending on market conditions. Meanwhile, traditional HNWI services—like family offices and private banking—remain largely inaccessible to those without proven liquidity.
Q: What’s the future of the high-net-worth definition in the U.S.?
A: The trend is toward dynamic, not static, thresholds. Firms are increasingly focusing on wealth potential (e.g., unrealized gains, future inheritance) rather than current balances. Artificial intelligence and big data will also play a role, as banks use predictive modeling to identify clients who could become high net worth—even if they’re not there yet. Politically, debates over wealth taxes and capital gains reforms could further blur the lines, but the core dynamic will remain: the definition will continue to serve those who control the financial system, not those who simply have the wealth.
