
Breaking Down the Numbers
The hierarchy of luxury brands isn’t just qualitative—it’s quantifiable. Market capitalization, revenue growth, and even social media engagement serve as proxies for where brands stand in the luxury food chain. LVMH, the world’s largest luxury conglomerate, reported revenues of €88.4 billion in 2023, with brands like Louis Vuitton and Dior generating the bulk of its profits. These figures aren’t just numbers; they reflect the hierarchy of luxury brands in action, where a single logo can command premium pricing and global cachet. Yet numbers alone don’t tell the full story. A brand like Rolls-Royce, with far lower annual sales than Louis Vuitton, holds a different kind of prestige—one tied to bespoke craftsmanship and an almost mythic status. The hierarchy of luxury brands isn’t linear; it’s a constellation where heritage, craftsmanship, and cultural relevance intersect. Even within LVMH’s portfolio, there’s a clear tiering: a Christian Dior gown carries more weight than a Fendi bag, not just in price, but in the narratives surrounding them.The Verified Baseline
Publicly available data confirms the hierarchy of luxury brands is real and measurable. The 2023 BrandZ Luxury Report ranked Louis Vuitton as the world’s most valuable luxury brand, with an estimated value of $62 billion, followed by Hermès at $55 billion. These rankings aren’t arbitrary—they reflect decades of brand-building, from Louis Vuitton’s steamer-trunk heritage to Hermès’ legendary waitlists for its Birkin bags. The hierarchy of luxury brands is reinforced by third-party valuations, which consistently place Swiss watchmakers, French fashion houses, and Italian leather goods at the top. What’s less discussed is the hierarchy’s dark side: the brands that once dominated but have since slipped. Burberry, for instance, saw its valuation drop by nearly 30% in 2022 after a series of missteps, including controversial campaigns and over-reliance on China. The hierarchy of luxury brands isn’t just about ascent—it’s about survival. Brands that fail to adapt, whether through relevance or scandal, risk demotion in the pecking order.What the Estimates Suggest
Industry estimates paint a picture of fluidity within the hierarchy of luxury brands. While LVMH and Kering remain the dominant players, private equity firms are increasingly eyeing niche luxury assets, suggesting a shift in how prestige is monetized. A 2023 McKinsey report estimated that the global luxury market could reach $1.3 trillion by 2030, with the fastest growth in "ultra-luxury" segments—think bespoke tailoring, vintage wine, and limited-edition art. Yet estimates also highlight the risks of over-expansion. The rise of "democratized luxury" brands like Zara’s Dupe collection has blurred the lines, forcing traditional houses to defend their positioning. The hierarchy of luxury brands is no longer just about exclusivity; it’s about perceived authenticity. A brand like Rolex, which has maintained strict production quotas, remains untouchable, while others scramble to justify their premium pricing in an era of economic uncertainty.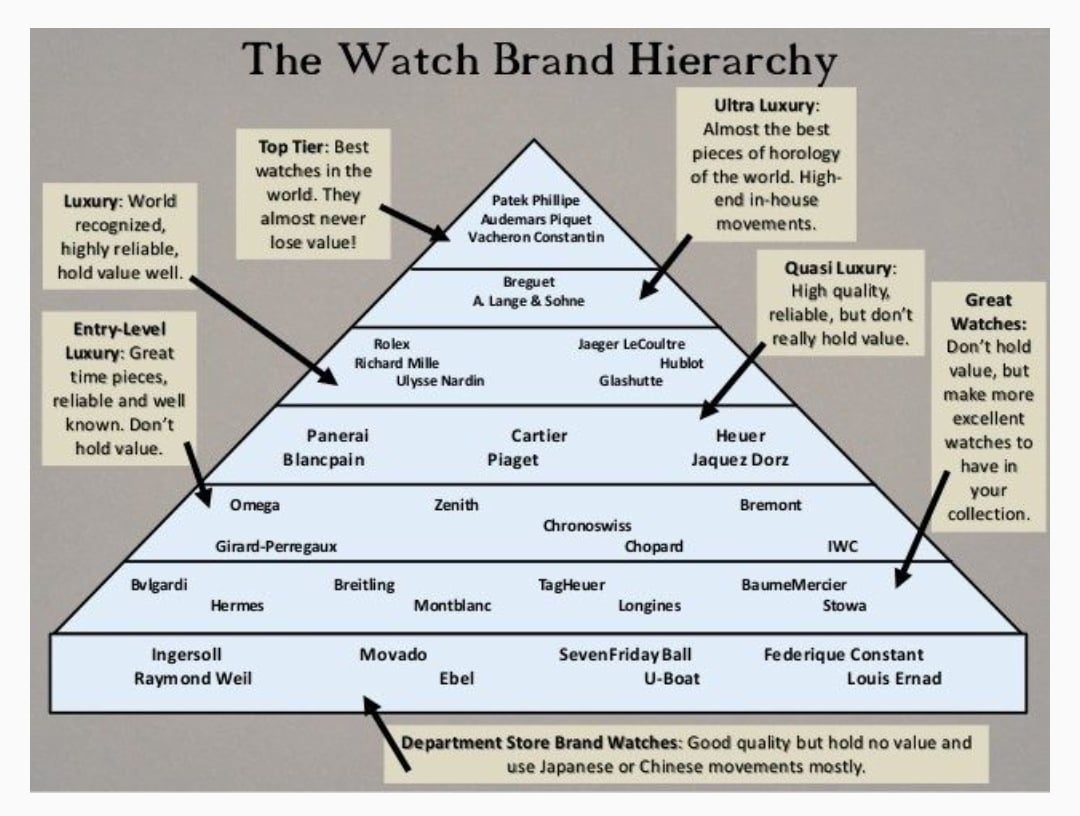
Case Study: A Closer Look
Few brands illustrate the hierarchy of luxury brands better than Patek Philippe. The Swiss watchmaker’s Nautilus model, introduced in 1976, has become a status symbol in its own right—one that now sells for figures around the £100,000 range on the secondary market. The brand’s refusal to chase volume over exclusivity has cemented its place at the top of the luxury watch hierarchy, where even celebrity endorsements (like LeBron James’ 2022 collaboration) are secondary to its legacy of horological mastery. Patek’s strategy isn’t just about product; it’s about controlled scarcity. The brand produces fewer than 40,000 watches annually, ensuring demand outstrips supply. This isn’t just a business model—it’s a psychological moat that keeps competitors at bay. While Rolex and Audemars Piguet also restrict production, Patek’s hierarchy within the watch world is unique because it appeals to both collectors and connoisseurs who value craftsmanship over brand recognition."A Patek Philippe isn’t just a watch—it’s a legacy piece. The moment you buy one, you’re not just owning a product; you’re joining a conversation that’s been happening for over 180 years." — Philippe Stern, Patek Philippe CEO (2023 interview)The impact of Patek’s positioning is clear when comparing it to mid-tier watchmakers like Tissot or Certina. While those brands offer quality at a fraction of the price, they lack the hierarchical weight that comes with Patek’s heritage. The table below breaks down the estimated impact of key factors in Patek’s dominance:
| Factor | Estimated Impact |
|---|---|
| Heritage & Legacy | Unmatched—founded in 1839, with royal patronage dating back to Napoleon III. |
| Production Limits | Annual output capped at ~40,000 units, ensuring scarcity. |
| Secondary Market Premium | Resale values often 20-50% above retail, driven by collector demand. |
| Craftsmanship Perception | Each watch is hand-finished; no two are identical, reinforcing exclusivity. |
What This Means Going Forward
The hierarchy of luxury brands is evolving under pressure from two forces: digital disruption and changing consumer priorities. Younger affluent buyers—particularly in Asia—are increasingly drawn to experiential luxury, where brand stories matter as much as the products themselves. This shift is forcing traditional houses to rethink their strategies. LVMH’s acquisition of Belmond (luxury hotels) in 2022 was a clear signal: the hierarchy of luxury brands is expanding beyond fashion and watches into immersive experiences. At the same time, authenticity is becoming the new currency. Brands that rely solely on logos risk being outpaced by those that invest in artisanal techniques, sustainability, and cultural relevance. The hierarchy of luxury brands is no longer just about what you own—it’s about what you stand for. Even heritage brands like Chanel are facing scrutiny over supply chain ethics, proving that prestige is no longer immune to modern expectations.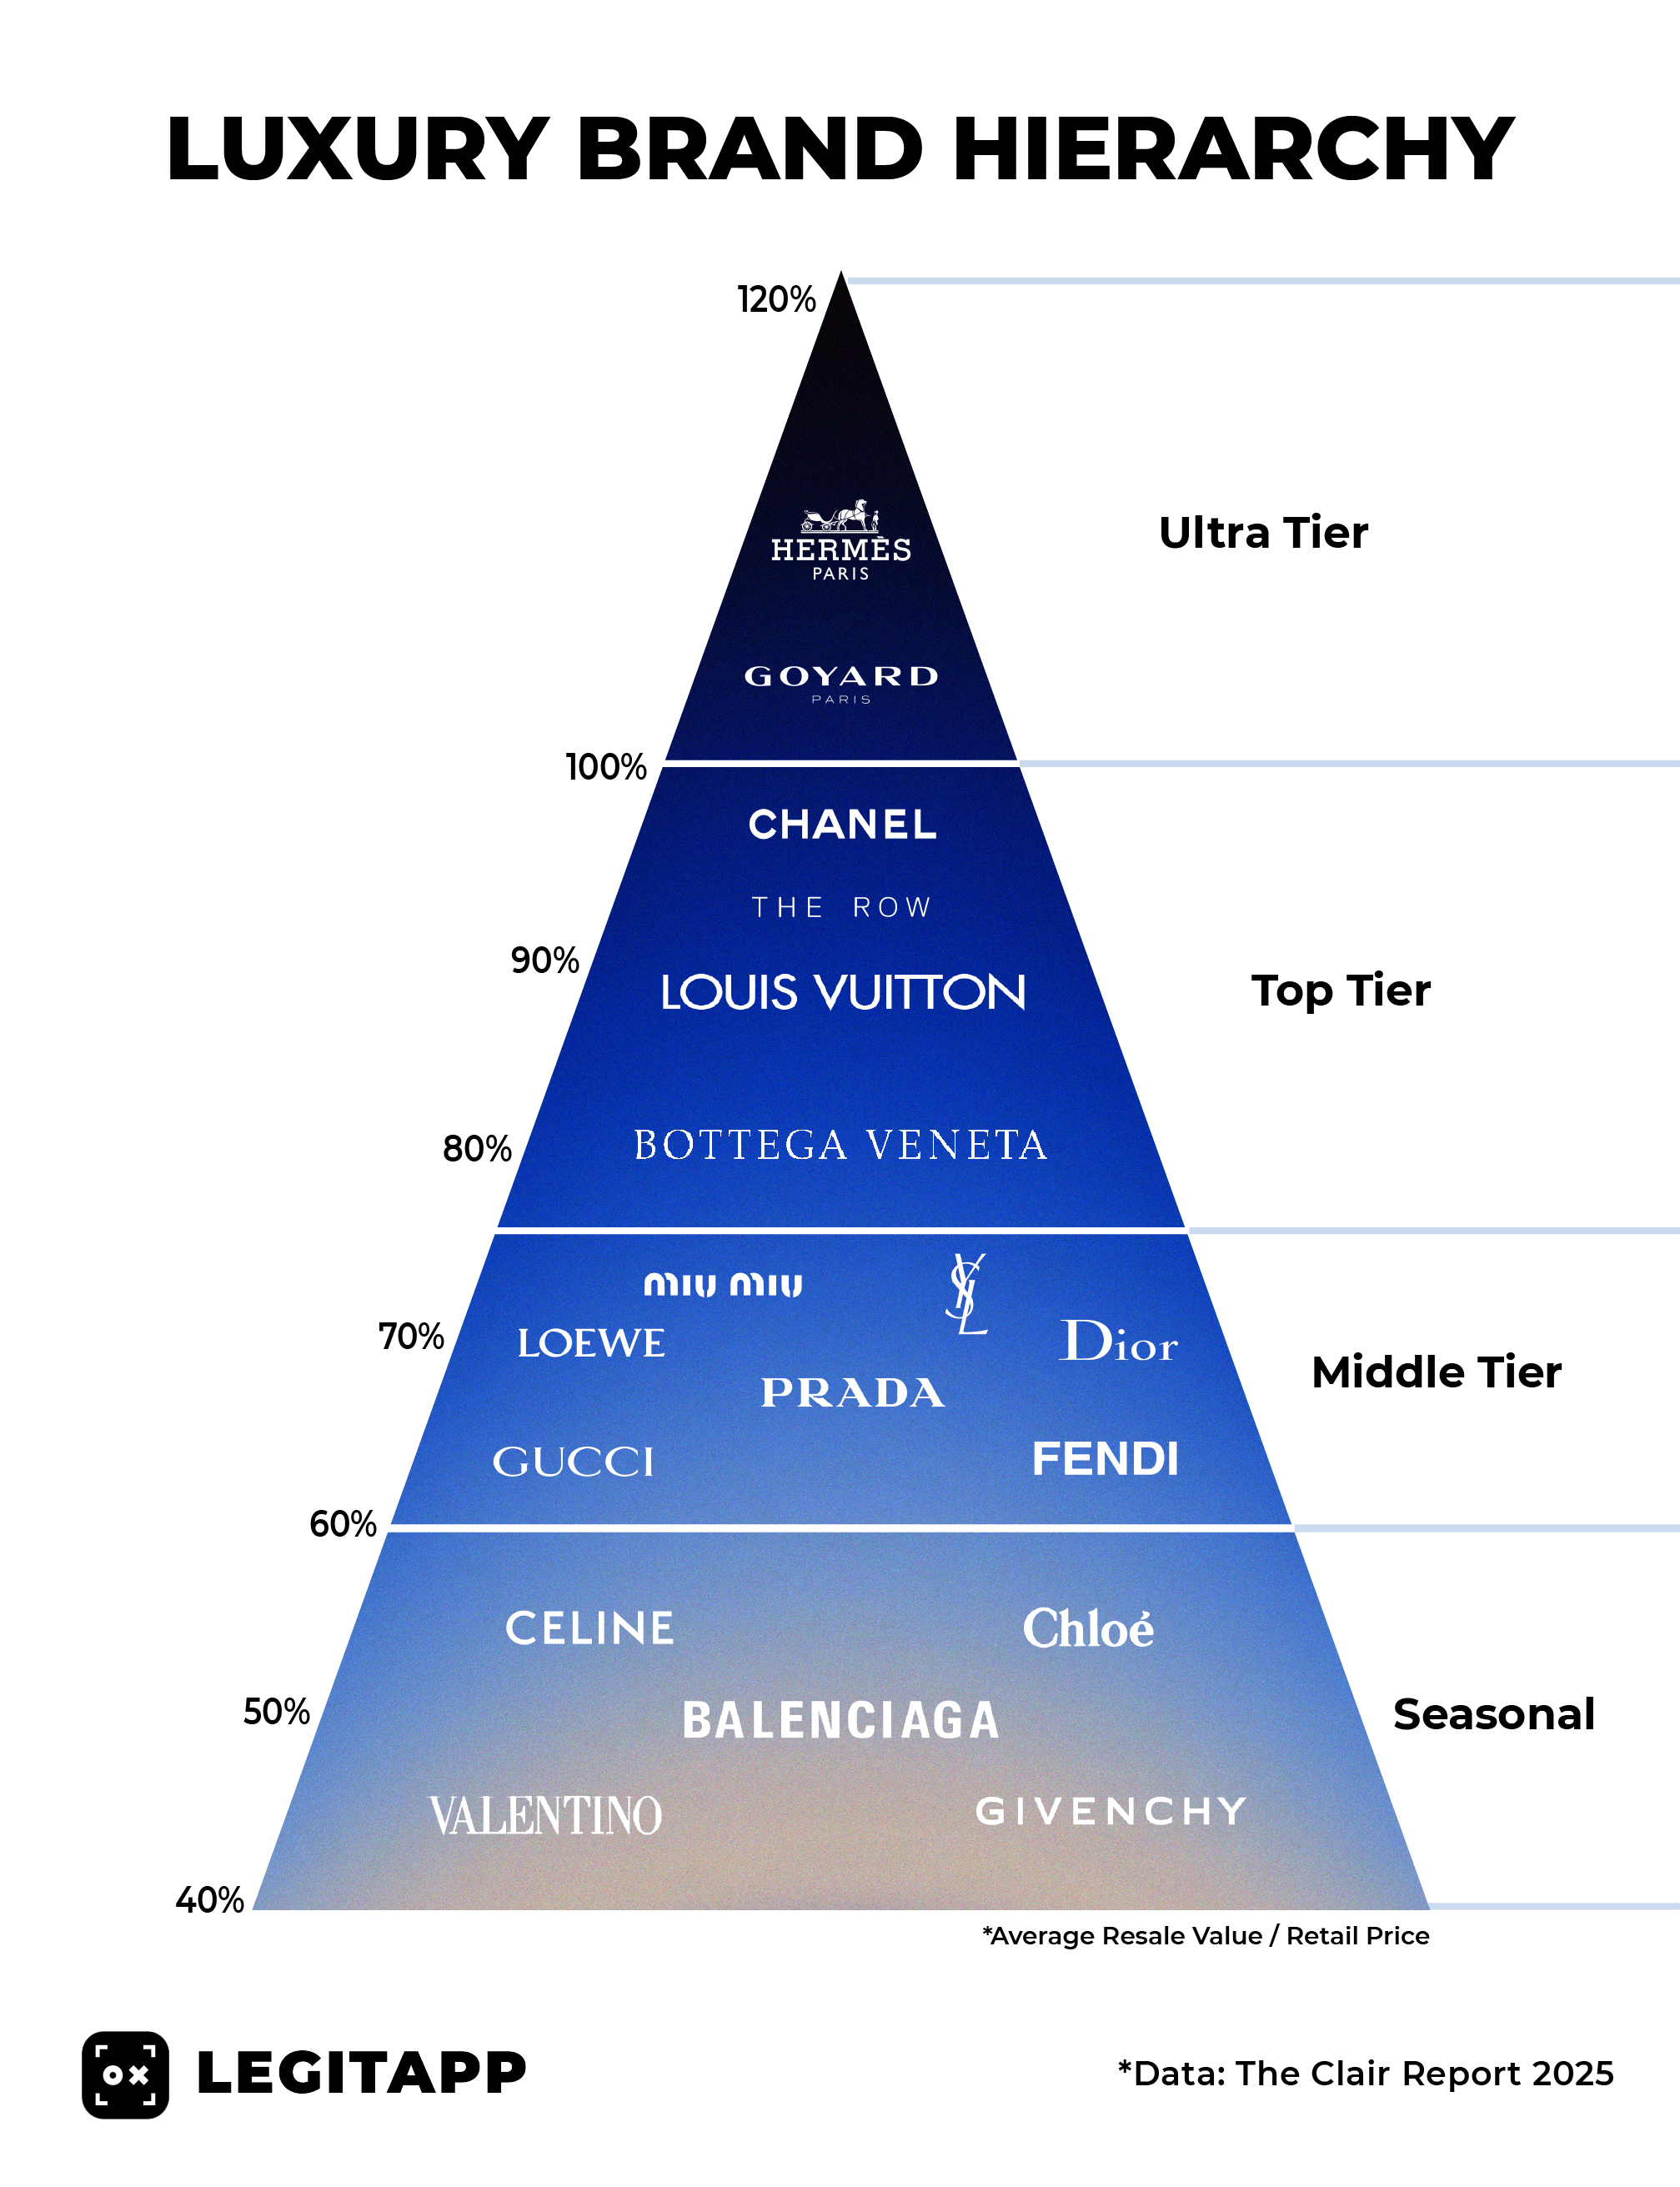
Conclusion
The hierarchy of luxury brands isn’t a fixed chart—it’s a dynamic ecosystem where power shifts with consumer behavior, economic trends, and bold acquisitions. What remains constant is the psychological power of prestige: the way a Hermès bag or a Rolex subtly signals status without a single word spoken. For brands, navigating this hierarchy means balancing exclusivity with accessibility, heritage with innovation. For consumers, understanding it means recognizing that luxury isn’t a single tier—it’s a spectrum. The brands at the top don’t just sell products; they sell membership in an elite narrative. And in a world where counterfeits and fast-fashion knockoffs proliferate, that narrative is more valuable than ever.Comprehensive FAQs
Q: How does the hierarchy of luxury brands affect resale values?
The hierarchy of luxury brands directly influences resale markets. Brands at the top—like Patek Philippe, Hermès, or Rolex—often see secondary market premiums because of controlled production and collector demand. A limited-edition Chanel bag, for instance, can resell for 20-30% above retail, while mid-tier brands may see little to no markup.
Q: Can a brand move up or down in the hierarchy?
Absolutely. Brands like Tiffany & Co. saw their hierarchical standing surge after LVMH’s acquisition, while others—such as Burberry—have slipped due to missteps. The hierarchy of luxury brands is fluid, dictated by market performance, cultural relevance, and strategic decisions like distribution cuts or celebrity collaborations.
Q: Are there regional differences in luxury brand hierarchies?
Yes. In China, luxury hierarchy often prioritizes brands with strong digital presence and limited-edition drops, while in Europe, heritage and craftsmanship remain non-negotiable. The hierarchy of luxury brands in the Middle East, for instance, leans toward ultra-exclusive experiences like private yacht charters or bespoke jewelry, reflecting local wealth dynamics.
Q: How do counterfeiters exploit the hierarchy of luxury brands?
Counterfeiters target brands just below the top tier—like fake Rolex or Louis Vuitton replicas—because they offer the illusion of prestige at a fraction of the cost. The hierarchy of luxury brands creates a "goldilocks zone" where mid-tier fakes are profitable, while ultra-luxury items (like Patek Philippe) are harder to replicate convincingly.
Q: Does sustainability affect a brand’s position in the hierarchy?
Increasingly, yes. Brands like Stella McCartney and Patagonia (though not traditionally luxury) are redefining prestige by tying it to ethical production. Even established houses like LVMH have pledged to carbon neutrality by 2050—a move that could elevate their hierarchical standing among younger, values-driven consumers.
Q: What’s the biggest misconception about the hierarchy of luxury brands?
The biggest myth is that price alone determines prestige. A $10,000 watch from a niche Swiss brand may hold more hierarchical weight than a $50,000 entry-level Rolex if it’s backed by craftsmanship and scarcity. The hierarchy of luxury brands is about perceived value, not just price tags.
