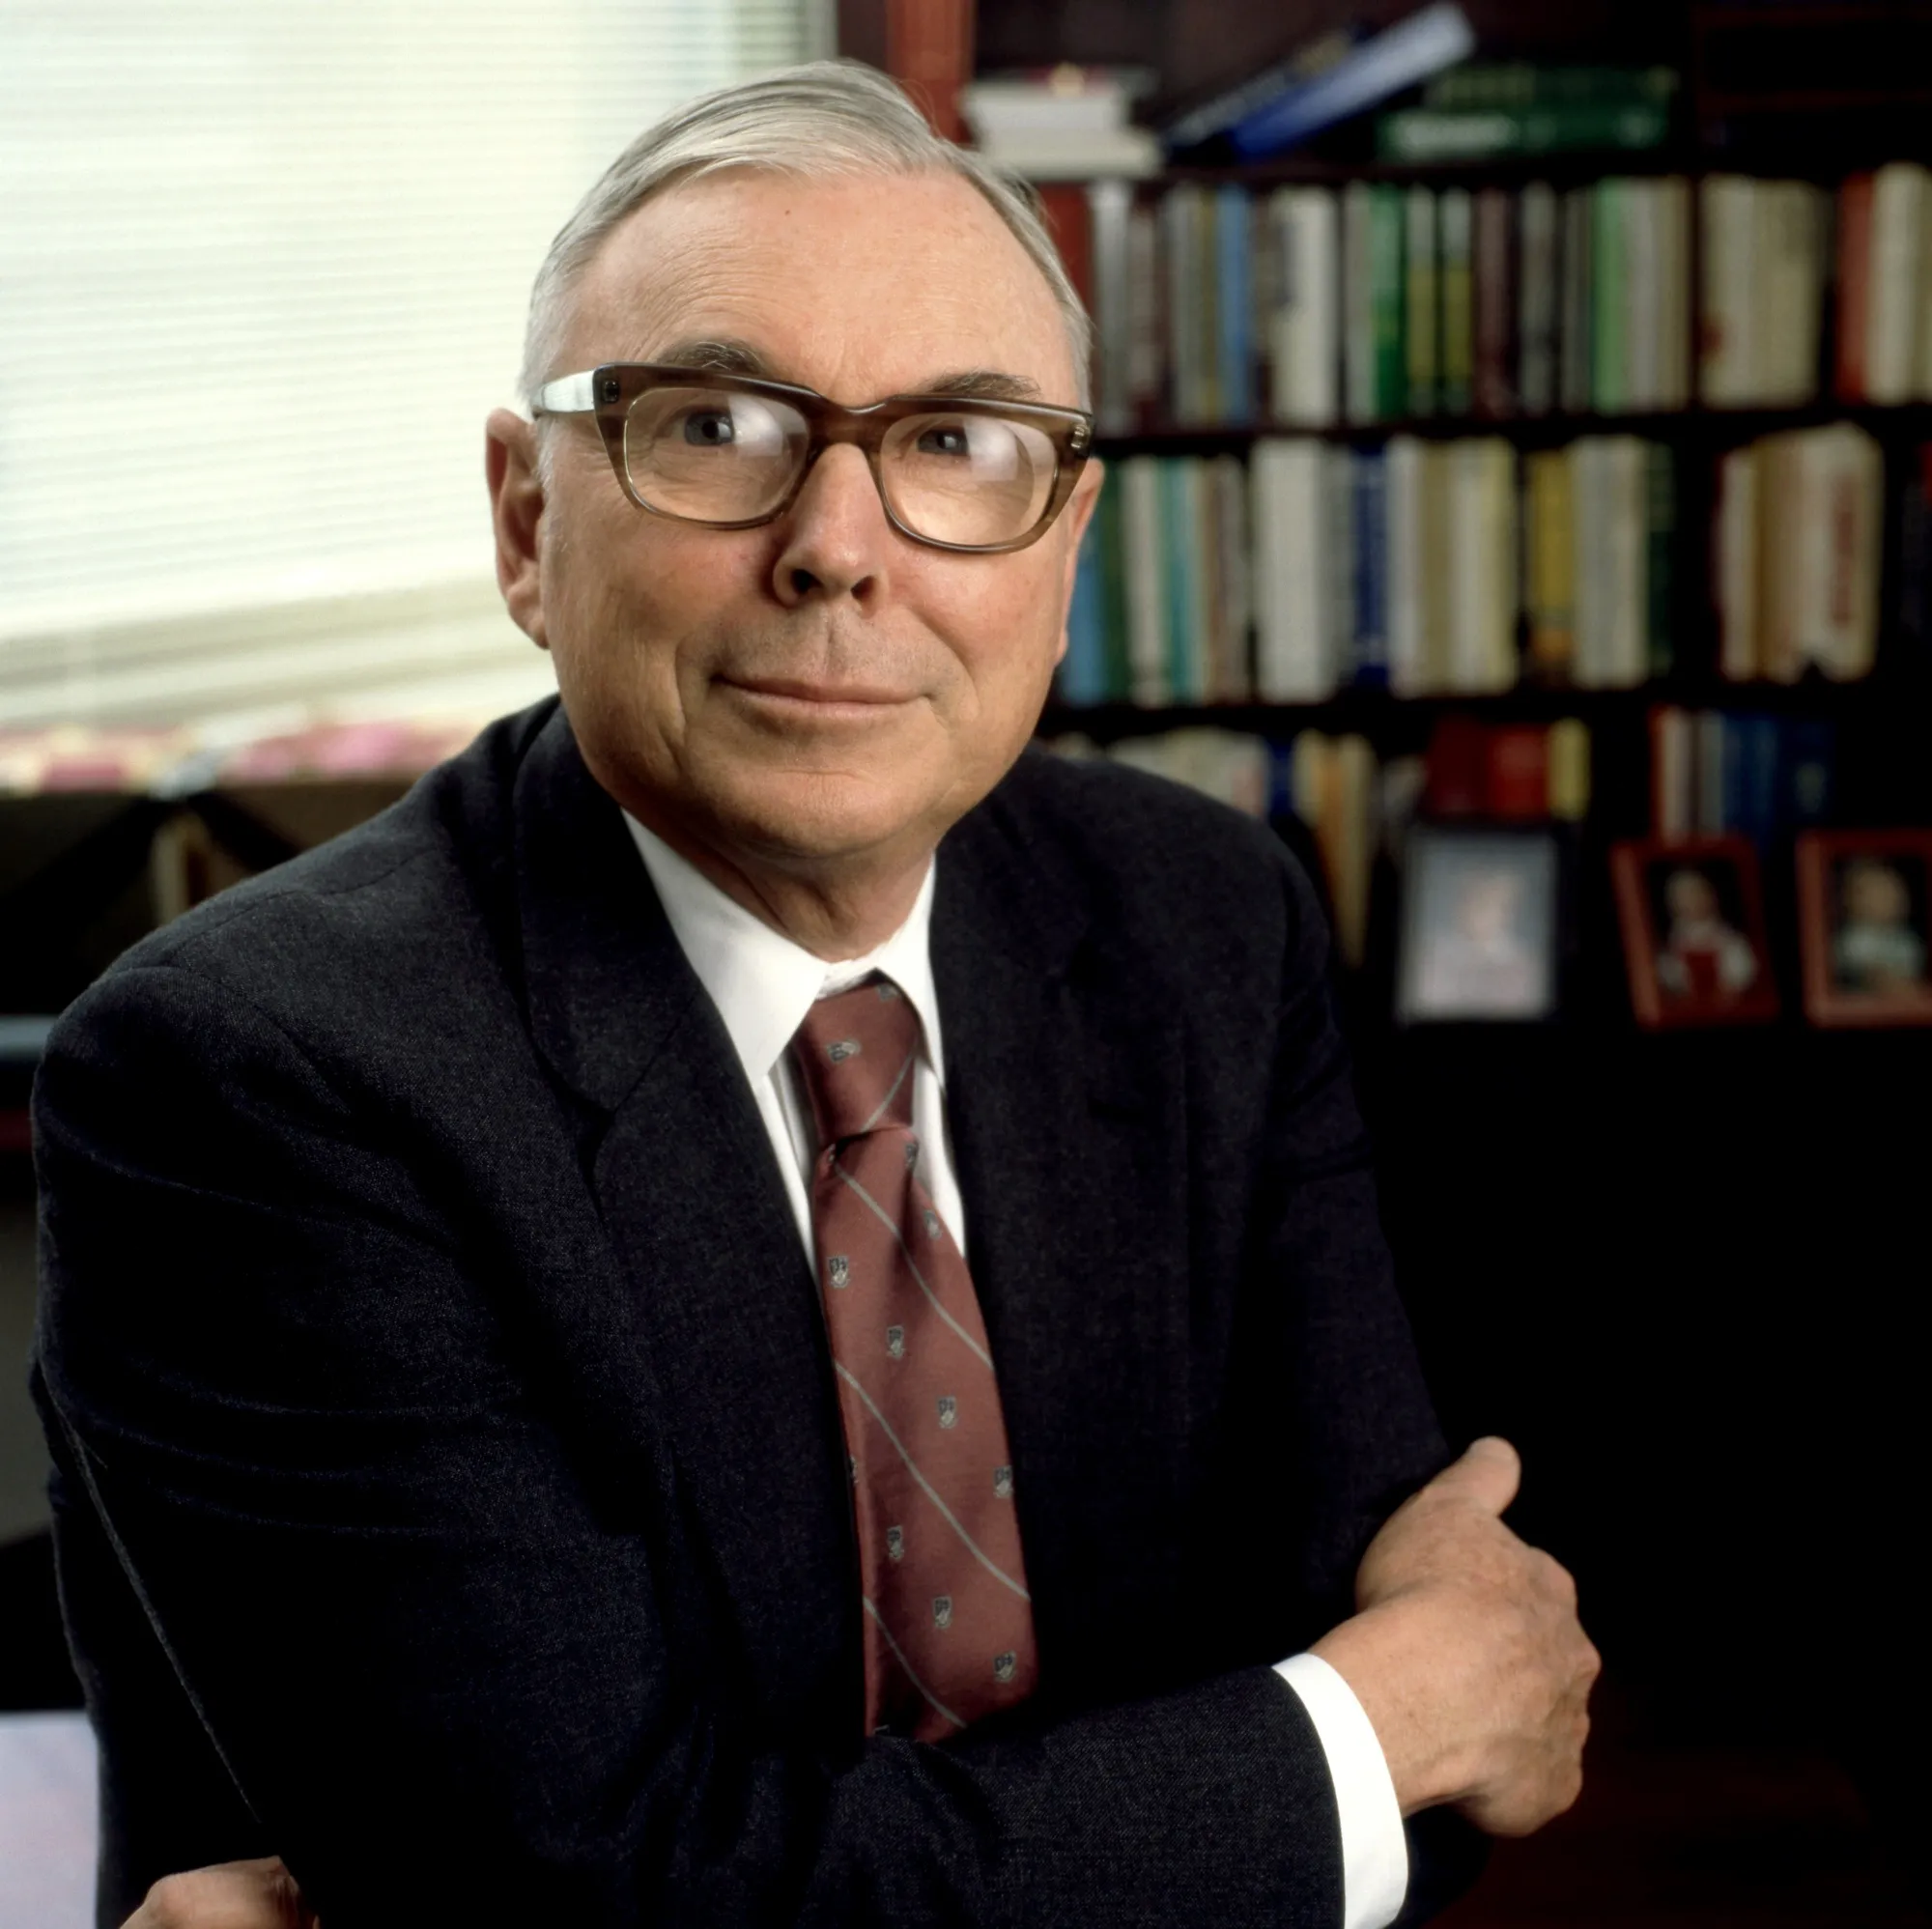
Breaking Down the Numbers
The financial legacy of Charlie Munger and Warren Buffett is staggering by any measure. Berkshire Hathaway’s stock price, which Buffett took over in 1965 at around $19 per share, surged to over $500,000 per share by 2023—an annualized return of roughly 20% over six decades. This outperformance isn’t just a statistical anomaly; it’s a testament to their ability to deploy capital with surgical precision. Their portfolio, spanning insurance, railroads, consumer brands, and even Apple, reflects a willingness to bet big on companies with durable competitive advantages. Yet the numbers tell only part of the story. Berkshire’s success isn’t just about returns—it’s about sustainability. While many conglomerates of their era collapsed under debt or poor governance, Berkshire thrived by avoiding leverage, retaining earnings, and letting compounding do the heavy lifting. Munger’s insistence on "circle of competence"—sticking to what you understand—meant Berkshire avoided the speculative bubbles that felled rivals. Their approach wasn’t just profitable; it was defensible.The Verified Baseline
Public records confirm that Warren Buffett and Charlie Munger first met in 1959, when Buffett, then 29, sought Munger’s legal advice on a real estate partnership. What began as a professional relationship evolved into a lifelong collaboration. By 1978, Munger joined Berkshire’s board, and by 1996, he became vice chairman—a role he held until his passing in 2023. Their partnership was formalized in a 1977 agreement where Buffett ceded operational control to Munger in exchange for his strategic oversight. Berkshire’s filings reveal their decision-making process in stark detail. For instance, the 1988 acquisition of Nebraska Furniture Mart—a retail giant—was driven by Munger’s admiration for its founder, Rose Blumkin, and her frugal, customer-centric ethos. Buffett’s letters later cited this deal as a prime example of their "economic moat" philosophy. Similarly, their 2016 purchase of Precision Castparts, a manufacturing conglomerate, highlighted their preference for businesses with pricing power and high returns on capital.What the Estimates Suggest
Industry estimates suggest that the combined net worth of Charlie Munger and Warren Buffett at their peaks exceeded $100 billion, though exact figures remain private. Buffett’s personal fortune, often cited as the largest in the U.S., is estimated to have fluctuated between $60 billion and $120 billion over his lifetime, with Berkshire’s Class A shares alone accounting for the majority. Munger, while never as publicly wealthy, reportedly held a stake in Berkshire worth tens of billions, along with significant holdings in other ventures like Daily Journal Corporation. Analysts speculate that their partnership generated hundreds of billions in shareholder value beyond Berkshire’s direct assets. For example, their influence on corporate governance—pushing for transparency, shareholder-friendly policies, and ethical leadership—has been adopted by institutions managing trillions. While precise valuation is impossible, their indirect impact on capital markets is estimated to dwarf even their most successful acquisitions.
Case Study: A Closer Look
Few decisions illustrate the Charlie Munger and Warren Buffett dynamic better than Berkshire’s 2011 purchase of IBM. At the time, IBM was a struggling tech giant, trading below its intrinsic value but facing structural challenges in cloud computing and hardware. Buffett, ever the optimist, saw potential in its services division and cash flow. Munger, however, was skeptical, warning in internal meetings that IBM’s legacy business models were obsolete. Their debate wasn’t about the numbers alone—it was about risk tolerance. Ultimately, Buffett prevailed, acquiring IBM for around $23 billion. The investment became a cautionary tale: IBM’s stock underperformed, and Berkshire later sold its stake at a loss. The episode underscored a key tension in their partnership—Buffett’s willingness to bet on turnarounds versus Munger’s preference for "obvious" winners. Yet even in failure, the decision revealed their process: they weighed options rigorously, debated fiercely, and accepted outcomes without recrimination."The first rule of investing is don’t lose money. The second rule is don’t forget the first rule." — Charlie Munger, reflecting on Berkshire’s IBM misstep.
| Factor | Estimated Impact |
|---|---|
| Buffett’s Optimism | Driven IBM purchase; later proved costly due to shifting tech trends. |
| Munger’s Caution | Advocated against deal; preferred businesses with clearer moats (e.g., Apple). |
| Compounding Effect | Even losses were absorbed by Berkshire’s scale; long-term portfolio remained resilient. |
| Lessons Learned | Reinforced Berkshire’s shift toward higher-margin, tech-adjacent investments post-2011. |
What This Means Going Forward
The departure of Charlie Munger in 2023 marked the end of an era, but their framework endures. Buffett’s successor, Greg Abel, has signaled continuity—not replication—of their principles. The challenge now is whether new leadership can maintain the discipline that defined their partnership. Early signs suggest Berkshire remains committed to value investing, though the absence of Munger’s contrarian edge may lead to more consensus-driven decisions. Their legacy also reshapes how we view leadership in business. Munger’s emphasis on multidisciplinary thinking—his "latticework of mental models"—has inspired a generation of investors to seek knowledge beyond finance. Buffett’s humility, meanwhile, proved that success isn’t about ego but about systems. As markets grow more complex, their example offers a counterpoint to short-termism: that patience, integrity, and deep thinking still outperform hype.
Conclusion
Charlie Munger and Warren Buffett weren’t just partners—they were architects of a new paradigm in capitalism. Their story is one of intellectual rigor, mutual respect, and an unwavering commitment to principle. While their individual contributions are celebrated, it’s their synergy that truly matters: Buffett’s intuition paired with Munger’s skepticism, Buffett’s deal-making tempered by Munger’s long-term vision. Their influence will be felt for decades. Whether in the boardrooms of Fortune 500 companies, the portfolios of retail investors, or the classrooms of business schools, the lessons of Charlie Munger and Warren Buffett remain the gold standard. The question now isn’t whether their approach can survive without them—it’s how deeply their principles have already been absorbed into the fabric of modern finance.Comprehensive FAQs
Q: How did Charlie Munger and Warren Buffett first meet?
They met in 1959 when Buffett, then a young investor, sought Munger’s legal advice on a real estate partnership in San Francisco. Their initial interaction evolved into a professional and later personal relationship that lasted over six decades.
Q: What was Charlie Munger’s role at Berkshire Hathaway?
Munger served as vice chairman from 1996 until his death in 2023. His role included overseeing corporate governance, strategic decisions, and mentoring Buffett—though he famously avoided the spotlight, preferring to work behind the scenes.
Q: Did Charlie Munger and Warren Buffett ever publicly disagree?
Yes, their disagreements were well-documented. Notably, Munger opposed Berkshire’s 2011 IBM purchase, while Buffett championed it. Their debates, however, were always constructive, with Munger often challenging Buffett to refine his thinking.
Q: How did their partnership influence corporate governance?
Their insistence on transparency, shareholder-friendly policies, and ethical leadership set a benchmark. Berkshire’s annual meetings became a model for corporate accountability, and their advocacy for rational capital allocation has shaped modern ESG (Environmental, Social, and Governance) standards.
Q: What is the most significant lesson from their collaboration?
Their partnership demonstrates the power of complementary thinking—combining Buffett’s deal-making instincts with Munger’s disciplined, multidisciplinary approach. The core lesson is that success in business, like in investing, requires both boldness and restraint.
Q: How has Berkshire Hathaway adapted since Charlie Munger’s passing?
Under Greg Abel’s leadership, Berkshire has maintained its value-investing principles but faces challenges in replicating Munger’s contrarian edge. Early moves suggest a focus on continuity, though the absence of Munger’s direct input may lead to more conservative decisions.
Q: Were there any acquisitions they regretted?
Yes, including IBM (2011) and the 2008 purchase of Goldman Sachs preferred stock during the financial crisis. Both deals underperformed, but they served as learning opportunities, reinforcing their emphasis on risk management over aggressive growth.
