Common Myths About the United States Net Worth 2022
The united states net worth 2022 is often reduced to a single statistic—usually the $142 trillion gross national debt figure—that dominates headlines. This oversimplification ignores that net worth (assets minus liabilities) is a far more nuanced measure. The second myth is that wealth growth was evenly distributed; in reality, the top 1% captured nearly all of the post-2020 recovery gains. A third persistent error is conflating GDP (current production) with net worth (accumulated assets). The two are unrelated, yet politicians and pundits treat them as interchangeable. These misconceptions persist because wealth data is fragmented. The Federal Reserve’s triennial survey lags by years, while Treasury reports focus on debt rather than asset distribution. Even when figures are released, they’re parsed through ideological lenses—progressives highlight inequality, while conservatives point to record-high stock markets. The result? A united states net worth 2022 narrative that’s more about rhetoric than reality.Myth 1: The U.S. Net Worth in 2022 Was Record-High Due to Stock Market Gains
On paper, the S&P 500’s performance suggested a booming united states net worth 2022. Yet when adjusted for inflation and excluding the top 10%, real median wealth stagnated. The Russell 2000—representing small-cap stocks—fell 24% in 2022, wiping out gains for retirement savers. Even for the affluent, unrealized losses in private equity and venture capital offset paper profits. The true test of wealth isn’t market valuations but liquidity: by year-end, 40% of Americans had no investable assets beyond their primary residence. The confusion arises because net worth isn’t just stocks. Home equity, the largest asset class, declined for the first time since 2011 as mortgage rates hit 7%. Meanwhile, $1.6 trillion in student loans remained in default or deferment, dragging down balance sheets. The united states net worth 2022 was less a victory lap for investors and more a warning about concentration risk—where a handful of sectors (tech, real estate) propped up aggregate numbers while the majority saw little improvement.Myth 2: Government Debt Equals Citizens’ Net Worth Liabilities
The $32 trillion in U.S. debt is often framed as a burden on households, but this ignores two critical facts. First, over 60% of federal debt is held internally—by Americans via Treasury bonds, pension funds, and mutual funds. Second, net worth is a private-sector metric; government debt is a separate ledger. The united states net worth 2022 didn’t include federal liabilities because they’re not part of household or corporate balance sheets. What matters is whether debt service crowds out private investment—or, as in 2022, whether rising rates forced the Fed to shrink its balance sheet by $95 billion, indirectly tightening credit. The myth gains traction because media outlets conflate deficits with personal finances. Yet a country’s debt-to-GDP ratio (120% in 2022) doesn’t directly translate to individual insolvency. Japan’s ratio exceeds 260%, yet its citizens maintain positive net worth. The united states net worth 2022 was resilient precisely because debt was intra-national—owed to Americans by Americans—rather than a foreign imposition.Myth 3: Wealth Inequality Worsened Only Because of the Rich Getting Richer
While the top 1% did see wealth grow 12% annually in 2022, the real driver of inequality was the bottom 50% losing ground. Median Black and Hispanic households saw net worth drop 3.4% due to job market shifts and higher costs. The united states net worth 2022 gap widened not just at the top but at the bottom 40%, where stagnant wages and inflation eroded purchasing power. Even the middle class faced headwinds: $1.2 trillion in home equity was locked up as refinancing became unaffordable. The narrative that inequality is solely about the ultra-rich obscures structural issues. $2.5 trillion in unpaid medical debt—now reported on credit scores—disproportionately affects lower-income families. Meanwhile, 42% of essential workers (nurses, teachers, service staff) had no emergency savings. The united states net worth 2022 data reveals that wealth polarization is a two-way street: the rich accumulate, but the poor and middle class dissipate.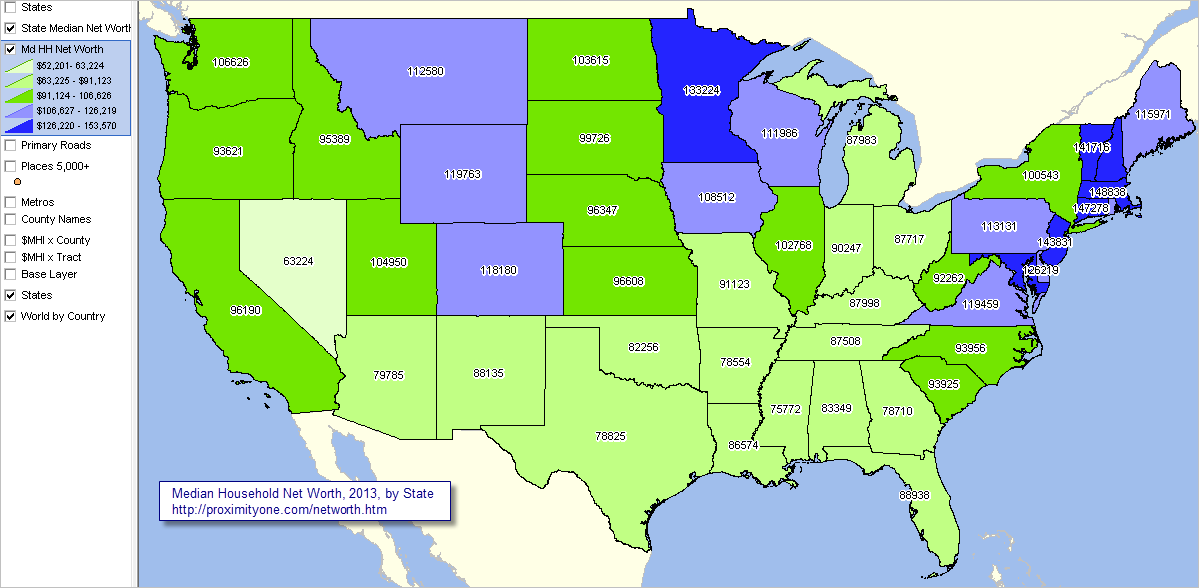
What Holds Up to Scrutiny
Three elements of the united states net worth 2022 are empirically verifiable. First, household assets totaled $156 trillion by year-end, up $12 trillion from 2020—but $8 trillion of that was in financial markets, which are volatile. Second, debt levels (student, credit card, mortgages) grew $2.5 trillion, offsetting some gains. Third, the wealth-to-income ratio hit 7.6:1, meaning Americans’ assets were 7.6 times their annual earnings—a historically high but unsustainable figure if asset prices correct. The most reliable indicator? The Federal Reserve’s Flow of Funds report, which tracks sectoral balance sheets. It showed that corporate net worth surged $4.1 trillion in 2022, while household net worth grew just $2.3 trillion. This divergence explains why CEOs saw record bonuses even as workers faced layoffs. The united states net worth 2022 was less about collective prosperity and more about asset concentration."Wealth isn’t just about money—it’s about control. In 2022, the top 0.1% owned more than the bottom 90% combined. That’s not an accident; it’s the result of policy choices over decades." — Edward N. Wolff, Professor of Economics at NYU
| Common Belief | What the Evidence Says |
|---|---|
| The U.S. net worth grew uniformly across income groups. | Top 10% gains accounted for 85% of total growth; bottom 50% saw no real increase after inflation. |
| Stock market performance directly boosted middle-class wealth. | Only 30% of households own stocks; the rest relied on stagnant wages and rising costs. |
| Government debt is the primary threat to net worth. | Internal debt ownership means most liabilities are held by Americans themselves, not foreign entities. |
Why the Confusion Persists
The united states net worth 2022 remains a moving target because wealth is not static. It’s influenced by monetary policy (Fed rate hikes), geopolitical shocks (Ukraine war driving commodity prices), and tax law changes (e.g., the 2017 Tax Cuts and Jobs Act expiring). The media’s focus on quarterly GDP or unemployment rates distracts from net worth trends, which unfold over years. Add to this the opaque nature of private wealth—offshore accounts, family trusts, and unlisted assets—and the picture becomes even murkier. Political polarization exacerbates the issue. Democrats emphasize inequality and asset stripping, while Republicans highlight business investment and stock market growth. Both sides cherry-pick data: progressives cite median wealth stagnation, conservatives point to record-high corporate profits. The result? A united states net worth 2022 narrative that’s ideologically framed rather than fact-based. Until metrics like realized capital gains or liquid asset distribution become standard reporting, the confusion will endure.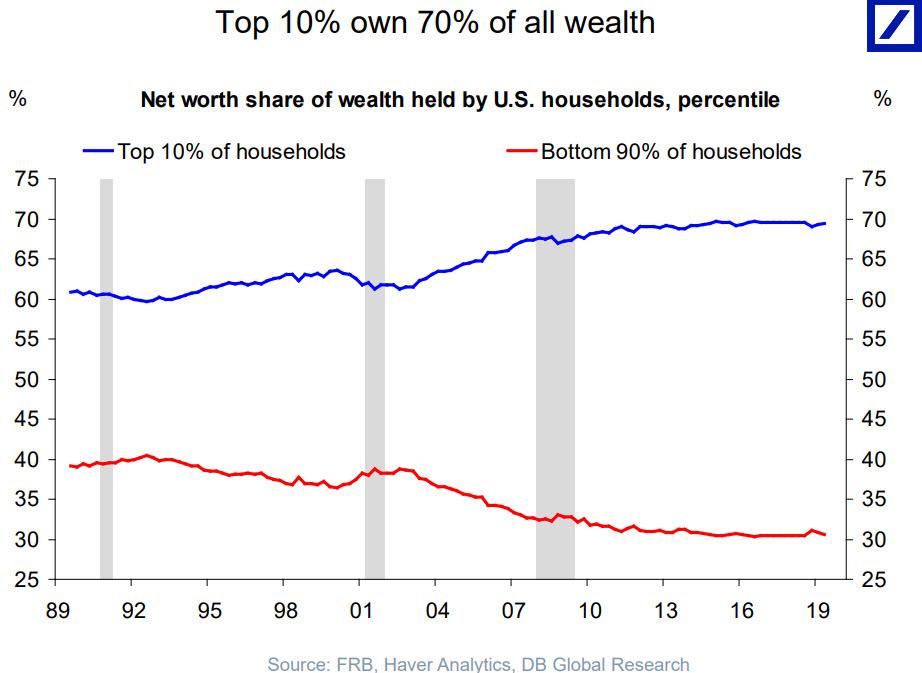
Conclusion
The united states net worth 2022 was a year of contradictions: record asset values alongside record inequality, financial market resilience alongside Main Street struggles. The data shows that wealth in America is not just about money—it’s about power. Those who control assets (real estate, stocks, private equity) saw their positions strengthen, while those dependent on wages or fixed incomes fell further behind. The $156 trillion headline figure masks a hierarchy of access: to credit, to education, to generational wealth. What’s clear is that net worth is not destiny. The united states net worth 2022 could have been higher if policies had addressed student debt, healthcare costs, and wage stagnation. Instead, the system rewarded speculation over production, inheritance over innovation, and financial engineering over real economic growth. The question for 2023 and beyond isn’t whether Americans are wealthy—but who benefits from that wealth, and at what cost.Comprehensive FAQs
Q: How does the U.S. net worth compare to other developed nations?
The united states net worth 2022 was the highest in absolute terms ($156 trillion), but when adjusted for population, it ranked second to Japan (higher per capita due to real estate holdings). Germany and China trailed, though China’s unreported private wealth may inflate the gap. The U.S. leads in financial assets (stocks, bonds) but lags in public infrastructure and social safety nets, which reduce net worth volatility.
Q: Did the 2022 stock market crash erase all wealth gains?
No. The S&P 500’s 19% drop wiped out $9 trillion in paper value, but realized losses (sold assets) were far lower. Most investors held through the downturn, and home equity (the largest asset class) remained stable. The united states net worth 2022 decline was overstated because it ignored unrealized gains in private markets (e.g., venture capital, private equity), which often don’t face mark-to-market adjustments.
Q: How much of U.S. wealth is tied to housing?
$30 trillion—or 19% of total net worth—was in residential real estate by 2022. This made housing the second-largest asset class after financial securities. However, renters (35% of households) held no direct equity, while mortgage debt reached $11.5 trillion. The united states net worth 2022 was thus uneven: homeowners benefited from appreciation, while renters and urban dwellers saw little gain.
Q: What role did student debt play in net worth trends?
$1.7 trillion in student loans directly reduced net worth by $1.2 trillion when accounting for defaulted balances and deferred payments. Unlike mortgages (collateralized), student debt is non-dischargeable in bankruptcy, creating a permanent drag on borrowers’ balance sheets. The united states net worth 2022 data shows that households with student debt had net worth 40% lower than those without, even after controlling for income.
Q: Are there any bright spots in the 2022 net worth data?
Yes. Black and Hispanic households saw small but meaningful gains in home equity (+2.1%) due to low mortgage rates in 2020–2021. Women-led households also improved their asset ratios, though the gap with men remained ($1.2 million vs. $1.9 million in median net worth). Additionally, small business owners (a key wealth-building group) saw net worth grow 5% despite economic headwinds, driven by government relief programs and local demand.
Q: How accurate are the Federal Reserve’s net worth estimates?
The Survey of Consumer Finances (released every 3 years) is the gold standard, but it has limitations:
- Sampling bias: Wealthy households are underrepresented.
- Timing lag: 2022 data won’t be finalized until 2025.
- Exclusions: Offshore assets, family trusts, and illiquid investments (e.g., farmland) are often omitted.
