
The Complete Overview of UK Net Worth in 2018
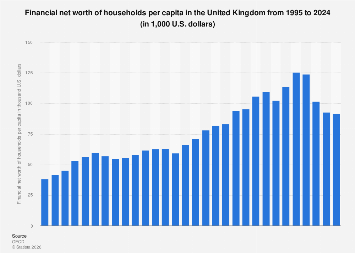
The UK net worth 2018 landscape was defined by three dominant forces: asset inflation, demographic shifts, and the lingering effects of the 2008 financial crisis. House prices, propped up by low interest rates and high demand, drove a significant portion of wealth accumulation. The average UK homeowner’s net worth surged as property values climbed, but this wealth was unevenly distributed—homeownership rates in London exceeded 60%, while in some northern cities, they hovered below 50%. Meanwhile, the stock market’s resilience, fueled by corporate buybacks and global investor confidence, added to the wealth of those with pension or investment portfolios. Yet beneath the surface, cracks were forming. The ONS highlighted that UK net worth 2018 was heavily concentrated in financial assets—pensions, stocks, and property—rather than liquid savings. Younger generations, saddled with student debt and stagnant real wages, saw their net worth grow at a fraction of the pace of older cohorts. The wealth gap between generations became a defining feature of the year, with the over-65s holding nearly twice the net worth of the under-35s. This wasn’t just a financial issue; it was a social one, with implications for intergenerational equity and long-term economic stability.Historical Background and Evolution
To understand UK net worth 2018, one must trace the trajectory of wealth accumulation over the past two decades. The early 2000s saw a housing boom that inflated personal balance sheets, only for the 2008 crash to wipe out trillions in equity. By 2018, the recovery had been uneven. While property prices rebounded—particularly in prime markets—many families still hadn’t regained pre-crisis wealth levels. The UK net worth 2018 figures reflected this patchwork recovery, with some households thriving and others still playing catch-up. The post-crisis era also saw a shift in wealth composition. Pension funds, bolstered by quantitative easing and low yields, became a cornerstone of personal wealth for older Britons. Meanwhile, the rise of gig economy platforms and side hustles created new avenues for wealth generation, though these were often precarious and lacked the security of traditional employment. The UK net worth 2018 data captured this duality: a system where some leveraged financial instruments to build fortunes, while others relied on debt to maintain their standard of living.Core Mechanisms: How It Works
The mechanics of UK net worth 2018 were rooted in three pillars: asset appreciation, income generation, and debt management. Property remained the single largest driver, with homeowners benefiting from capital gains that outpaced wage growth. For those without property, wealth was tied to pensions, savings accounts, or investments—all of which were vulnerable to market fluctuations. The Bank of England’s monetary policy, particularly the base rate cuts following the Brexit referendum, played a critical role in keeping borrowing costs low and asset prices elevated. Income inequality further shaped the UK net worth 2018 landscape. High earners in finance, tech, and law accumulated wealth at a far greater rate than the median worker. Tax policies, such as the reduction in capital gains tax for higher earners, reinforced this disparity. Meanwhile, the gig economy offered flexibility but often at the expense of job security and benefits, complicating wealth accumulation for those outside traditional employment.Key Benefits and Crucial Impact
The UK net worth 2018 boom had tangible benefits for those who participated in asset markets. Homeowners in strong property markets saw their equity multiply, while investors in equities and bonds rode a wave of global growth. For businesses, easy access to credit and a skilled workforce fueled expansion, particularly in sectors like fintech and renewable energy. The wealth effect—where rising asset values encourage spending—stimulated consumer demand, supporting retail and service industries. Yet the impact was not uniformly positive. The concentration of wealth in financial assets left many vulnerable to market downturns. The UK net worth 2018 figures also highlighted a stark regional divide: London and the Southeast accounted for nearly 60% of the country’s total wealth, while northern regions lagged. This geographic disparity had political and social repercussions, fueling debates about fiscal redistribution and regional investment."Net worth is not just about money—it’s about opportunity. When wealth is concentrated in a few hands, it’s not just an economic issue; it’s a question of who gets to participate in the economy and who doesn’t." — Andrew Haldane, former Chief Economist at the Bank of England
Major Advantages
- Asset appreciation drove wealth growth, particularly in property and equities, benefiting homeowners and investors.
- Low interest rates and quantitative easing policies supported borrowing and spending, sustaining consumer demand.
- Strong corporate performance, especially in London’s financial sector, boosted pension funds and shareholder wealth.
- Technological advancements in fintech and digital banking expanded access to financial tools, though often with uneven benefits.
Comparative Analysis
| Metric | UK (2018) | US (2018) | Germany (2018) |
|---|---|---|---|
| Total Net Worth (trillions) | £12.3 | $104.6 | €10.2 |
| Wealth per Adult (median) | £230,000 | $120,000 | €110,000 |
| Homeownership Rate | 63% | 65% | 51% |
| Top 10% Wealth Share | 47% | 70% | 55% |
Future Trends and Innovations
Looking ahead from 2018, the UK net worth trajectory faced two competing forces: the potential for continued asset growth and the risks of economic instability. Brexit’s unresolved status cast a shadow over business confidence, while demographic trends—an aging population and declining birth rates—threatened long-term productivity. Innovations in fintech, such as robo-advisors and blockchain-based assets, promised to democratize wealth management, but adoption remained uneven. The UK net worth 2018 data also signaled a growing urgency around wealth inequality. Policymakers grappled with how to address the generational divide, while social movements pushed for greater transparency in corporate ownership and tax avoidance. The coming years would test whether the UK could reconcile its financial success with broader societal equity—or whether the wealth gap would continue to widen.
Conclusion
The UK net worth 2018 snapshot was a study in contrasts: a nation with record-high wealth on paper, but where opportunity remained tightly controlled. The data revealed not just economic trends but the fault lines of a society in transition. For those who benefited from asset inflation and strong markets, the outlook was optimistic. For others, the challenges of stagnant wages, high costs of living, and uncertain futures loomed large. The lessons of 2018 were clear: wealth is not distributed by accident, and its accumulation reflects deeper structural forces. Moving forward, the UK’s ability to address inequality, invest in human capital, and adapt to technological change would determine whether its wealth story becomes one of shared prosperity—or continued division.Comprehensive FAQs
Q: How did Brexit affect UK net worth in 2018?
The uncertainty surrounding Brexit contributed to market volatility, particularly in financial assets. While some investors sought refuge in sterling-denominated assets, others pulled capital out, leading to fluctuations in property and equity values. The UK net worth 2018 figures reflect this turbulence, with wealth growth slowing in sectors most exposed to trade and regulatory changes.
Q: Were there significant regional differences in UK net worth in 2018?
Yes. London and the Southeast accounted for the majority of the country’s wealth, with homeownership rates and property values far outpacing those in northern regions. Cities like Manchester and Birmingham saw slower wealth growth, partly due to lower property appreciation and wage stagnation. The UK net worth 2018 data underscored a north-south divide that has persisted for decades.
Q: How did pension wealth contribute to UK net worth in 2018?
Pensions were a critical component of UK net worth 2018, particularly for older generations. With low interest rates and strong stock market performance, defined contribution pension funds grew significantly. However, younger workers faced challenges due to auto-enrolment limitations and the risk of underfunded pensions in the event of market downturns.
Q: What role did debt play in shaping UK net worth in 2018?
Household debt remained a double-edged sword. While low mortgage rates allowed homeowners to service loans, high levels of consumer debt—particularly among younger borrowers—posed risks. The UK net worth 2018 figures showed that for many, wealth was leveraged, meaning a rise in interest rates could erode net worth rapidly.
Q: How did the gig economy impact personal net worth in 2018?
The gig economy offered flexible income streams but often at the cost of job security and benefits. While some gig workers accumulated savings or invested earnings, others struggled with inconsistent income. The UK net worth 2018 data did not fully capture gig economy wealth, as many participants lacked traditional financial assets like property or pensions.
