Where It All Began
Timberland ownership traces its modern roots to the late 19th century, when railroads and industrial sawmills turned forests into commodities. The first timberland owners were often loggers or homesteaders who saw wood as a renewable resource—one that could be harvested, replanted, and harvested again. By the 1920s, companies like Weyerhaeuser and Georgia-Pacific had consolidated millions of acres, treating timberland as a perpetual crop. The model was simple: plant, grow, cut, repeat. But the Great Depression and the Dust Bowl exposed a flaw in this thinking. Without proper management, forests could be depleted faster than they regrew, leaving owners with barren land and no income. The turning point came in the 1930s with the creation of the U.S. Forest Service and the passage of the Taylor Grazing Act. For the first time, timberland ownership was tied to sustainability mandates. The federal government began enforcing rotation cycles, reforestation requirements, and even soil conservation practices. Timberland owners who resisted these rules found themselves locked out of markets—or worse, facing fines. The shift wasn’t just regulatory; it was cultural. The idea that a forest could be both an economic asset and an ecological system took hold. Early adopters who embraced these changes became the first generation of timberland owners to think beyond the stumpage price.The Early Signs
The 1970s and 1980s marked the beginning of timberland’s transformation into a financial asset class. As real estate markets boomed, investors began treating forests like any other property—something to leverage, diversify, or hedge against inflation. The first timberland investment trusts (TIMOs) emerged, allowing retail investors to buy shares in professionally managed forestry operations. Meanwhile, institutional players like Harvard’s endowment and the California Public Employees’ Retirement System (CalPERS) quietly acquired millions of acres, viewing timberland as a low-volatility alternative to stocks and bonds. But not all timberland owners welcomed this shift. Family operators in the Pacific Northwest watched as corporate buyers snapped up old-growth stands, often at prices that reflected speculative value rather than timber yield. The conflict between traditional stewards and financial opportunists came to a head in the 1990s, when environmental groups targeted clear-cutting practices. Timberland owners who had relied on high-grading—the practice of cutting only the most valuable trees—found themselves facing lawsuits, boycotts, and plummeting timber prices. The lesson was clear: the future belonged to those who could balance profit with preservation.The Turning Point
The 2008 financial crisis didn’t just crash housing markets—it exposed the fragility of timberland as an unmanaged asset. Many timberland owners who had borrowed heavily against their property found themselves underwater as lumber prices collapsed. But the crisis also forced a reckoning. Those who survived did so by diversifying revenue streams: carbon credits, recreational leases, and even renewable energy projects on forested land. The timberland owner of the 21st century wasn’t just growing trees; they were managing multiple income layers—some visible, some hidden. The real inflection point came with the Paris Agreement in 2015. Suddenly, forests weren’t just about wood—they were about climate mitigation. Timberland owners who had long dismissed carbon markets as a fringe concern found themselves courted by offset buyers, conservation groups, and even tech giants looking to neutralize their emissions. A single acre of well-managed forest could now generate thousands in carbon credits annually. The shift wasn’t just economic; it was existential. Timberland ownership had become a climate-resilient strategy, one that aligned with ESG (Environmental, Social, and Governance) investing trends."We used to think of timberland as a place to cut trees. Now, it’s a place to store carbon, filter water, and even generate power. The best owners are the ones who see the forest for more than just the trees." — A senior timber analyst at a major investment firm, 2022
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1990s–2000 | Timberland ownership fragmented as family operators sold to institutional buyers. The rise of TIMOs (Timber Investment Management Organizations) made forests accessible to retail investors. However, the dot-com bubble and 9/11 created volatility, leading some timberland owners to diversify into recreational leases (hunting, camping). |
| 2005–2015 | Climate change became a material risk. Timberland owners in fire-prone regions (e.g., California, Australia) began investing in fire-resistant species and proactive thinning. The first major carbon credit deals emerged, with some timberland owners selling offsets to corporations. Meanwhile, Chinese demand for softwoods drove up prices, benefiting owners in the Southeast U.S. |
| 2016–Present | Timberland ownership entered the ESG era. Institutional investors now demand sustainability certifications (e.g., FSC, PEFC) before acquiring properties. Technology plays a larger role—drones for inventory management, AI for predicting timber yields, and blockchain for tracking carbon credits. The pandemic accelerated remote work trends, boosting demand for recreational forestland as urbanites sought second homes in wooded areas. |
Lessons From the Journey
- Diversification isn’t just about tree species. The most successful timberland owners spread risk across timber harvests, carbon credits, and alternative uses (e.g., solar farms on cleared land, agri-forestry).
- Regulation is your friend. Timberland owners who proactively comply with environmental laws (e.g., Endangered Species Act protections) avoid costly lawsuits and access premium markets.
- Patience is the only constant. Timber takes decades to mature, but the best timberland owners think in centuries. Family forests that have been managed for 100+ years often command higher values.
- Location matters more than ever. Proximity to mills, ports, and urban centers determines timberland value. Meanwhile, climate resilience (e.g., drought-resistant species, firebreaks) is becoming a competitive advantage.
Where Things Stand Today
Timberland ownership in 2024 is a study in contradictions. On one hand, forests are more valuable than ever—global timber prices hit record highs in 2023 as housing demand surged. On the other, climate risks (wildfires, pests, shifting growing seasons) threaten long-held assumptions about timberland as a "safe" asset. The timberland owner today must navigate this tension: how to extract value without depleting the resource. Institutional players dominate the space, with pension funds and sovereign wealth funds controlling the majority of commercially managed timberland. But family operators still hold sway in high-quality, low-disturbance forests—properties that institutional buyers often overlook due to their illiquidity. The rise of impact investing has also created new opportunities. Timberland owners who can demonstrate biodiversity benefits, water filtration, or community engagement now command premiums from socially conscious investors. Yet the biggest story may be the silent migration of urban capital into timberland. As interest rates rise and housing markets stagnate, high-net-worth individuals are turning to forests as a hedge against inflation. Private equity firms are snapping up timberland assets, repackaging them as alternative investments for accredited investors. The timberland owner of tomorrow may not even live near a forest—just a digital portfolio manager in New York or Singapore.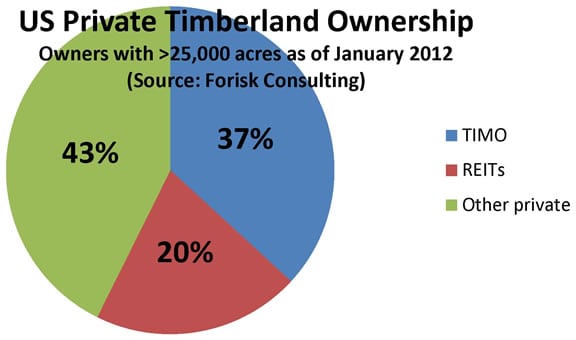
Conclusion
Timberland ownership has always been a test of patience. But the test has changed. No longer is it enough to plant a tree and wait for it to grow. The modern timberland owner must also anticipate climate shifts, navigate regulatory labyrinths, and balance ecological and financial returns. The best in the field don’t just grow trees—they engineer ecosystems. The irony is that as timberland becomes more financialized, its non-financial value grows in importance. A forest isn’t just an asset; it’s a carbon sink, a water purifier, a habitat. The timberland owners who thrive in the coming decades will be those who recognize this duality—and act accordingly. For them, the land isn’t just a plot of earth. It’s a legacy.Comprehensive FAQs
Q: Is timberland ownership still profitable in 2024?
Profitability depends on management strategy and location. Well-managed timberland in high-demand regions (e.g., Pacific Northwest, Southeast U.S.) can yield 5–10% annual returns, often outperforming stocks and bonds over the long term. However, poorly managed properties—especially those vulnerable to wildfires or pests—can lose value. Carbon credits and alternative revenue streams (e.g., hunting leases) have become critical for diversifying income.
Q: How much does it cost to buy timberland?
Prices vary wildly by region, species, and accessibility. In the Southeast U.S., timberland can cost as little as $1,000–$3,000 per acre for lower-quality land, while prime old-growth forests in the Pacific Northwest may exceed $50,000 per acre. Institutional buyers often pay premiums for certified sustainable management (e.g., FSC), while family operators may acquire land at below-market rates through inheritance or seller financing.
Q: Can I start with a small plot of timberland?
Yes, but scale matters. A 5–10-acre parcel can be managed for personal use (firewood, hunting) or small-scale timber sales, though returns will be modest. For serious investment, 100+ acres is ideal, as it allows for diversified species, carbon credit eligibility, and economies of scale in harvesting. Many timberland owners start small and consolidate over time through partnerships or acquisitions.
Q: What are the biggest risks in timberland ownership?
The top risks include:
- Climate change: Wildfires, droughts, and pests (e.g., bark beetles) can devastate timber stands.
- Regulatory shifts: New environmental laws (e.g., expanded Endangered Species Act protections) can restrict harvesting.
- Market volatility: Lumber prices swing dramatically—what’s a boom year can turn into a bust.
- Liquidity constraints: Timberland is illiquid; selling quickly often means taking a loss.
Q: Do I need to be a forester to own timberland?
No, but professional management is essential for profitability. Many timberland owners hire forestry consultants or work with Timber Investment Management Organizations (TIMOs) to handle harvesting, reforestation, and regulatory compliance. For smaller plots, online tools and local cooperatives can provide guidance. However, DIY management without expertise often leads to poor yields or legal issues.
Q: How do carbon credits work for timberland owners?
Carbon credits allow timberland owners to monetize the CO₂ their forests sequester. Programs like Verra’s VCS or American Carbon Registry verify emissions reductions, which can then be sold to corporations or governments. A single acre of well-managed forest may generate $50–$500 per year in credits, depending on species, soil type, and verification costs. However, selling credits requires certification, which involves third-party audits and ongoing monitoring.
Q: What’s the future of timberland ownership?
The next decade will likely see:
- More institutional involvement: Pension funds and ESG-focused investors will drive demand for sustainably managed timberland.
- Technology integration: Drones, AI, and blockchain for carbon tracking will improve efficiency.
- Climate adaptation as a competitive edge: Timberland owners who diversify species (e.g., drought-resistant oak over pine) will outperform.
- Urban migration into forests: As remote work grows, recreational timberland (hunting, cabins) will see increased demand.
