7 Things Worth Knowing About the Tax Benefits of 1031 Exchanges to High Net Worth Investors
The 1031 exchange is often framed as a tax deferral tool, but its power lies in how it interacts with broader financial strategies. For HNWIs, it’s not just about avoiding taxes—it’s about reallocating capital more efficiently, accessing better financing terms, and even hedging against inflation. The nuances, however, demand attention. Below are the seven pillars that separate successful exchanges from costly missteps.1. The Deferral Isn’t Permanent—But It Can Be Indefinite
The core of the tax benefits of 1031 exchanges to high net worth investors is the deferral of capital gains taxes. When an investor sells a property and reinvests the proceeds into a "like-kind" replacement property, the IRS defers recognition of the gain until the replacement property is sold. This isn’t a tax holiday; it’s a postponement. The clock only starts ticking when the new property is disposed of. For investors with multi-generational wealth plans, this creates a compounding effect. A property purchased in 1995 for $500,000 might now be worth $5M. Without a 1031 exchange, selling it could trigger a $3.5M+ tax bill (assuming a 20% long-term capital gains rate). Instead, that capital stays deployed, growing through reinvestment. The indefinite nature of this deferral is its greatest strength. Some investors hold replacement properties for decades, passing them to heirs who then execute another 1031 exchange. This strategy exploits the step-up in basis at death—heirs receive the property at its fair market value, resetting the capital gains clock. The IRS doesn’t mandate a final sale; it only requires that the deferral be honored until the property is no longer held for investment or productive use.2. Like-Kind Requirement: More Flexible Than You Think
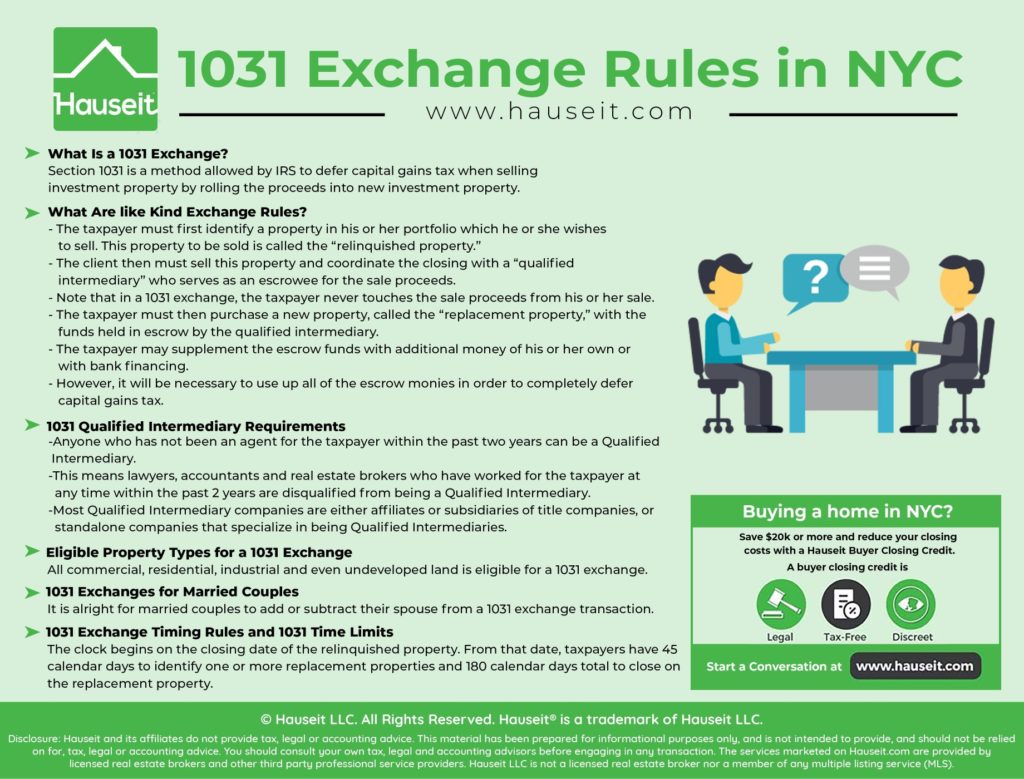
The "like-kind" rule is the most misunderstood aspect of the tax benefits of 1031 exchanges to high net worth investors. Contrary to popular belief, the IRS doesn’t require identical properties. The definition has evolved: real estate held for investment or business use qualifies, regardless of whether it’s residential, commercial, or land. A single-family rental property can be exchanged for a multi-unit apartment complex, or a retail strip mall for vacant land zoned for development. The key is the intent: both properties must be used for income generation or business purposes, not personal use (e.g., a primary residence doesn’t qualify). What’s changed in recent years is the IRS’s scrutiny of related-party exchanges and self-directed exchanges. For HNWIs, this means avoiding transactions with family members or entities they control, as these can trigger immediate tax recognition. The IRS also now requires qualified intermediaries to hold exchange funds, eliminating the risk of commingling personal and exchange funds. These safeguards ensure the exchange remains legitimate while preserving its tax advantages.3. The 45-Day Rule: Timing Is Everything
The 45-day identification period is where many exchanges fail. Investors must identify potential replacement properties within 45 days of selling the relinquished property. The rules allow for three identification methods: - Three-property rule: Up to three properties of any value. - 200% rule: Any number of properties, but their total value cannot exceed 200% of the relinquished property’s value. - Single-property rule: One property of any value. For high-net-worth investors, the 200% rule is often the most flexible. Suppose an investor sells a $10M property; they can identify up to $20M in replacement properties. However, the 180-day deadline to close on the replacement property is non-negotiable. Missing either deadline voids the exchange, and the investor faces retroactive capital gains taxes plus penalties. Elite investors mitigate this risk by pre-identifying properties, securing financing in advance, and working with intermediaries who specialize in high-value transactions.4. Boot and Mortgage Relief: The Hidden Leverage Play
When a 1031 exchange involves boot—cash or other non-like-kind property received in the transaction—the tax-deferred portion is reduced by the boot amount. For example, if an investor sells a property for $5M but takes $1M in cash (boot), only $4M of gain is deferred. The $1M is taxable immediately. However, this isn’t necessarily a drawback. HNWIs often use boot strategically to reduce basis in the replacement property, lowering future capital gains taxes. Additionally, if the replacement property is financed, the mortgage can offset boot. For instance, if the replacement property has a $2M mortgage, the investor’s cash contribution is effectively reduced, minimizing boot and preserving the deferral. This leverage aspect is why many investors structure exchanges to increase debt. By taking on more mortgage debt in the replacement property, they defer more gain while improving cash flow. The IRS allows this as long as the debt is non-recourse (i.e., the lender’s only remedy is the property). This tactic is common among commercial real estate investors who use 1031 exchanges to consolidate smaller properties into larger, more efficiently financed assets.5. The Qualified Intermediary: A Non-Negotiable Partner
The IRS prohibits investors from holding exchange funds directly. Instead, they must use a qualified intermediary (QI), a third-party entity that facilitates the exchange. The QI holds the sale proceeds and disburses them only to purchase the replacement property. This requirement exists to prevent investors from effectively "selling" to themselves—a practice the IRS would classify as a taxable event. For high-net-worth investors, selecting the right QI is critical. Fees can range from $1,500 to $5,000 per transaction, but the cost pales compared to the risk of a failed exchange. Some QIs specialize in reverse exchanges, where the replacement property is acquired before the relinquished property is sold. This is useful when the investor wants to secure a prime asset before selling their current holding. However, reverse exchanges are complex and require careful structuring to avoid triggering taxable events. HNWIs often pair these with installment sales to manage cash flow while maintaining exchange eligibility.6. State Tax Implications: A Patchwork of Rules
While the IRS governs federal tax deferral, state tax laws vary widely. Some states, like California and New York, conform to federal 1031 rules, meaning the deferral applies at both levels. Others, such as Texas and Florida, don’t impose capital gains taxes on real estate sales, making 1031 exchanges less critical. However, states like Massachusetts and Oregon have unique rules: they may tax deferred gains if the replacement property is sold within a certain period. HNWIs with multi-state portfolios must navigate this landscape carefully. For example, an investor selling a property in California (where prop 13 limits reassessment) might exchange into a state with higher capital gains rates, only to face unexpected liabilities years later. The solution? Tax planning in advance. Investors should consult state-specific attorneys to model how deferred gains will be treated upon eventual disposition. Some states allow for basis adjustments that reduce future taxable gains, while others impose recapture rules that accelerate tax recognition. Ignoring state laws can turn a deferred gain into an immediate liability.7. The 1031 Exchange and Estate Planning: A Generational Strategy
The most sophisticated use of the tax benefits of 1031 exchanges to high net worth investors lies in estate planning. By deferring capital gains indefinitely, investors can pass appreciated properties to heirs who then execute another 1031 exchange. This generational deferral strategy exploits the step-up in basis at death, resetting the capital gains clock for future heirs. For families with real estate wealth, this can mean millions in tax savings over multiple generations. Consider a family that owns a $20M commercial portfolio. Without 1031 exchanges, selling it could trigger a $10M+ tax bill. Instead, the family exchanges into a new property, defers the gain, and passes the asset to the next generation, who repeats the process. The IRS doesn’t care about family succession—only about the timing of the sale. However, this strategy requires proactive planning. Heirs must be educated on the exchange process, and the family should structure ownership (e.g., LLCs, trusts) to facilitate smooth transitions. Some HNWIs use intentionally defective grantor trusts (IDGTs) to hold replacement properties, allowing heirs to access cash flow while deferring taxes. The key is ensuring that each generation’s exchange complies with IRS rules, avoiding the related-party transaction pitfalls that can void deferral.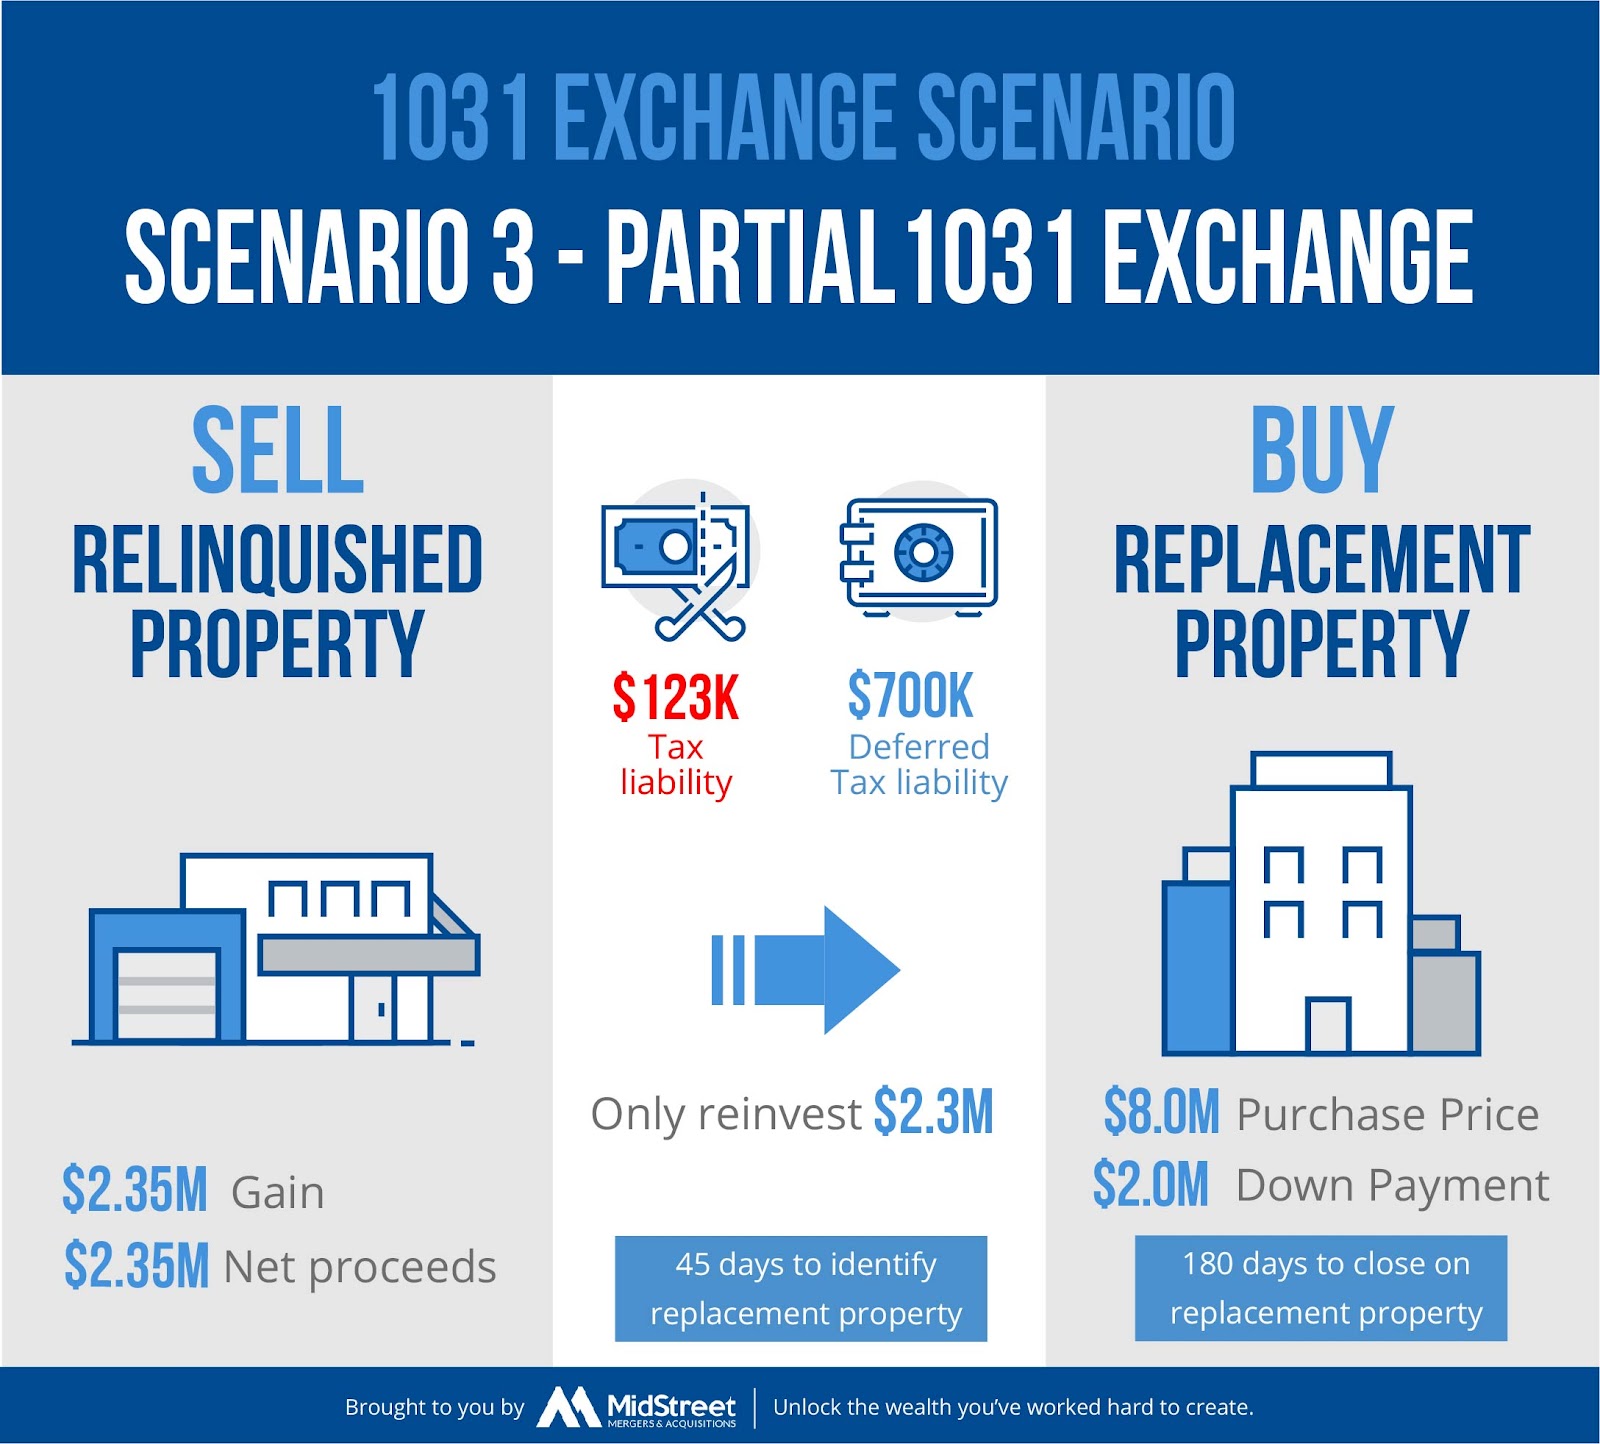
How These Facts Connect
The tax benefits of 1031 exchanges to high net worth investors aren’t isolated advantages—they form a cohesive system designed to preserve and grow wealth. The deferral mechanism (Point 1) is the foundation, but its power is amplified by the flexibility of like-kind rules (Point 2) and the strategic use of leverage (Point 4). Timing (Point 3) and professional intermediaries (Point 5) ensure the exchange executes flawlessly, while state laws (Point 6) and estate planning (Point 7) determine how the deferral cascades across generations. Together, these elements create a tax-efficient real estate engine that outperforms traditional sell-and-reinvest strategies. The most revealing insight? The 1031 exchange is a liquidity multiplier. By deferring taxes, investors retain more capital to deploy into higher-yielding or more strategic assets. This isn’t just about avoiding taxes—it’s about reallocating capital more aggressively, accessing better financing, and structuring wealth for long-term growth. The table below contrasts the three most critical components of this strategy:| Component | Key Advantage | Primary Risk |
|---|---|---|
| Deferral Mechanism | Preserves capital for reinvestment; compounds growth over time. | Taxes become due upon eventual sale, potentially at a higher rate. |
| Like-Kind Flexibility | Allows portfolio diversification without tax consequences. | Related-party exchanges or personal-use properties void deferral. |
| Leverage via Boot & Mortgages | Increases purchasing power; improves cash flow. | Excessive boot reduces deferred gain; financing terms must align. |

Conclusion
The tax benefits of 1031 exchanges to high net worth investors extend far beyond simple tax avoidance. They represent a structural advantage in wealth preservation, allowing investors to navigate market cycles, optimize financing, and plan for generational transfers without the drag of immediate tax liabilities. The strategy demands precision—timing, documentation, and compliance are non-negotiable—but the rewards for those who master it are substantial. For the ultra-wealthy, a well-executed 1031 exchange isn’t just a financial tool; it’s a cornerstone of legacy building. Yet the landscape is evolving. IRS scrutiny of related-party transactions and state-level tax conformity are tightening the rules. HNWIs must adapt by working with specialized advisors, leveraging technology for due diligence, and staying ahead of legislative changes. The exchanges that succeed in the next decade will be those that balance tax efficiency with portfolio diversification, ensuring that deferral isn’t just a short-term gain but a long-term growth catalyst.Comprehensive FAQs
Q: Can a 1031 exchange be used for primary residences?
A: No. The IRS restricts 1031 exchanges to properties held for investment or business use. Primary residences, vacation homes used personally, and undeveloped land held for personal enjoyment do not qualify. However, if a primary residence was previously a rental property, it may qualify for a 1031 exchange if sold within two years of ceasing personal use (under the 2-year rule).
Q: What happens if the replacement property sells for less than the relinquished property?
A: The difference is treated as boot—a taxable gain. For example, if you sell a $5M property for $5M but the replacement property is worth $4.5M, the $500K difference is taxable immediately. To mitigate this, investors often finance the replacement property to reduce the cash contribution (and thus the boot). Some also structure exchanges to acquire properties with higher potential appreciation to offset the gap.
Q: Are there limits to how often an investor can perform a 1031 exchange?
A: No, there’s no IRS limit on the number of 1031 exchanges an investor can perform. However, each exchange must comply with the 45-day identification rule and 180-day closing deadline. The strategy is most effective when used to consolidate smaller properties into larger, more efficient assets or to diversify into higher-growth sectors (e.g., from retail to multifamily). Frequent exchanges without a clear strategic purpose may raise IRS scrutiny.
Q: Can a 1031 exchange be used to defer losses?
A: No. The 1031 exchange only defers gains, not losses. If a property is sold at a loss, the loss is recognized immediately and can be used to offset other capital gains or income (subject to IRS limits). The exchange process doesn’t alter the treatment of losses—it’s purely a tool for deferring recognized gains.
Q: What role do qualified intermediaries play in high-value exchanges?
A: Qualified intermediaries (QIs) are mandatory for 1031 exchanges. Their roles include: - Holding sale proceeds in a segregated account to prevent commingling with personal funds. - Facilitating the transfer of funds to purchase the replacement property. - Ensuring compliance with IRS timelines (45-day identification, 180-day closing). For high-net-worth investors, QIs also provide due diligence support, help structure complex transactions (like reverse exchanges), and assist with documentation to avoid audit triggers.
Q: How do state taxes affect 1031 exchanges?
A: State treatment of 1031 exchanges varies: - Conforming states (e.g., California, New York) follow federal rules, allowing deferral at both levels. - Non-conforming states (e.g., Texas, Florida) may not impose capital gains taxes on real estate sales, making federal deferral less critical. - Hybrid states (e.g., Massachusetts) may tax deferred gains if the replacement property is sold within a set period. HNWIs must consult state-specific tax attorneys to model how deferred gains will be treated upon eventual disposition, especially in states with recapture rules or basis adjustment limitations.
Q: Can a 1031 exchange be used to swap international properties?
A: No. The IRS restricts 1031 exchanges to U.S. real property. Exchanges involving foreign properties are not eligible for tax deferral under Section 1031. However, some investors use foreign investment entities (FIEs) or offshore trusts to hold international real estate, but these structures introduce complex tax and legal considerations (e.g., FATCA compliance, PFIC rules). For U.S. investors, domestic exchanges remain the only viable option.
Q: What’s the most common mistake HNWIs make with 1031 exchanges?
A: Underestimating the 45-day identification window. Many investors assume they have more time to find a replacement property, only to realize too late that they’ve missed the deadline. Other common errors include: - Failing to use a qualified intermediary, which voids the exchange. - Taking constructive receipt of funds (e.g., depositing sale proceeds into a personal account before the exchange completes). - Ignoring state tax implications, leading to unexpected liabilities upon sale of the replacement property. Elite investors mitigate these risks by pre-identifying properties, working with specialized QIs, and conducting tax modeling before executing the exchange.
