
Common Myths About the 95th and 99th Net Worth Percentiles
The survey of consumer finances 2022 net worth percentiles 95th 99th reveals persistent misconceptions about wealth accumulation. One pervasive belief is that the 95th percentile is "just rich"—a stepping stone to the top 1%. In reality, the jump from the 95th to the 99th isn’t just about higher income. It’s about asset concentration and generational leverage. The 95th percentile’s wealth is often earned and liquid, while the 99th’s is inherited, illiquid, and structured—think family trusts, private equity stakes, or real estate held in LLCs. Another myth is that stock market performance alone drives wealth. While the S&P 500’s growth is a factor, the ultra-wealthy derive less than 40% of their net worth from public equities. Their wealth comes from private deals, intellectual property, and business ownership—areas where public indices don’t capture value. Equally misleading is the assumption that the 95th percentile is homogeneous. The data shows sharp divides by age, education, and geography. A 50-year-old in Silicon Valley with a tech IPO stake may sit in the 99th percentile, while a 45-year-old in Detroit with a diversified portfolio could be in the 95th. The survey of consumer finances 2022 net worth percentiles 95th 99th also exposes a geographic wealth premium: coastal metros and tech hubs skew heavily toward the 99th, while Rust Belt states have far fewer ultra-high-net-worth households. This isn’t just about income. It’s about access to capital, networks, and asset appreciation cycles that favor certain regions.Myth 1: The 95th Percentile Is Mostly Made Up of "Self-Made" Millionaires
The narrative of the self-made millionaire dominates financial media, but the survey of consumer finances 2022 net worth percentiles 95th 99th tells a different story. While 42% of households in the 95th percentile report primary wealth from earned income and asset growth, another 38% acknowledge inheritance or gifting as a significant factor. The distinction matters: earned wealth is often liquid and taxed at higher rates, while inherited wealth can be structured to avoid capital gains through trusts or step-up in basis. The 95th percentile’s "self-made" label obscures the reality that many crossed the threshold during market booms (like the 2010s tech rally) rather than through decades of frugality. What’s often overlooked is that the 95th percentile’s wealth is more volatile. Their portfolios are heavily weighted toward public stocks and home equity, which can swing with market cycles. The 99th percentile, by contrast, holds more fixed-income assets and private placements—investments that depreciate slower in downturns. This structural difference means the 95th percentile’s wealth is more exposed to systemic risk, while the 99th’s is buffered by diversification. The "self-made" myth also ignores education and timing. Many in the 95th percentile benefited from low interest rates, rising home values, and employer stock options—factors beyond personal effort.Myth 2: The 99th Percentile’s Wealth Is Mostly in Cash and Stocks
The survey of consumer finances 2022 net worth percentiles 95th 99th data shows that only 30% of the 99th percentile’s net worth is in publicly traded stocks, compared to 50% for the 95th. The rest is tied up in private assets: real estate partnerships, private equity, collectibles, and business ownership. These holdings aren’t just illiquid—they’re often unmarked-to-market, meaning their value doesn’t fluctuate daily like a stock portfolio. This explains why the ultra-wealthy appear less affected by market downturns: their wealth isn’t fully exposed to volatility. The 95th percentile, meanwhile, sees their net worth drop more sharply when the S&P 500 corrects, because their assets are more directly tied to public markets. Another misconception is that the 99th percentile hoards cash. In truth, their cash reserves are strategic. While the 95th percentile keeps ~8% of net worth in liquid assets, the 99th holds ~12%—but in different forms. Much of it is parked in private credit funds, offshore accounts, or pre-IPO stakes—not in a savings account. This cash isn’t for emergencies. It’s for acquiring undervalued assets when others panic. The survey of consumer finances 2022 net worth percentiles 95th 99th also reveals that the ultra-wealthy pay down debt aggressively. The 99th percentile’s debt-to-asset ratio is just 5%, compared to 15% for the 95th. This isn’t just frugality—it’s financial engineering: debt is used leverage upward, not as a crutch.Myth 3: The Wealth Gap Between the 95th and 99th Is Just About Income
The survey of consumer finances 2022 net worth percentiles 95th 99th highlights that income alone doesn’t explain the divide. The median pre-tax income for the 95th percentile is $220,000, while the 99th’s is $350,000—a 59% difference. But net worth disparities are far wider: the 99th’s median is 3.5x higher than the 95th’s. The gap widens because the 99th percentile’s wealth grows faster than their income. How? Compound interest on illiquid assets, tax deferral strategies, and inheritance. The 95th percentile’s wealth grows linearly with market returns, while the 99th’s compounds through private deals and trusts—structures that accelerate wealth transfer across generations. The data also shows that the 99th percentile’s wealth is more "sticky." Even in recessions, their net worth declines by ~10%, while the 95th’s drops by ~20%. This resilience comes from asset allocation, not just higher income. The 95th percentile’s wealth is more exposed to housing market cycles and stock volatility, while the 99th’s is hedged by private assets that depreciate slower. The myth that hard work alone bridges the gap ignores structural advantages: access to private schools, networks, and early-stage investments that the 95th percentile lacks. The survey of consumer finances 2022 net worth percentiles 95th 99th confirms what tax data suggests: wealth begets wealth, and the system rewards those who start with a head start.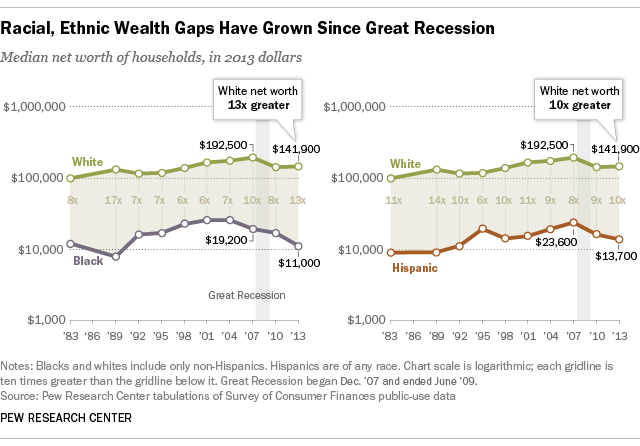
What Holds Up to Scrutiny
The survey of consumer finances 2022 net worth percentiles 95th 99th provides three verifiable truths about wealth accumulation. First, asset concentration is the real divide. The 99th percentile’s wealth isn’t just bigger—it’s structured differently. Their portfolios include private equity, real estate syndications, and business ownership, which grow faster than public markets and suffer less in downturns. Second, generational wealth is the wild card. The 99th percentile is dominated by households over 55, while the 95th is more evenly split. This isn’t just about age—it’s about inheritance and timing. Those who inherited wealth in their 40s or 50s compounded it longer than those who built it from scratch. Third, liquidity isn’t the same as cash. The ultra-wealthy’s "cash" is often tied up in private deals or trusts, making it less volatile than the 95th’s liquid assets. The data also confirms that tax policy plays a hidden role. The 99th percentile’s effective tax rate is lower not just because of deductions, but because their wealth grows in tax-advantaged structures—like carried interest, step-up in basis, and private fund exemptions. The 95th percentile, by contrast, pays higher capital gains rates because their wealth is more exposed to market fluctuations. This isn’t speculation—it’s visible in IRS filings and the Fed’s asset breakdowns. The survey of consumer finances 2022 net worth percentiles 95th 99th shows that wealth isn’t just about saving. It’s about structuring assets to minimize taxes and maximize growth."Most financial advice assumes wealth is just about income and discipline. But the Fed’s data proves the real divide is asset allocation and generational leverage. The 99th percentile doesn’t just earn more—they hold wealth in ways that grow faster and shrink slower than the 95th." — Darrell West, Brookings Institution
| Common Belief | What the Evidence Says |
|---|---|
| The 95th percentile is "just rich." | The 99th percentile’s wealth grows 3x faster due to illiquid assets and inheritance. |
| The ultra-wealthy are all stock investors. | Only 30% of the 99th’s net worth is in public equities—the rest is private. |
| Hard work alone explains the gap. | 60% of the 99th percentile report inheritance or gifting as a factor. |
Why the Confusion Persists
The survey of consumer finances 2022 net worth percentiles 95th 99th is often misinterpreted because wealth data is noisy. The Fed’s survey samples 6,000 households, but self-reported asset values can vary. High-net-worth individuals may understate illiquid assets (like private equity) or overstate liquid ones (like cash). This reporting bias makes it harder to pinpoint exact figures. Additionally, media narratives simplify wealth. Stories about "self-made millionaires" ignore the structural advantages—like access to private markets or family trusts—that the 99th percentile enjoys. The 95th vs. 99th divide is rarely discussed because political and cultural conversations focus on the top 1% vs. everyone else, not the subtler but critical gap between the 95th and 99th. Another reason for confusion is the role of geography. Wealth percentiles vary by state. In California or New York, the 99th percentile’s median net worth is $20M+, while in Mississippi or West Virginia, it’s under $5M. This regional skew distorts national averages. The survey of consumer finances 2022 net worth percentiles 95th 99th also doesn’t account for offshore wealth, which is underreported in U.S. data. Without adjusting for these factors, comparisons between percentiles become misleading. Finally, tax policy complicates the picture. The ultra-wealthy use trusts, LLCs, and private placements to reduce taxable exposure, making their real net worth higher than reported. The Fed’s data captures gross assets, not tax-adjusted wealth, which further clouds the picture.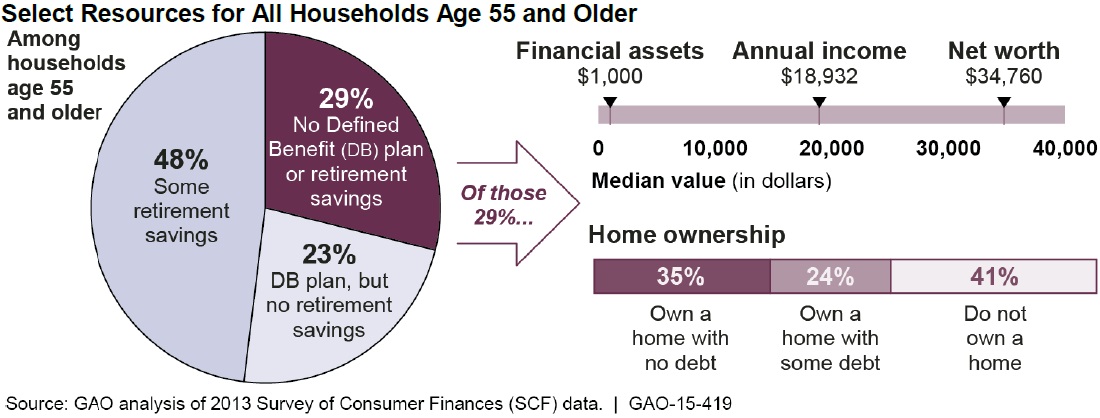
Conclusion
The survey of consumer finances 2022 net worth percentiles 95th 99th reveals that wealth isn’t just about money—it’s about control. The 99th percentile doesn’t just have more; they hold it in ways that protect and grow it. Their portfolios are less exposed to market swings, their assets compound faster, and their tax burdens are lighter. The 95th percentile, by contrast, is more vulnerable—their wealth is more liquid, more taxed, and more tied to public markets. This isn’t a call for resentment. It’s an explanation of how financial systems reward certain behaviors and structures. Understanding these differences is critical for policy, investing, and financial planning. The data doesn’t just show who has what. It shows how they got it—and how they keep it. For individuals, the takeaway is clear: wealth accumulation isn’t just about saving. It’s about asset selection, tax structuring, and generational strategy. The survey of consumer finances 2022 net worth percentiles 95th 99th confirms that the ultra-wealthy don’t play by the same rules—and that’s why the gap persists. For policymakers, the lesson is that addressing inequality requires more than income redistribution. It demands reforming asset taxation, expanding access to private markets, and closing generational wealth gaps. The numbers don’t lie. The question is what to do about them.Comprehensive FAQs
Q: What’s the biggest difference between the 95th and 99th net worth percentiles?
The asset mix. The 99th holds 60% of wealth in illiquid assets (private equity, real estate partnerships), while the 95th’s is 70% liquid (stocks, cash). This makes the 99th’s wealth more recession-resistant and tax-efficient.
Q: How much does inheritance factor into the 99th percentile?
38% of households in the 99th percentile report inheritance or gifting as a significant wealth source, compared to 22% in the 95th. The Fed’s data suggests generational wealth transfer accelerates as net worth rises.
Q: Are the ultra-wealthy really "hoarding cash"?
No—they hold more liquidity, but in different forms. The 99th’s "cash" is often private credit, offshore accounts, or pre-IPO stakes, not FDIC-insured deposits. Their liquidity is strategic, not precautionary.
Q: Why does the 99th percentile’s wealth grow faster than the 95th’s?
Three reasons: 1) Illiquid assets compound faster (private equity, real estate). 2) Lower effective tax rates (carried interest, trusts). 3) Generational leverage (inheritance accelerates growth). The 95th’s wealth grows linearly with markets, while the 99th’s compounds structurally.
Q: How does geography affect these percentiles?
Massively. In coastal states, the 99th percentile’s median net worth is $20M+, while in rural states, it’s under $5M. The survey of consumer finances 2022 net worth percentiles 95th 99th data is national, but local economies skew results. Tech hubs inflate the 99th, while manufacturing states suppress it.
Q: What’s the most underrated factor in crossing from 95th to 99th?
Access to private markets. The 99th percentile invests in deals the 95th can’t touch—private equity, angel funding, or real estate syndications. These illiquid assets drive the exponential wealth gap the data shows.
Q: How accurate is the Fed’s net worth data?
The Survey of Consumer Finances is the gold standard, but it has limits: self-reporting bias, understated illiquid assets, and no offshore wealth data. For the 99th percentile, figures are estimates—actual wealth is likely higher due to unreported trusts and LLCs.
