
Where It All Began
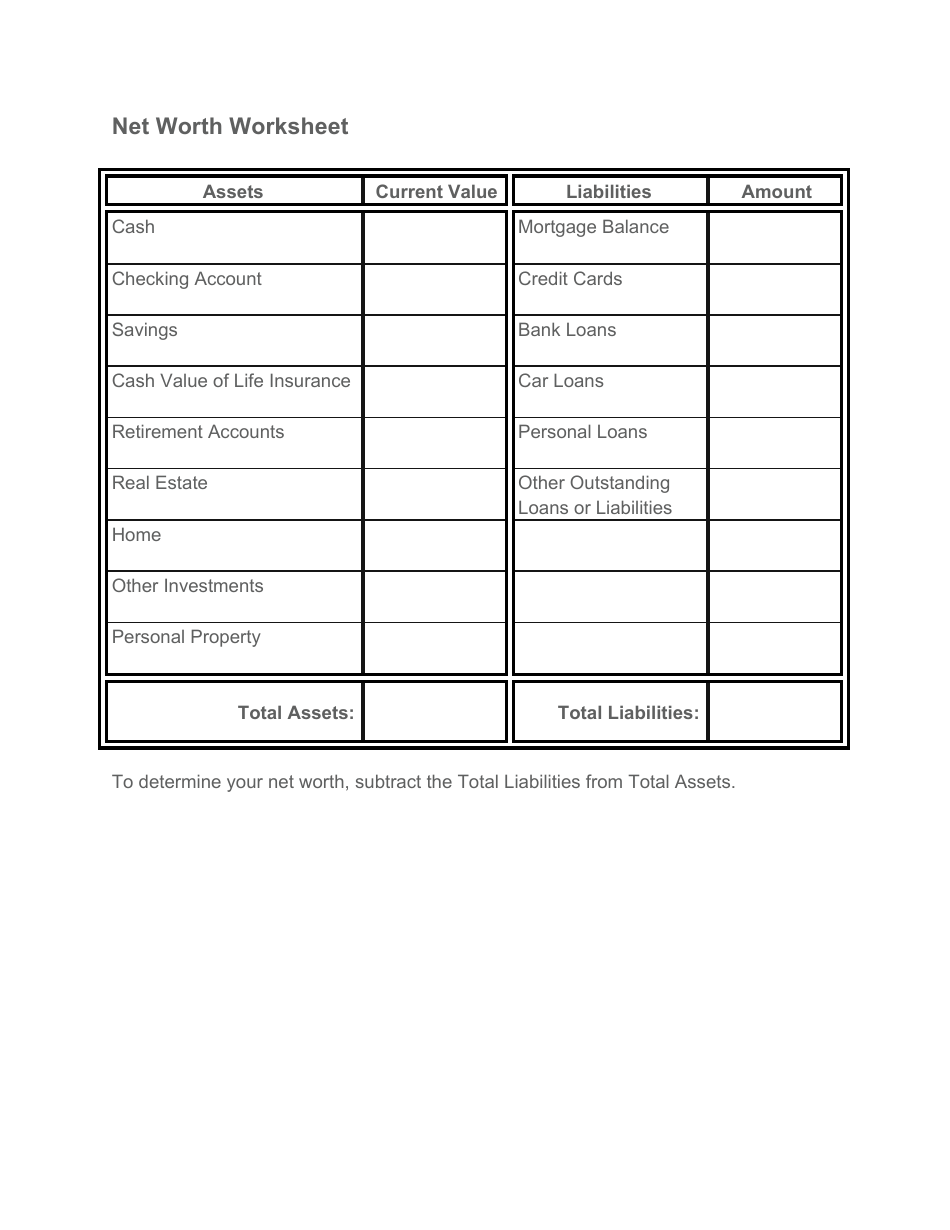
The origins of the statement of financial net worth worksheet lie in the ledger books of Renaissance merchants. These early versions were crude but functional: columns for assets (gold coins, spices, ships) and liabilities (debts to Venetian bankers, unpaid sailors). The key innovation wasn’t the format but the idea that wealth could be distilled into a single number. For a merchant in 15th-century Florence, this number determined whether he could afford another voyage—or whether his creditors would seize his warehouse. The transition from handwritten ledgers to printed worksheets happened gradually. By the 1850s, American accountants began publishing templates in trade journals, tailored to farmers, shopkeepers, and the emerging middle class. These early financial net worth worksheets were often one-page documents with hand-drawn tables, designed to be filled out annually. The language was stark: "List all property," "Subtract debts," "Result = Net Worth." There was no room for ambiguity. The worksheet wasn’t just a record; it was a mirror held up to financial reality.The Early Signs
The real turning point came when the statement of financial net worth moved beyond merchants and landowners. In the 1880s, American universities began teaching basic accounting, and textbooks included simplified net worth tracking worksheets for students. This democratization was critical. For the first time, a clerk in a Chicago factory or a schoolteacher in rural Iowa could calculate their financial standing using the same principles as a railroad tycoon. The worksheets of this era reveal another shift: the introduction of categories. Early versions lumped everything into "Assets" and "Liabilities," but by the 1920s, templates started breaking down assets into liquid (cash, stocks) and illiquid (real estate, farm equipment). This granularity reflected a changing economy where paper wealth—stocks, bonds—was becoming as valuable as physical property. The financial net worth worksheet was evolving from a survival tool into a strategic instrument.The Turning Point
The Great Depression forced the statement of financial net worth into the mainstream. As banks failed and savings vanished, Americans realized they couldn’t rely on verbal promises or handshake deals. The Works Progress Administration (WPA) distributed millions of financial literacy pamphlets, many featuring net worth calculation worksheets as their centerpiece. These documents weren’t just for the wealthy; they were for anyone who wanted to avoid the fate of those who lost everything. The post-war boom cemented the worksheet’s place in American life. The rise of homeownership, employer-sponsored pensions, and consumer credit created a new complexity. A 1950s financial net worth tracker might include columns for a house mortgage, a car loan, and a newly popularized "charge account" at Sears. The worksheet had to adapt—or risk becoming obsolete. By the 1970s, software companies began digitizing these templates, though the core structure remained unchanged: assets minus liabilities equals net worth."Before the worksheet, people lived in financial fog. After, they could see the numbers—and that changed everything." — John Bogle, founder of Vanguard and pioneer of index investing
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1850–1900 | Printed financial net worth worksheets appear in accounting manuals, targeting merchants and farmers. Categories are broad (e.g., "Property," "Debts"). |
| 1920–1940 | Worksheets refine categories (liquid vs. illiquid assets) as stock markets grow. Used by middle-class families tracking home equity and savings accounts. |
| 1950–1970 | Post-war prosperity adds new liabilities (mortgages, car loans) to net worth statements. Worksheets become more detailed, with space for "Retirement Savings." |
| 1980–2000 | Software like Quicken introduces digital financial net worth trackers. Worksheets now include investment portfolios, student loans, and credit card debt. |
| 2010–Present | Cloud-based tools (Mint, Personal Capital) automate net worth calculations, but the core worksheet remains a manual exercise for precision. Cryptocurrency and side hustles add new asset classes. |
Lessons From the Journey
- The worksheet’s power lies in its simplicity. Despite digital tools, the core formula—assets minus liabilities—hasn’t changed since the 18th century. Complexity is the enemy of clarity.
- It forces honesty. Early adopters like Samuel Adams used it to confront uncomfortable truths (e.g., "I owe the miller 50 pounds"). Modern versions do the same.
- Economic crises accelerate adoption. The Depression, 2008, and COVID-19 all saw surges in people creating financial net worth statements—not as a luxury, but as a necessity.
- It’s a tool, not a judgment. A negative net worth isn’t failure; it’s data. The worksheet’s value is in tracking trends, not assigning moral weight.
Where Things Stand Today
Today, the statement of financial net worth worksheet exists in three forms: the analog spreadsheet (still used by purists), the digital tracker (Mint, YNAB), and the hybrid approach (manual review of automated data). The rise of gig economy income, cryptocurrency, and high-interest debt has made the worksheet more complex—but also more necessary. A freelancer’s net worth tracker might include columns for PayPal balances, NFT holdings, and equipment depreciation, none of which fit neatly into a 1950s template. Institutions have caught on too. Wealth managers now use customized financial net worth worksheets to assess client portfolios, while nonprofits distribute simplified versions to low-income families. The worksheet has become a bridge between personal finance and systemic change. For example, the Federal Reserve’s Report on the Economic Well-Being of U.S. Households relies on net worth data derived from these very tools to gauge national financial health.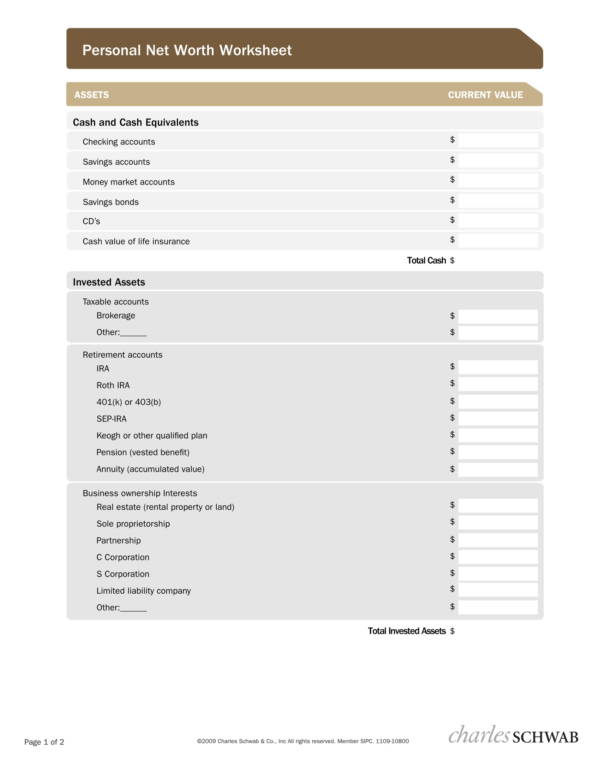
Conclusion
The statement of financial net worth worksheet began as a merchant’s ledger and has become the quiet backbone of modern finance. Its endurance speaks to a fundamental truth: numbers don’t lie, but they do reveal. Whether you’re a farmer in 18th-century Massachusetts or a remote worker in 2024, the worksheet’s purpose remains the same—to turn the chaos of money into a single, actionable number. The next evolution may lie in AI-driven insights, but the worksheet itself won’t disappear. Why? Because at its core, it’s not about technology. It’s about the moment you sit down, add up your assets, subtract your debts, and finally see—clearly—where you stand.Comprehensive FAQs
Q: Do I need a statement of financial net worth worksheet if I use budgeting apps?
Budgeting apps track cash flow, but a financial net worth worksheet gives you the big picture—your total wealth over time. Apps can automate calculations, but manually reviewing your net worth (even quarterly) ensures accuracy, especially with illiquid assets like real estate or private business stakes.
Q: How often should I update my net worth statement?
Ideally, quarterly. Market fluctuations, large purchases (e.g., a car), or debt repayments can shift your net worth significantly. If your assets or liabilities are stable (e.g., no trading, fixed mortgage), annual updates may suffice—but consistency matters more than frequency.
Q: Can a financial net worth worksheet help with debt management?
Absolutely. By listing all liabilities (credit cards, student loans, mortgages), you’ll see which debts are dragging down your net worth. The worksheet also highlights high-interest debts—targeting these first can accelerate wealth growth.
Q: Are there industry-standard templates for net worth tracking worksheets?
No strict standard, but reputable sources like the Financial Industry Regulatory Authority (FINRA) and the IRS provide guidelines. Many financial advisors use a simple two-column format: one for assets (cash, investments, property) and one for liabilities (debts, loans). Templates from Mint or Personal Capital also align with best practices.
Q: What’s the difference between a net worth statement and a balance sheet?
A financial net worth worksheet is a personal balance sheet—both list assets and liabilities—but the net worth statement focuses on the net result (assets minus liabilities). A corporate balance sheet includes additional line items (revenue, expenses) irrelevant to individuals. Think of the net worth statement as your financial report card.
Q: How do I handle assets like cryptocurrency or side hustles in my net worth tracker?
Treat them like any other asset: record their current value (use CoinMarketCap for crypto, actual earnings for side gigs) under "Other Assets." For volatile assets (e.g., crypto), update the value monthly. Side hustle income should be added to assets only after taxes are accounted for—otherwise, you’ll overstate your net worth.
Q: Is a negative net worth a red flag?
Not necessarily. Many people—especially young adults or those with student loans—start with a negative net worth. The red flag isn’t the number itself but the trend. If your net worth is improving (even slowly), you’re on the right track. If it’s stagnant or worsening, it’s time to reassess spending, debt repayment, or income strategies.
