The Complete Overview of What Is the Wealth Distribution in America
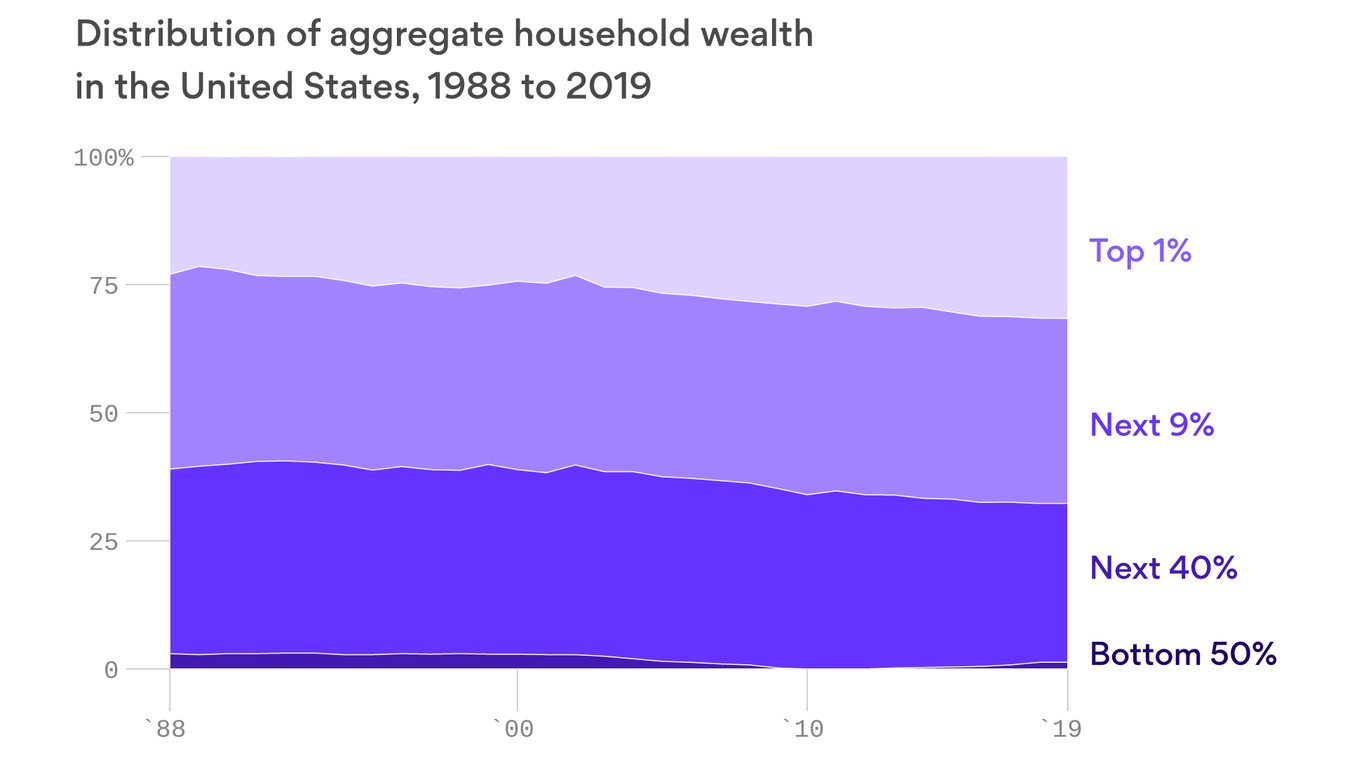
Wealth distribution in the U.S. operates on two parallel tracks: one for those who own assets (stocks, real estate, businesses) and another for those who rely on labor income. The gap between these tracks has never been wider. Data from the Federal Reserve’s Survey of Consumer Finances shows that in 2022, the average net worth of the top 10% was $5.2 million, while the bottom 50% averaged just $138,000. The median—a more reliable measure—paints an even grimmer picture: the middle 60% of Americans hold less than 25% of total wealth. What is the wealth distribution in America also exposes a racial wealth divide that persists despite economic growth. The median white household holds $188,200 in wealth, compared to $24,100 for Black households and $36,100 for Hispanic households. This gap isn’t just about income; it’s about generational wealth accumulation, redlining history, and the compounding effects of asset ownership. Closing it would require systemic changes far beyond wage adjustments.Historical Background and Evolution
The modern wealth distribution in America took shape in the late 20th century, but its roots stretch back to the Gilded Age. After World War II, policies like the GI Bill and progressive taxation temporarily narrowed inequality. By the 1970s, however, deregulation, stagnant wages, and the rise of financial speculation began to reverse those gains. The Tax Reform Act of 1986—which slashed capital gains taxes—accelerated wealth concentration, as asset appreciation became the primary driver of fortune-building. What is the wealth distribution in America today is a direct legacy of these choices. The 1990s tech boom and 2000s housing bubble created temporary illusions of shared prosperity, but both collapsed into crises that disproportionately harmed the middle class. The Great Recession of 2008 wiped out $16.5 trillion in household wealth, yet the top 1% recovered within five years. For everyone else, recovery took a decade—or never came at all.Core Mechanisms: How It Works
Wealth isn’t just money in the bank; it’s a self-reinforcing system. The ultra-rich deploy capital in ways that generate more capital: private equity stakes, venture capital, and real estate holdings that appreciate independently of labor markets. Meanwhile, the majority of Americans depend on wages, which have grown just 13% in real terms since 1964, while corporate profits have soared. What is the wealth distribution in America hinges on three pillars: 1. Asset ownership: Stocks, homes, and businesses appreciate over time, creating generational wealth. Those without these assets fall further behind. 2. Tax policy: Lower capital gains rates and estate tax exemptions (now at $13.61 million per individual) ensure wealth persists across generations. 3. Wage suppression: The decline of unions and the rise of gig economy jobs have eroded collective bargaining power, keeping wages flat while corporate profits rise.Key Benefits and Crucial Impact
For the top 1%, concentrated wealth means unparalleled influence—over politics, media, and even scientific research. The top 0.001% (about 1,400 families) control more wealth than the bottom 90% combined. This isn’t just about luxury yachts; it’s about shaping the rules of the economy. For the rest, the impact is stagnation: 40% of Americans can’t cover a $400 emergency without borrowing. What is the wealth distribution in America forces a reckoning: Is this inequality a feature or a bug of capitalism? Some argue it’s the price of innovation; others see it as evidence of a system rigged against mobility."Wealth inequality is the most critical economic issue of our time—not because the rich are getting richer, but because the rest are getting left behind." — Thomas Piketty, Capital in the Twenty-First Century
Major Advantages
- Political leverage: The top 1% funds campaigns, lobbies for tax cuts, and shapes regulatory environments to protect asset values.
- Intergenerational transfer: Wealth compounds through trusts, private schools, and real estate, ensuring privilege persists.
- Financial resilience: Asset owners weather recessions better; wage earners face permanent setbacks.
- Global influence: Ultra-high-net-worth individuals (UHNWIs) control cross-border investments, shaping markets beyond national borders.

Comparative Analysis
| Metric | United States (2023) | European Average |
|---|---|---|
| Top 1% wealth share | ~30% | ~20% |
| Median net worth (adjusted) | $138,000 | $180,000 (Germany) |
| Estate tax exemption | $13.61M per individual | $2M–$5M (varies by country) |
Future Trends and Innovations
The wealth gap isn’t closing; it’s accelerating. Automation and AI threaten to displace mid-skilled jobs, pushing more workers into precarious gig economies. Meanwhile, the top 0.1% are investing in emerging sectors like biotech and renewable energy, ensuring their fortunes grow even as traditional industries decline. What is the wealth distribution in America in 2030 may look like this: a liquidation economy, where the ultra-rich monetize assets (homes, art, even data) while the middle class struggles with debt. Policy shifts—like higher capital gains taxes or wealth taxes—could alter this trajectory, but political will remains the biggest obstacle.
Conclusion
The data on what is the wealth distribution in America isn’t just dry statistics—it’s a warning. A society where the top 1% own more than the bottom 90% combined is one where democracy, mobility, and stability are at risk. The question isn’t whether to address inequality; it’s how urgently. Reforms could include expanded inheritance taxes, stronger unions, and universal basic services—but none will work without confronting the structural forces that created this divide. The alternative? A future where wealth isn’t just concentrated, but hereditary.Comprehensive FAQs
Q: How does the U.S. wealth gap compare to other developed nations?
The U.S. has the most unequal wealth distribution among advanced economies. While countries like Sweden and Denmark use progressive taxation and welfare to narrow gaps, America’s reliance on asset-based wealth accumulation widens disparities.
Q: What role does homeownership play in wealth inequality?
Homeownership is the single largest driver of wealth for middle-class Americans. However, racial disparities in mortgage access (historically through redlining) and rising housing costs mean that white households are 10x more likely to own homes than Black households.
Q: Do high-income earners always become wealthy?
No. Income and wealth are distinct. A doctor earning $300K may have no savings due to student debt, while a CEO with stock options could be multi-millionaire. Wealth requires asset accumulation, not just high earnings.
Q: How does student debt affect wealth distribution?
Total student debt exceeds $1.7 trillion, suppressing homeownership and entrepreneurship for younger generations. Borrowers in the bottom 40% of the wealth distribution are less likely to own homes than their non-debted peers.
Q: Can wealth taxes reduce inequality?
Historically, yes. The 1930s–1970s estate tax (before Reagan-era cuts) reduced dynastic wealth. Modern proposals (e.g., a 2% tax on fortunes over $50M) could raise $300B annually, but political resistance remains fierce.
Q: How does corporate stock ownership contribute to inequality?
The top 10% of Americans own 80% of all corporate stock. Since the 1980s, 401(k) plans have shifted retirement savings into the stock market, benefiting those already invested—while wage earners lack access.
Q: What’s the relationship between wealth and political power?
The top 0.01% spend $1B+ annually on lobbying and campaigns. A 2020 study found that policy changes favoring the rich outnumber those helping the poor by 4:1—directly tied to wealth-driven political influence.
Q: Are there any bright spots in wealth distribution?
Yes, but limited. Employee stock ownership plans (ESOPs) and worker cooperatives (e.g., Mondragon Corporation in Spain) show how alternative models can distribute wealth. However, these remain niche in the U.S.
