5 Things Worth Knowing About Percentage of Wealth by Generation
Understanding the wealth concentration by age cohort requires looking beyond income statistics. While paychecks tell part of the story, net worth—the sum of assets minus debts—paints a far more revealing picture. The gap isn’t just about who earns more; it’s about who owns assets that appreciate, who inherits, and who gets locked out of markets entirely. Here are five critical insights that explain why the numbers matter—and why they’re getting worse.1. The Silent Transfer: How Boomers and Older Generations Hold the Majority of Wealth
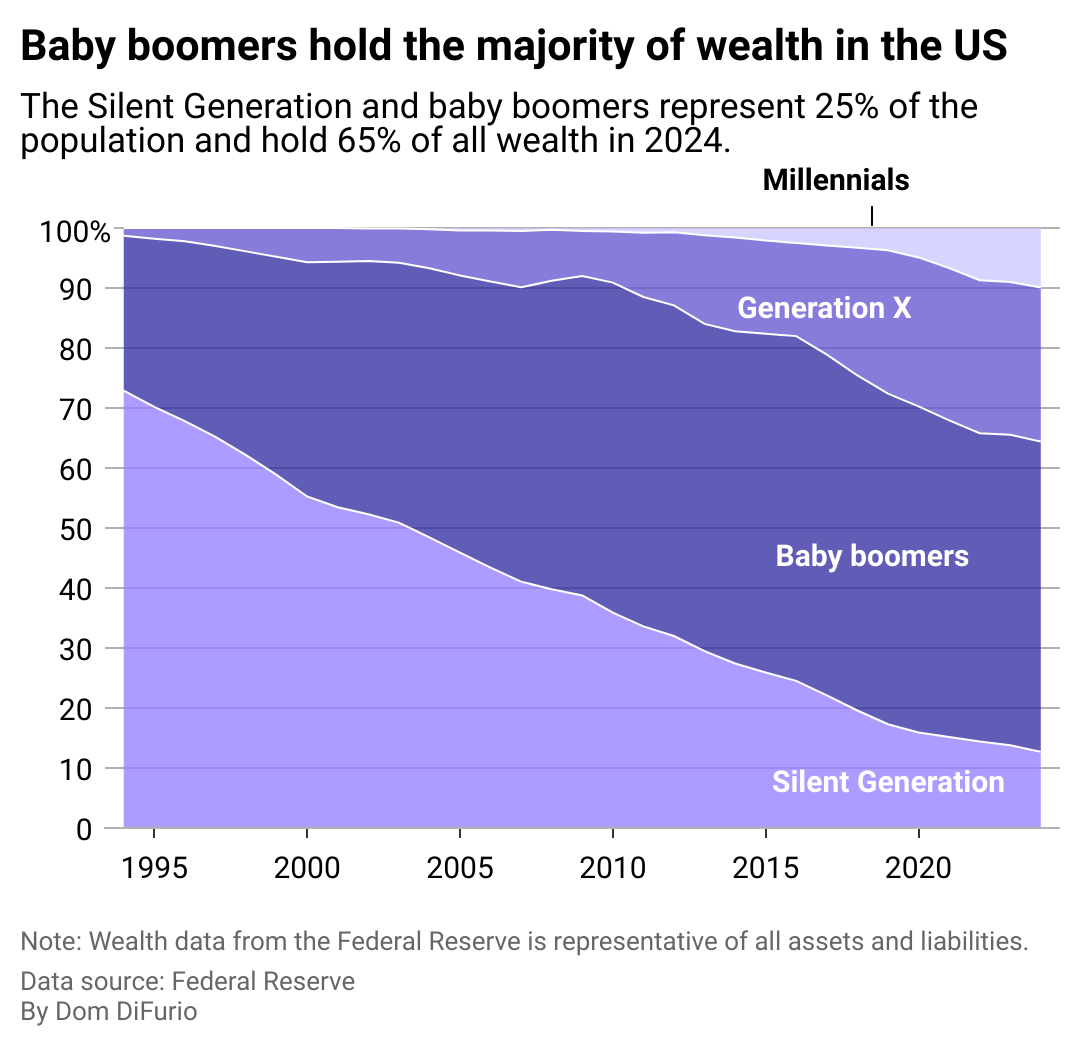
The Federal Reserve’s data leaves little room for ambiguity: households headed by those 65 and older hold roughly 53% of all U.S. wealth, while millennials—now the largest generation in the workforce—control just 7%. The disparity isn’t new, but its severity has accelerated. By 2023, the median net worth of a household led by someone 65+ was estimated at $288,000, compared to $75,000 for millennials. The gap widens further when considering racial and ethnic divides; white households in that age group hold nearly 90% of the wealth of their Black and Hispanic counterparts. This isn’t just about savings habits. It’s about asset accumulation over decades. Older generations benefited from the post-WWII housing boom, low-interest-rate environments that inflated home values, and the untaxed appreciation of stocks held in retirement accounts. Meanwhile, younger generations entered the market during the 2008 crash, the student debt crisis, and a period of stagnant wage growth—factors that collectively slashed their ability to build wealth at the same pace.2. Inheritance as the Ultimate Equalizer—Or Lack Thereof
The myth of meritocracy crumbles when examining intergenerational wealth transfer. Studies suggest that inheritance accounts for roughly 20% of total U.S. wealth, but the distribution is anything but equal. The top 1% of estates—those worth over $10 million—represent nearly half of all inheritance, while the bottom 90% receive almost nothing. For millennials, the chance of inheriting enough to meaningfully alter their financial trajectory is slim; only about 1 in 10 will receive any bequest, and the average inheritance hovers around $64,000—barely enough to cover a down payment in many markets. What’s more, inheritance isn’t just about money; it’s about access to networks, education, and opportunity. A child born into a family with generational wealth is far more likely to attend elite universities, secure unpaid internships that lead to jobs, or inherit a business. The wealth gap by generation thus becomes a knowledge gap, reinforcing class boundaries that stretch back centuries.3. The Student Debt Albatross: How Younger Generations Are Financially Handicapped
No discussion of wealth disparities across generations is complete without addressing the student debt crisis. As of 2023, Americans owed over $1.7 trillion in student loans, with the average borrower owing $37,000—an amount that can take decades to repay at current interest rates. For millennials, this debt doesn’t just delay homeownership; it prevents wealth accumulation entirely. A 2022 Brookings Institution report found that households with student debt have 50% less wealth than those without, even when controlling for income. The impact is generational. While older cohorts could invest their earnings in appreciating assets like stocks or real estate, younger workers are forced to allocate a larger share of their income to debt service. This isn’t just a personal financial setback—it’s a structural barrier to entering the wealth-building pipeline. Without the liquidity to save, invest, or even afford a home, millennials and Gen Z are being priced out of the very markets that could have closed the wealth divide by generation.4. The Homeownership Crisis: How Younger Generations Are Renting for Life
Homeownership remains the single most effective tool for building wealth in the U.S., yet the percentage of young adults who own homes has plummeted to historic lows. In 2023, just 37% of millennials owned a home, down from 47% for Gen X at the same age. The reasons are clear: housing costs now consume 35% of the median young worker’s income, up from 25% in the 1980s. Meanwhile, home prices have risen faster than wages for decades, creating a feedback loop where each generation starts with a larger financial deficit. The consequences are stark. A 2021 Urban Institute study estimated that millennials will accumulate $1.4 trillion less wealth by age 60 than their parents’ generation due to housing costs alone. For Gen Z, the outlook is even grimmer—many are entering adulthood in a market where rental prices have outpaced wage growth, making homeownership a distant dream. This isn’t just a housing crisis; it’s a wealth accumulation crisis, where the foundation of financial security is being eroded for an entire generation.5. Policy and Taxation: How the System Favors the Old
The wealth concentration by generation isn’t an accident—it’s the result of deliberate policy choices. Since the 1980s, capital gains taxes have been slashed repeatedly, benefiting older investors who hold the majority of assets. In 2023, the top marginal rate for long-term capital gains was 20%, down from 35% in the 1990s. Meanwhile, estate taxes—designed to prevent dynastic wealth accumulation—have been weakened to the point where only 0.2% of estates pay any tax at all. Then there’s the Social Security wealth transfer. Older Americans receive $1.2 trillion annually in benefits, while younger workers contribute through payroll taxes but may never see returns at the same level due to demographic shifts. Add to this the lack of wealth-building tools for low- and middle-income earners—such as limited access to employer-sponsored retirement plans or financial literacy education—and the system becomes a machine designed to concentrate advantage in the hands of those who already have it.
How These Facts Connect
The data on wealth distribution by generation doesn’t just show a gap—it reveals a self-reinforcing cycle of advantage and disadvantage. Older generations, having benefited from decades of asset appreciation, low taxes on wealth, and inheritance, now control the majority of financial resources. Younger cohorts, burdened by student debt, unaffordable housing, and stagnant wages, are left scrambling to enter the wealth-building pipeline—often failing. The result is a two-tiered economy, where one generation’s security is built on another’s exclusion. This isn’t a story of individual failure; it’s a story of structural design. The policies that allowed the top 10% of older households to accumulate wealth—tax cuts, deregulation, and weak inheritance taxes—were sold as pro-growth measures. Yet their true effect has been to entrench generational inequality, creating a system where financial mobility is a privilege, not a right. The table below compares the key drivers of this divide:| Factor | Older Generations (65+) | Younger Generations (Millennials/Gen Z) |
|---|---|---|
| Asset Ownership | Control 53% of U.S. wealth; homeownership rates near 80% | Control 7% of wealth; homeownership rates at 37% |
| Inheritance | Receive 90% of bequests; median inheritance ~$64K+ | Only 10% receive inheritance; average <$5K |
| Debt Burden | Low consumer debt; most debt is mortgage-based | Student debt averages $37K; housing costs eat 35% of income |
| Policy Benefits | Benefit from low capital gains taxes, weak estate taxes | Face higher payroll taxes, limited wealth-building tools |
Conclusion
The percentage of wealth by generation isn’t just a statistical curiosity—it’s a warning sign of a society at risk of fracturing along economic lines. The data shows that wealth isn’t just a measure of individual success; it’s a transferred legacy, passed down through inheritance, policy, and market access. For younger Americans, the message is unambiguous: the rules of the game are stacked against them. Without bold reforms—such as wealth taxes, stronger inheritance regulations, and policies that make homeownership and education affordable—the gap will only deepen, turning economic inequality into a permanent feature of American life. The challenge isn’t just fixing the numbers; it’s redesigning the system. That means challenging the notion that wealth accumulation is a zero-sum game, where one generation’s gain must come at another’s expense. It means recognizing that economic mobility isn’t a natural state—it’s a policy choice. And it means asking whether a society that allows such extreme concentration of wealth can still claim to be fair, or even functional.Comprehensive FAQs
Q: Why do older generations hold so much more wealth than younger ones?
The primary reasons are decades of asset appreciation (homes, stocks), lower tax burdens on capital gains and estates, and inheritance. Older cohorts also benefited from stronger labor unions, higher wages relative to costs, and policies that favored homeownership. Younger generations, meanwhile, entered the economy during crises (2008, student debt boom) and face higher costs for housing and education that erode savings potential.
Q: Can millennials and Gen Z ever close the wealth gap?
Closing the gap will require systemic changes, including wealth taxes on the ultra-rich, student debt relief, housing policy reforms (e.g., down payment assistance, zoning reforms), and stronger labor protections. Individually, younger generations can mitigate the gap through aggressive saving, side hustles, and investing early, but structural barriers—like unaffordable housing—make progress difficult without policy shifts.
Q: How does inheritance play into generational wealth inequality?
Inheritance is the great equalizer—or lack thereof. The top 1% of estates receive half of all bequests, while the bottom 90% get almost nothing. For millennials, the chance of inheriting enough to meaningfully boost wealth is low; the average inheritance is $64,000, often insufficient to buy a home or cover emergencies. Without inheritance, younger generations must rely on earned wealth, which is far harder to accumulate in today’s economy.
Q: Are there any bright spots in generational wealth trends?
Yes, but they’re niche and policy-dependent. Some progress has been made in student debt relief efforts (e.g., Biden’s partial forgiveness plans) and first-time homebuyer programs. Additionally, diversified investment tools (like index funds) and remote work opportunities have lowered costs for some young professionals. However, these gains are outpaced by broader economic trends, and without sustained policy support, they won’t reverse the long-term decline in wealth mobility.
Q: What’s the biggest misconception about generational wealth inequality?
The biggest myth is that wealth gaps are due to laziness or poor choices. The data shows that systemic factors—tax policy, housing costs, student debt, and inheritance—play far larger roles than individual behavior. For example, a millennial with a six-figure salary may still struggle to save due to high rent and student loans, while a boomer with the same income could retire comfortably thanks to home equity and 401(k) growth. The system is rigged, not the individuals.
