
The Complete Overview of Median Net Worth Black vs White
The median net worth Black vs white disparity is one of the most enduring and consequential economic divides in the U.S. It’s not a recent phenomenon but the result of centuries of unequal treatment, from chattel slavery to redlining to mass incarceration. While headlines often focus on income disparities, net worth—the total value of assets minus debts—reveals a deeper truth: wealth is inherited as much as earned. White families benefit from inherited wealth, home equity, and generational trusts at rates Black families simply cannot match. The data shows that by age 60, the median net worth for white households is roughly 10 times that of Black households, a gap that widens with each generation. What’s less discussed is how this divide plays out in everyday life. A Black family’s median net worth is often insufficient to weather a financial shock—whether a medical emergency, job loss, or housing crisis—without falling into debt or losing assets. Meanwhile, white families with comparable incomes can leverage their wealth to invest, start businesses, or pass down inheritances. The median net worth Black vs white gap isn’t just about money; it’s about economic resilience. It explains why Black homeownership rates remain 20 percentage points lower than white rates, why Black entrepreneurs face higher rejection rates for loans, and why Black families are more likely to live paycheck to paycheck despite working full-time jobs. The numbers tell a story of structural inequality. In 2021, the median net worth for white families was $188,200, while for Black families it was $24,100—a ratio of 7.8 to 1. Even when Black households earn the same income as white ones, their net worth remains significantly lower due to historical barriers like predatory lending, discriminatory housing policies, and wage suppression. The gap is narrower for younger cohorts but still stark: Black millennials have a median net worth of $8,500, compared to $65,000 for white millennials. This isn’t just a wealth gap; it’s a wealth inheritance gap, where one group starts the race with a head start no amount of individual effort can overcome.Historical Background and Evolution
The roots of the median net worth Black vs white divide stretch back to the 1600s, when slavery systematically stripped Black families of their labor, autonomy, and any possibility of wealth accumulation. Even after emancipation, Black Codes and Jim Crow laws enforced segregation and economic exclusion. The 1930s saw the creation of the Federal Housing Administration, which explicitly excluded Black families from mortgages—leading to redlining, where entire neighborhoods were denied access to credit. By the mid-20th century, white families were building generational wealth through homeownership, while Black families were locked out of the same opportunities. The civil rights era brought legal progress, but economic policies often undermined it. The War on Drugs and mass incarceration disproportionately targeted Black communities, stripping families of breadwinners and imposing collateral consequences like lost voting rights and employment barriers. Meanwhile, policies like the Home Mortgage Disclosure Act (1975) and Community Reinvestment Act (1977) were supposed to address discrimination—but enforcement remained weak. The result? By the 1990s, the median net worth Black vs white gap had widened to $8,000 for Black families vs $90,000 for white families, a disparity that only grew in the 21st century. Even today, Black families are three times more likely to be denied a mortgage application than white families with similar credit scores. The median net worth Black vs white gap isn’t a static number; it’s a moving target shaped by policy choices. The 2008 financial crisis, for example, wiped out $16 trillion in household wealth—but Black families lost 31% of their net worth, while white families lost just 16%. The recovery that followed didn’t bridge the gap; it widened it. Today, the median net worth Black vs white ratio remains one of the most persistent economic inequalities in the developed world, outpacing even gender-based wealth gaps.Core Mechanisms: How It Works
The median net worth Black vs white disparity isn’t accidental—it’s the result of three interlocking systems: asset exclusion, wage suppression, and punitive policies. First, asset exclusion prevents Black families from building wealth. Homeownership is the primary driver of wealth accumulation in the U.S., yet Black families face higher denial rates for mortgages and pay $1,000 more per year in interest due to discriminatory lending practices. Even when they buy homes, Black neighborhoods often have lower property values due to historical redlining, meaning equity builds more slowly. Second, wage suppression ensures Black workers earn less for the same work. In 2022, Black workers earned $15.27 per hour on average, compared to $19.13 for white workers—a gap that persists even for college graduates. Over a lifetime, this translates to hundreds of thousands in lost earnings, money that could have gone toward savings, investments, or home purchases. Third, punitive policies like criminal justice debt and occupational licensing barriers further erode Black families’ ability to accumulate wealth. A single traffic fine or misdemeanor conviction can trigger a cascade of financial penalties, making it harder to save or invest. The median net worth Black vs white gap isn’t just about individual choices; it’s about structural barriers that make wealth accumulation nearly impossible for Black families. Even when they overcome these obstacles, they’re often met with investor bias—Black entrepreneurs receive just 0.5% of venture capital, while white entrepreneurs with identical business plans get 10 times more funding. The system is designed to keep the gap intact.Key Benefits and Crucial Impact
The median net worth Black vs white gap isn’t just an economic issue—it’s a national security and social stability issue. Wealth isn’t neutral; it determines access to education, healthcare, and political influence. When one group’s median net worth is a fraction of another’s, the consequences extend beyond personal finance. Stagnant wealth for Black families means fewer small businesses, fewer jobs, and weaker communities. It also means greater reliance on public assistance, which strains already overburdened social safety nets. The impact is visible in homeownership rates, which sit at 44% for Black families vs 73% for white families. Home equity is the largest source of wealth for most Americans, yet Black families are systematically locked out of this pathway. The median net worth Black vs white gap also translates to lower retirement savings, meaning Black workers are more likely to enter old age with no financial cushion. This isn’t just about money; it’s about economic dignity."Wealth is the residue of daily habits—how we handle a paycheck, how we deal with a crisis, how we invest our time and energy. For Black families, the system is rigged against those habits from the start." — Darrick Hamilton, economist and author of Zora Neale Hurston and the Politics of Sustainability
Major Advantages
Despite the systemic barriers, understanding the median net worth Black vs white gap reveals three critical advantages for white families—and three urgent opportunities for policy change: - Generational Wealth Transfer: White families benefit from inherited wealth, trusts, and family business legacies that Black families rarely inherit due to historical exclusion. - Homeownership as a Wealth Multiplier: White families leverage home equity for down payments on new properties, creating a compounding effect Black families can’t replicate. - Investor and Lender Bias: White entrepreneurs and homebuyers receive preferential treatment in lending and funding, while Black applicants face higher rejection rates. - Policy Leverage: Baby Bonds (child wealth accounts) could provide Black families with a financial head start, similar to how white families benefit from inherited assets. - Workplace Equity: Closing the wage gap—even partially—would allow Black families to save and invest at rates comparable to white families. - Community Investment: Targeted mortgage subsidies and predatory lending crackdowns could accelerate homeownership for Black families, the single most effective wealth-building tool. The median net worth Black vs white gap isn’t a natural outcome—it’s a policy outcome. Addressing it requires structural changes, not just individual effort.
Comparative Analysis
| Metric | White Households | Black Households |
|---|---|---|
| Median Net Worth (2022) | $188,200 | $24,100 |
| Homeownership Rate | 73% | 44% |
| Median Retirement Savings | $120,000 | $15,000 |
Future Trends and Innovations
The median net worth Black vs white gap won’t disappear without deliberate policy shifts. One promising trend is the rise of Baby Bonds—government-funded wealth accounts for children in low-income families, designed to give them a financial head start. Pilot programs in Maryland and California have shown potential, though scaling remains a challenge. Another innovation is community wealth-building initiatives, where cities like Jackson, Mississippi, are experimenting with public banking to keep capital circulating within Black communities. However, corporate resistance and political gridlock threaten progress. The median net worth Black vs white gap is often framed as a charity issue rather than an economic necessity. Without bipartisan support for wealth redistribution policies, the gap will likely persist—or even widen as inflation and housing costs rise. The future of racial wealth equity depends on whether policymakers treat it as a priority, not an afterthought.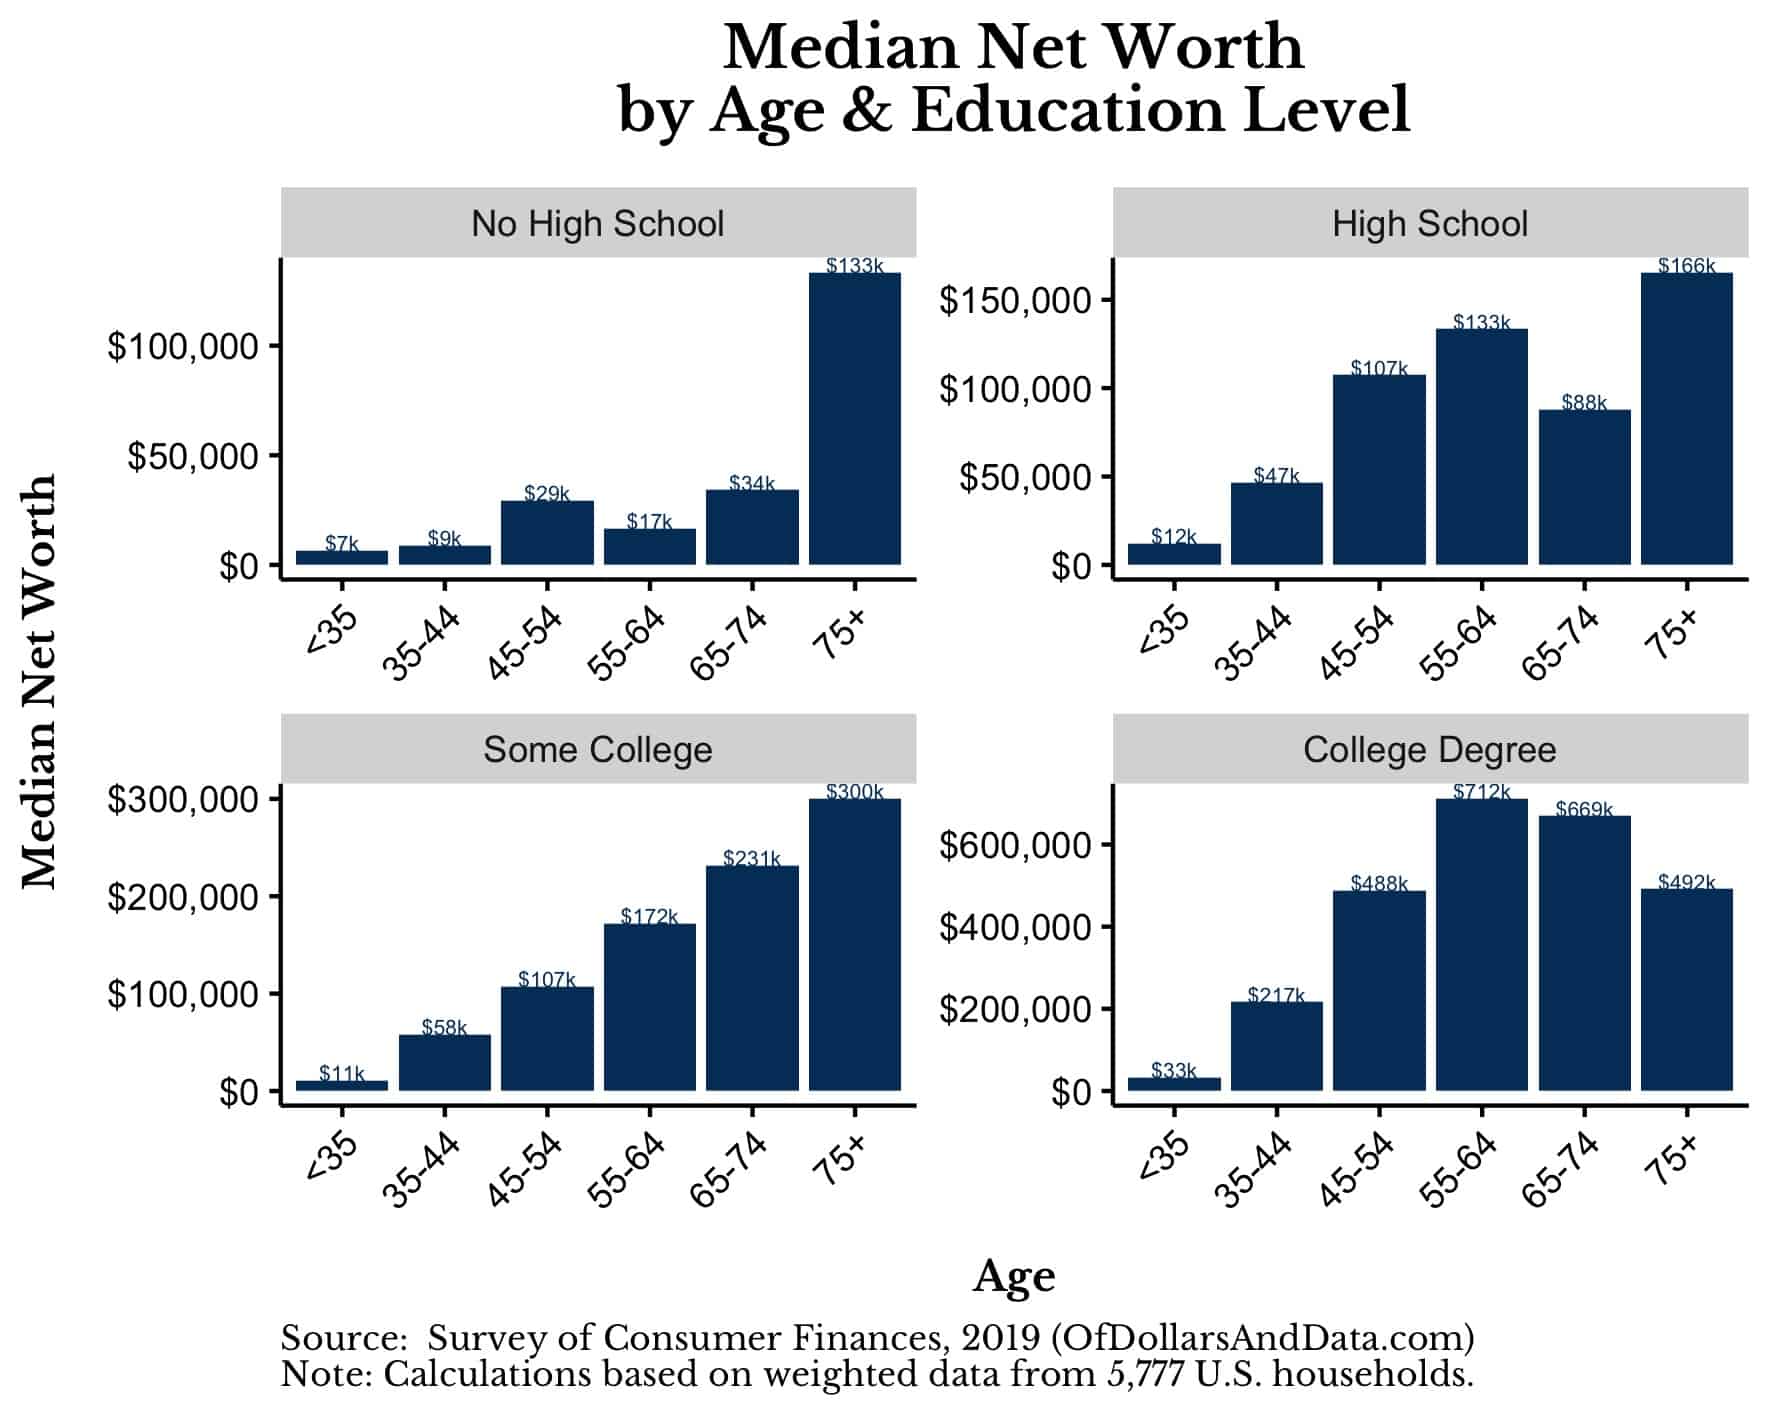
Conclusion
The median net worth Black vs white gap is more than a statistic—it’s a measure of systemic failure. It reflects centuries of exclusion, exploitation, and policy neglect. While individual success stories exist, they are exceptions in a system designed to favor one group over another. The good news? Wealth gaps can be closed with the right policies. Baby Bonds, anti-discrimination lending reforms, and wage equity measures could all make a difference—but only if implemented at scale. The median net worth Black vs white disparity isn’t a mystery. It’s the result of centuries of deliberate exclusion, and it will take centuries of deliberate inclusion to fix. The question isn’t whether change is possible—it’s whether society has the will to make it happen.Comprehensive FAQs
Q: Why is the median net worth Black vs white gap so large?
The gap stems from centuries of systemic barriers, including slavery, Jim Crow laws, redlining, predatory lending, and mass incarceration. Even when Black families earn comparable incomes, they face higher denial rates for mortgages, lower home values in segregated neighborhoods, and wage suppression. The result is a wealth inheritance gap that no amount of individual effort can overcome without structural change.
Q: Does education close the median net worth Black vs white gap?
Not significantly. While Black college graduates earn more than their non-college counterparts, they still have lower net worth than white college graduates due to wage gaps, student debt burdens, and asset exclusion. A Black family with a college degree may earn more, but they still face higher rejection rates for loans and lower homeownership rates than white families with less education.
Q: How does homeownership affect the median net worth Black vs white gap?
Homeownership is the single biggest driver of wealth accumulation in the U.S. White families benefit from home equity, which they can use for down payments, renovations, or retirement. Black families, however, face higher mortgage denial rates and lower property values in segregated neighborhoods. Even when they buy homes, they often lose more equity due to higher maintenance costs and slower appreciation in redlined areas.
Q: Are there any policies that could reduce the median net worth Black vs white gap?
Yes, but they require bold structural reforms. Baby Bonds (child wealth accounts), anti-discrimination lending laws, wage equity measures, and community land trusts could all help. However, political resistance and corporate lobbying often block these solutions. The most effective approach combines direct wealth transfers with systemic changes in housing, employment, and finance.
Q: How does the median net worth Black vs white gap affect future generations?
The gap is self-perpetuating. Black families with low net worth struggle to save for college, buy homes, or pass down inheritances. This means their children start life at a financial disadvantage, repeating the cycle. Without intervention, the median net worth Black vs white gap will likely worsen, as economic pressures like inflation and healthcare costs disproportionately affect Black families.
Q: Can individual effort alone close the median net worth Black vs white gap?
No. While personal finance habits (saving, investing, avoiding debt) matter, they can’t overcome systemic barriers. A Black family working twice as hard as a white family with the same income will still accumulate less wealth due to wage gaps, lending discrimination, and asset exclusion. Closing the gap requires policy changes, not just personal discipline.
Q: What role do corporations play in the median net worth Black vs white gap?
Corporations contribute through wage suppression, discriminatory hiring, and predatory lending. Many large employers pay Black workers less for the same work, while banks and lenders deny mortgages at higher rates to Black applicants. Additionally, venture capital and private equity overwhelmingly favor white entrepreneurs, starving Black business owners of capital. Without corporate accountability, the gap will persist.
