
7 Things Worth Knowing About the Net Worth of Blacks vs Whites
The racial wealth divide isn’t a single issue but a constellation of factors: inheritance patterns, housing discrimination, wage stagnation, and access to capital. Below are seven critical insights that explain why the net worth of Blacks vs whites remains one of the most stubborn economic divides in the U.S.1. The Wealth Gap Is Far Wider Than the Income Gap
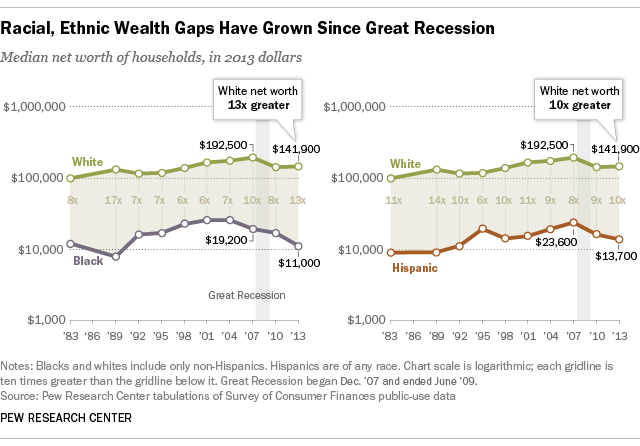
Income inequality gets more attention, but the net worth of Blacks vs whites reveals a far more entrenched problem. In 2022, the median white household had a net worth of $188,200, while the median Black household had just $24,100—a ratio of nearly 8-to-1. Income disparities pale in comparison: Black households earn roughly 62 cents for every dollar a white household earns, but wealth is the product of years of compounded advantage. A white family’s wealth isn’t just their current paycheck; it’s the sum of home appreciation, inheritances, and investments passed down through generations. For Black families, those levers have historically been out of reach. The gap widens with age. By the time white households reach their 60s, their median net worth is $236,200, while Black households of the same age have just $36,000. This isn’t a temporary setback—it’s a lifelong trajectory shaped by policies like redlining, predatory lending, and the denial of mortgage access that kept Black families locked out of the greatest wealth-building tool of the 20th century: homeownership.2. Homeownership Is the Single Biggest Driver of the Gap
Housing isn’t just shelter; it’s the largest asset most Americans will ever own. White families have a homeownership rate of 73%, while Black families hover around 44%. The difference translates directly into wealth. A home isn’t just a place to live—it’s a forced savings account that appreciates over time. When white families buy homes in predominantly white neighborhoods, they benefit from rising property values, tax deductions, and the ability to pass equity to heirs. Black families, meanwhile, have historically been steered into less valuable neighborhoods or denied mortgages altogether through practices like redlining, which persisted well into the 1960s. Even when Black families do buy homes, they often pay more for less. A 2021 study found that Black homebuyers were shown fewer properties, offered higher prices, and given less favorable loan terms than white buyers with identical financial profiles. The result? Black homeowners build wealth at a fraction of the rate of their white counterparts. Without home equity, the net worth of Blacks vs whites gap would be even wider than it already is.3. Inheritance and Wealth Transfers Favor White Families
Wealth isn’t just earned—it’s inherited. A 2020 Federal Reserve study found that white families receive 2.5 times more in inheritances than Black families, even when controlling for income. These transfers aren’t just small bequests; they can amount to hundreds of thousands of dollars over a lifetime. A white child born into a middle-class family might inherit a home, a retirement account, or a business. A Black child, even in a similar economic position, is far less likely to receive such a windfall. The reason? Historical exclusion. After slavery, 40 acres and a mule was promised but never delivered. The Homestead Act of 1862 excluded Black families, and the GI Bill—meant to help veterans buy homes—was administered in ways that shut out Black soldiers. Even today, the net worth of Blacks vs whites reflects these broken chains. White families have had generations to accumulate and pass down wealth, while Black families have had to build from scratch—without the same safety net.4. Student Loan Debt Disproportionately Hurts Black Families
Student debt isn’t just a personal financial burden; it’s a wealth destroyer. Black families carry $25,000 more in student loan debt on average than white families, and they’re less likely to see their degrees translate into higher-paying jobs. The result? A double penalty: lower income and higher debt, which erodes the net worth of Blacks vs whites even further. White families can leverage education to climb the wealth ladder, while Black borrowers often find themselves trapped in cycles of debt without the same upward mobility. The problem isn’t just borrowing—it’s repayment. Black graduates are more likely to work in lower-paying fields, making it harder to service loans. Meanwhile, wealthier white families can use education as a wealth multiplier, passing down degrees (and the associated financial benefits) to future generations. For Black families, student loans too often become a wealth drain rather than an investment.5. Black Businesses Struggle to Scale—Despite Growth in Numbers
The number of Black-owned businesses has risen sharply in recent decades, but their net worth and revenue lag far behind. While white-owned businesses dominate high-growth sectors like tech and finance, Black-owned firms are concentrated in lower-margin industries like retail and personal services. Access to capital is the biggest hurdle: Black entrepreneurs receive just 0.5% of all venture capital, despite making up 14% of the U.S. population. Even when Black businesses succeed, their owners often reinvest less in growth due to limited access to loans or investors. A white business owner might use profits to expand, hire more employees, or buy equipment—all of which increase net worth. A Black business owner, meanwhile, may struggle just to keep the doors open. The result? A wealth gap that starts in entrepreneurship and ripples outward into broader economic disparities."Wealth isn’t just money in the bank—it’s the ability to take risks, make investments, and leave something for the next generation. For Black families, those opportunities have been systematically denied." — Darrick Hamilton, economist and professor at The New School
6. Retirement Savings Show the Long-Term Cost of the Gap
By the time Americans reach retirement age, the net worth of Blacks vs whites gap becomes a crisis. White households nearing retirement have $170,600 in retirement accounts, while Black households have just $20,000. The difference isn’t just about saving habits—it’s about starting points. White workers have had decades to contribute to 401(k)s, IRAs, and pensions, often with employer matches and tax advantages. Black workers, meanwhile, have faced lower wages, job instability, and fewer retirement benefits, making it nearly impossible to catch up. The result? Black retirees are far more likely to rely on Social Security—which provides a smaller benefit—and less likely to have a financial cushion for healthcare or emergencies. The net worth of Blacks vs whites at retirement isn’t just a personal failure; it’s the culmination of a system that never gave Black families the same tools to build security.7. Policy Changes Could Shift the Trajectory—but So Far, They Haven’t
The racial wealth gap isn’t inevitable. Countries like Brazil and South Africa have closed their gaps through land redistribution, inheritance reforms, and targeted wealth-building programs. In the U.S., proposals like baby bonds (giving every child a trust fund at birth) or canceling student debt for low-income borrowers have been floated—but never fully implemented. Even the 2021 American Rescue Plan included a $10,000 child tax credit, which temporarily reduced the wealth gap by 20% for Black families. When it expired, the gap widened again. The problem isn’t a lack of solutions—it’s political will. Without sustained policy intervention, the net worth of Blacks vs whites will continue to reflect the same old inequities. The question isn’t whether change is possible; it’s whether society is willing to pay the cost of closing the gap.
How These Facts Connect
The net worth of Blacks vs whites isn’t a single issue but a feedback loop of exclusion. Homeownership begets wealth, which begets inheritance, which begets education—each step reinforcing the next. White families enter this cycle with a generational head start, while Black families are forced to play catch-up with fewer tools. Student debt doesn’t just reduce income; it erodes future wealth-building by delaying home purchases, retirement savings, and business investments. The data doesn’t just show a gap—it reveals a system. Redlining kept Black families out of wealth-building neighborhoods. Predatory lending targeted them for subprime mortgages. The GI Bill excluded them. And today, venture capital and home loans still favor white entrepreneurs and buyers. The net worth of Blacks vs whites isn’t a coincidence; it’s the result of policies that rewarded accumulation for one group while stunting it for another.| Factor | White Households | Black Households | Impact on Wealth Gap |
|---|---|---|---|
| Median Net Worth (2022) | $188,200 | $24,100 | 8-to-1 ratio, primarily driven by home equity |
| Homeownership Rate | 73% | 44% | Homes are the largest wealth asset; Black families miss out on appreciation |
| Inheritance Received | $250,000+ (lifetime avg.) | $100,000 (lifetime avg.) | White families inherit 2.5x more, creating generational wealth |
| Student Loan Debt | $30,000 (avg.) | $55,000 (avg.) | Black borrowers carry more debt with lower earning potential |
Conclusion
The net worth of Blacks vs whites isn’t just an economic issue—it’s a moral one. It reflects a society that has historically valued some lives and opportunities over others. The gap persists because the systems that created it—housing discrimination, wage suppression, capital exclusion—remain largely intact. Closing it won’t happen by accident; it will require intentional policy, wealth redistribution, and a reckoning with history. Yet the conversation is changing. More economists, policymakers, and activists are framing wealth—not income—as the key to racial equity. The question now is whether America will act on that understanding or continue to let the net worth of Blacks vs whites serve as a silent testament to its unfinished work.Comprehensive FAQs
Q: Why is the wealth gap wider than the income gap?
The wealth gap is wider because wealth is cumulative—it includes home equity, inheritances, and investments passed down over generations. Income is earned anew each year, but wealth compounds over time, giving white families a structural advantage that income alone doesn’t capture.
Q: How does redlining still affect Black wealth today?
Redlining—where banks denied mortgages in Black neighborhoods—kept Black families out of homeownership, the primary wealth-building tool. Even today, Black families live in less valuable neighborhoods, pay higher prices for homes, and have lower home equity, all direct legacies of past discrimination.
Q: Can Black families close the wealth gap on their own?
No. While individual effort matters, the gap is systemic. Black families face higher student debt, lower wages, and limited access to capital—barriers that would disappear only with policy changes, such as wealth-building programs, inheritance reforms, and fair lending practices.
Q: What’s the biggest single factor in the wealth gap?
Homeownership. White families have a 73% homeownership rate, while Black families are at 44%. Homes are the largest asset most Americans own, and the wealth gap would be even wider without them.
Q: Have any policies successfully reduced the wealth gap?
Yes, but only temporarily. The 2021 child tax credit reduced the gap by 20% for Black families before expiring. Countries like Brazil have closed gaps through land redistribution and inheritance reforms, proving that targeted policies work—but the U.S. has yet to implement lasting solutions.
Q: How does student debt worsen the wealth gap?
Black families carry $25,000 more in student debt than white families, but their degrees don’t translate into higher-paying jobs at the same rate. This double penalty—lower income and higher debt—erodes wealth that could have gone toward homes, retirement, or business investments.
Q: What would it take to close the wealth gap?
A combination of policy changes, including:
- Baby bonds (trust funds for every child at birth)
- Wealth-building programs (like the New York City’s IDA program)
- Student debt cancellation for low-income borrowers
- Fair lending reforms to correct historical housing discrimination
