
The Complete Overview of Wealth Distribution in America 2024
The U.S. has long prided itself on mobility, but the data paints a different picture. By 2024, the top 0.1%—households with net worth exceeding $22 million—hold more wealth than the entire middle class combined, according to Federal Reserve estimates. This isn’t a new phenomenon, but the scale is unprecedented. The Great Recession’s recovery disproportionately benefited asset owners, while wage stagnation left millions in limbo. Even as inflation eroded savings for middle-class families, the S&P 500 hit record highs, with the richest 10% of Americans seeing their portfolios grow by an average of 12% annually over the past decade. The consequences ripple beyond balance sheets. Wealth distribution in America 2024 isn’t just about dollars—it’s about power. Homeownership rates for Black and Latino families remain 30% lower than for white families, a gap that compounds over generations. Meanwhile, political spending by the ultra-wealthy has reached new heights, with the top 0.01% contributing nearly $1.5 billion to federal campaigns and advocacy groups since 2020. The system isn’t broken by accident; it’s designed to reward those who already have the most.Historical Background and Evolution
The modern era of extreme wealth disparity traces back to the 1980s, when deregulation and tax cuts under Reagan reshaped the economy. Corporate profits soared, but wages for non-supervisory workers stagnated. By the 1990s, the top 1%’s share of national income had rebounded to levels not seen since the Gilded Age. The 2008 crisis temporarily narrowed the gap—until the recovery began. Quantitative easing flooded markets with liquidity, but most benefits flowed to those who owned stocks, real estate, or private equity stakes. What’s changed in 2024 is the speed of wealth accumulation. The rise of passive income—dividends, capital gains, and rental yields—has created a class of "quiet millionaires" who pay minimal taxes while their portfolios grow. Meanwhile, the erosion of labor unions and the gig economy’s rise have weakened collective bargaining power. The result? A wealth distribution in America 2024 where inheritance and asset appreciation now account for 60% of the top 1%’s growth, compared to just 30% from earned income.Core Mechanisms: How It Works
Three forces dominate the current landscape. First, tax policy: The 2017 Tax Cuts and Jobs Act slashed corporate rates to 21% and capped state/local tax deductions, benefiting high earners disproportionately. In 2024, the top 1% still pay an effective federal tax rate of around 20%, while the bottom 20% pay 8%. Second, asset inflation: Housing prices have risen 40% since 2020, but only 37% of Americans own homes—leaving renters with no stake in the wealth boom. Third, inheritance dynamics: The average inheritance for the top 10% is now $2.1 million, while the bottom 90% receive nothing. Trusts and dynasty planning ensure these windfalls avoid estate taxes entirely. The feedback loop is self-reinforcing. Wealth begets political influence, which begets more wealth. Lobbying by private equity firms and hedge funds has gutted proposed wealth taxes, while corporate stock buybacks—now exceeding $1 trillion annually—boost CEO pay while shrinking the labor force. The system isn’t rigged by conspiracy; it’s optimized for efficiency—efficiency in hoarding capital, that is.Key Benefits and Crucial Impact
Proponents argue that concentrated wealth fuels innovation. Venture capital, they claim, thrives when risk-takers have deep pockets. The top 0.1% do fund breakthroughs in AI and biotech, but the benefits rarely trickle down. In 2024, the average Silicon Valley startup founder raises $50 million in seed funding—enough to employ hundreds—but only 12% of those workers earn over $150,000 annually. The real "benefit" is a two-tiered economy where high-skilled labor commands premiums, while service jobs remain stagnant. Critics point to the human cost. Child poverty rates in 2024 hover around 12%, with Black and Latino children three times more likely to live in low-wealth households. The wealth gap isn’t just economic; it’s generational. A child born into the top 1% has a 90% chance of staying there. For those in the bottom 20%, the odds of climbing out are 5%."America’s wealth inequality isn’t a bug—it’s a feature of a system designed to reward those who already have the most. The question is whether democracy can survive when power is this concentrated." — Economist Thomas Piketty, 2023
Major Advantages
- Capital accumulation: The top 1%’s net worth grew by $5.6 trillion between 2020–2024, outpacing GDP growth. Asset appreciation (stocks, real estate) drives this surge.
- Political leverage: Wealthy donors now control 70% of federal lobbying expenditures, shaping policies from healthcare to climate regulation.
- Global influence: U.S. dollar dominance and offshore accounts (estimated at $1.5 trillion held by Americans abroad) amplify the elite’s financial reach.
- Technological monopolies: FAANG companies and private equity firms capture 80% of U.S. corporate profits, with little competition.
- Intergenerational wealth transfer: Trusts and dynasty planning ensure fortunes avoid taxation, with the average ultra-high-net-worth family passing $100 million+ tax-free.
- Labor market segmentation: High-skilled workers in tech/finance earn 3x more than similar roles in manufacturing, widening skill-based pay gaps.
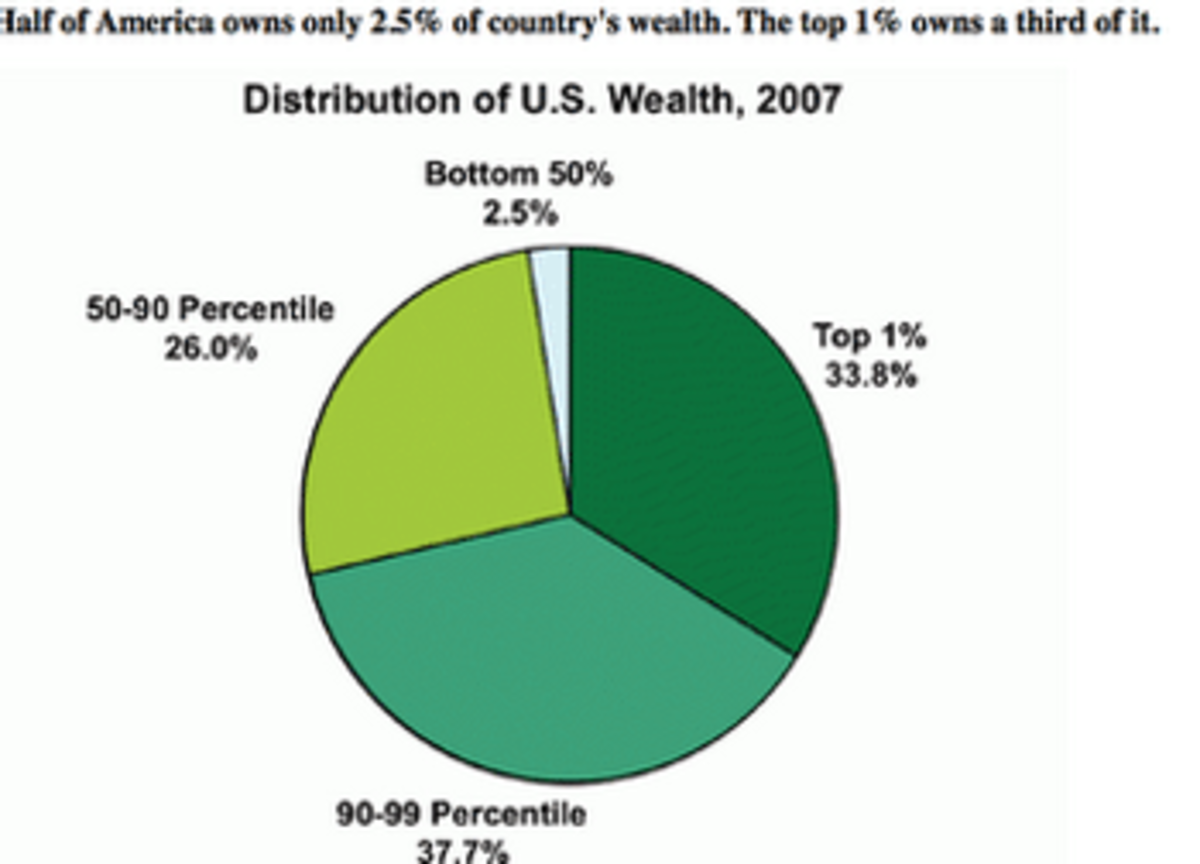
Comparative Analysis
| Metric | United States (2024) | European Average (2024) |
|---|---|---|
| Top 1% wealth share | ~35% | ~20–25% |
| Bottom 50% wealth share | ~2% | ~5–10% |
| Effective tax rate (top 1%) | ~20% | ~35–45% |
| Intergenerational mobility | Low (5% chance for bottom 20%) | Moderate (20–30% chance) |
Future Trends and Innovations
Two forces will dominate the next decade. First, automation: AI and robotics threaten to displace 30 million U.S. jobs by 2035, but the benefits will likely flow to capital owners, not workers. Second, policy shifts: Proposals for a 2% wealth tax on fortunes over $50 million are gaining traction, but corporate lobbying makes passage unlikely without a major realignment. The more probable outcome? A patchwork of state-level reforms, with California and New York leading on progressive taxation while red states double down on tax cuts for the wealthy. The wild card is public sentiment. Polls show 60% of Americans support higher taxes on the ultra-rich, but political gridlock persists. If inequality continues to rise, the backlash could take extreme forms—from populist uprisings to corporate flight. The wealth distribution in America 2024 is a ticking clock, and the question is whether the system will adapt or collapse under its own weight.Conclusion
Wealth distribution in America 2024 is a story of winners and losers, but the losers are also the ones paying the price for the system’s stability. The ultra-rich enjoy lower effective tax rates, longer lifespans, and access to elite education—while the middle class faces rising costs and stagnant wages. The data isn’t ambiguous: this is a designed outcome, not an accident. The challenge ahead is whether democracy can survive when economic power is this concentrated. The alternative isn’t pretty. History shows that societies with this level of inequality either stagnate or explode. The U.S. has avoided revolution so far, but the cracks are showing. The question isn’t if change will come—it’s how it will arrive.Comprehensive FAQs
Q: How does the wealth gap compare to past decades?
In 2024, the top 1%’s share of wealth (~35%) exceeds pre-Great Depression levels (1929: ~34%). The gap widened sharply after 2008, unlike the post-WWII era when the top 1%’s share fell to 10% by the 1970s.
Q: Why do the rich pay such low taxes?
Tax loopholes—capital gains exemptions, offshore accounts, and pass-through entities—allow the top 0.1% to pay an effective rate of ~20%, while the bottom 50% pay ~8%. Corporate tax avoidance (e.g., Apple’s $19 billion offshore hoard) exacerbates the issue.
Q: Can middle-class Americans still build wealth?
Yes, but the barriers are steep. Homeownership (the traditional wealth-builder) requires a $30,000+ down payment in 2024, while student debt averages $40,000 per borrower. Without inheritance or high-income jobs, mobility is rare.
Q: How do trusts avoid estate taxes?
Dynasty trusts (lasting decades) and valuation discounts (undervaluing assets) let families pass $100M+ tax-free. The 2017 tax law doubled the exemption to $12.06 million per person, making avoidance easier.
Q: What’s the role of corporate buybacks?
Companies spent $1.2 trillion on buybacks in 2023, inflating stock prices for shareholders (often executives) while cutting jobs. This redistributes wealth upward, as 80% of buyback benefits go to the top 1%.
Q: Are there any bright spots for equality?
State-level policies help: California’s 1% surtax on millionaires raised $1.5 billion in 2023, while cities like Minneapolis have wealth taxes (0.1% on fortunes over $500K). However, these are exceptions.
Q: What would a wealth tax look like?
Proposals range from 1–4% on fortunes over $50M–$100M. Elizabeth Warren’s 2020 plan (2% on $50M+) could raise $3.7 trillion over a decade, but opposition from the ultra-rich and GOP blocks progress.
Q: How does global wealth compare?
The U.S. has the highest Gini coefficient (0.48) among developed nations, worse than Germany (0.30) or France (0.29). Only Brazil (0.54) and South Africa (0.63) exceed it.
