The Complete Overview of the Median US Household Net Worth in 2022 Survey of Consumer Finances
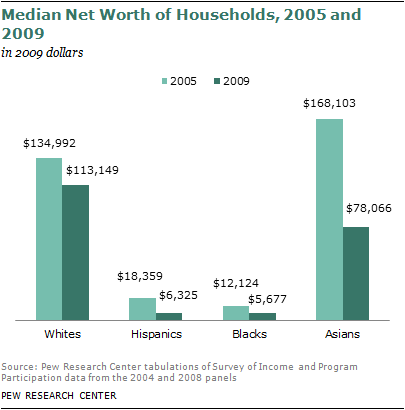
The 2022 Survey of Consumer Finances painted a picture of a nation still grappling with the aftermath of the pandemic, where asset appreciation for some clashed with stagnant wages for others. The median US household net worth rose, but the gains were uneven. Homeownership rates climbed to 65.9%, up from 64.8% in 2019, while retirement account balances swelled—401(k) and IRA assets grew by 12%—thanks to market rallies. Yet, for renters and younger households, the picture was bleaker: 42% of households under 35 had no retirement savings at all. The survey also highlighted how demographics shaped wealth accumulation. White households reported a median net worth of $188,200, compared to $48,800 for Black households and $97,500 for Hispanic households. These gaps persisted even after controlling for income, education, and age—proof that wealth isn’t just about earnings but about generational advantage. The data forced a reckoning: median US household net worth wasn’t just a financial metric; it was a measure of opportunity. What made the 2022 SCF particularly revealing was its timing. Released in late 2023, it captured the tail end of the Fed’s asset-purchase programs and the early stages of inflation-driven erosion. The survey’s timing meant it didn’t reflect the full brunt of 2022’s economic turbulence—rising interest rates, stock market volatility, or the housing market’s sharp slowdown—but it did show how pre-existing trends were hardening. The question wasn’t whether wealth inequality was worsening; the data confirmed it was, just at a slower pace than the headlines suggested.Historical Background and Evolution
The Survey of Consumer Finances has been tracking median US household net worth since 1989, making it one of the most reliable long-term datasets on American wealth. Its origins trace back to the Federal Reserve’s need to understand household balance sheets after the Savings & Loan crisis of the 1980s. Over decades, the SCF evolved from a narrow focus on debt to a comprehensive look at assets, liabilities, and financial behaviors—including cryptocurrency holdings for the first time in 2022. The 2022 report wasn’t just a snapshot; it was a continuation of a decades-long trend. Since the 2008 financial crisis, the median US household net worth had recovered, but the recovery was lopsided. The bottom 90% of households saw their net worth grow by $15,000 from 2013 to 2019, while the top 1% gained $1.5 million. The pandemic accelerated this divergence: stimulus checks, low-interest rates, and a roaring stock market lifted asset values, but for many, these gains were offset by rising costs of living. The 2022 SCF showed that by 2022, the median net worth had not just returned to pre-crisis levels but surpassed them—but only for those who owned stocks, homes, or businesses. The survey also introduced new variables, like student loan debt and gig economy earnings, which complicated the narrative. While total student debt reached $1.7 trillion, its impact on net worth was uneven: borrowers in high-earning fields saw it as an investment, while others viewed it as a wealth drag. The SCF’s inclusion of these factors reflected a shifting economic landscape where traditional measures of wealth—homeownership, retirement accounts—were no longer the sole determinants of financial health.Core Mechanisms: How It Works
The Survey of Consumer Finances operates on a rotating panel design, interviewing 6,000 households every three years to ensure statistical reliability. Unlike annual reports, its triennial cycle means the 2022 data reflects conditions from mid-2021 to mid-2022, capturing the transition from pandemic stimulus to inflationary pressures. The Fed’s methodology includes weighting for non-response and adjusting for inflation, but critics note it still underrepresents certain groups—like the ultra-wealthy, who are sampled less frequently. What makes the median US household net worth metric unique is its focus on the middle, not the mean. The mean (average) net worth in 2022 was $1,076,400, but this figure is skewed by billionaire wealth. The median, at $255,400, tells a different story: it’s the value at which half of households have more and half have less. This distinction is crucial because it reveals where the average American stands—not the outliers. The SCF’s emphasis on medians, debt-to-income ratios, and asset classes (like real estate vs. financial assets) allows policymakers to spot trends before they become crises. The survey’s depth lies in its breakdowns: by race, age, education, and geography. For example, households in the Northeast had the highest median net worth ($305,900), while those in the South lagged ($203,700). These regional disparities reflect historical factors—like redlining, industrial decline, and differences in homeownership rates. The SCF doesn’t just describe wealth; it exposes the mechanisms that create it—or prevent its accumulation.Key Benefits and Crucial Impact
The 2022 Survey of Consumer Finances wasn’t just an academic exercise; it had real-world consequences. For policymakers, the data provided a roadmap for addressing inequality. The median US household net worth figures showed that wealth-building programs—like first-time homebuyer incentives or expanded retirement accounts—were needed more than ever. For economists, the survey clarified how financial shocks (like the 2020 stock market crash) disproportionately affected lower-income households, which lacked the liquid assets to weather downturns. The report also served as a wake-up call for financial institutions. Banks and investment firms used the data to refine their products, recognizing that traditional savings strategies weren’t enough for younger or lower-income demographics. The rise of high-yield savings accounts and robo-advisors post-2022 can be traced back to the SCF’s revelations about financial exclusion. Even the gig economy’s growth—highlighted in the survey—pushed platforms like Uber and DoorDash to offer benefits that mimicked traditional employer-sponsored wealth-building tools."Wealth isn’t just about income; it’s about access. The 2022 SCF shows that without structural changes, the median household will keep chasing a moving target." — Darrick Hamilton, economist and wealth inequality researcher
Major Advantages
- Policy precision: The SCF’s granular data allowed targeted interventions, like the American Rescue Plan’s child tax credit expansions, which temporarily reduced child poverty by 40%. The survey’s racial wealth gaps guided debates on reparations and equity-focused lending.
- Market transparency: Investors used the median US household net worth trends to predict consumer spending patterns. A rising median suggested stronger demand for durable goods, while stagnant figures signaled caution.
- Educational tool: Financial literacy programs leveraged SCF data to teach households about asset diversification, retirement planning, and debt management—critical skills given the survey’s findings on retirement savings shortfalls.
- Regional economic planning: Cities and states used the data to design housing policies. For instance, San Francisco’s high median net worth ($1.3 million) contrasted with Detroit’s ($120,000), prompting discussions on wealth redistribution through land trusts and community investment funds.
- Historical benchmark: The SCF’s long-term dataset became a reference point for debates on automatic wealth-building policies, like baby bonds or wealth taxes, by quantifying how much progress had (or hadn’t) been made.
- Corporate accountability: Companies faced pressure to address pay gaps after the survey showed that women’s median net worth was 30% lower than men’s, even at similar income levels. This data fueled demands for equal pay audits and career advancement programs.
Comparative Analysis
| Metric | 2022 SCF Findings |
|---|---|
| Median Net Worth Growth (2019–2022) | +6.5% (adjusted for inflation), but top 10% saw 25%+ gains in liquid assets. |
| Homeownership Rate | 65.9% (up from 64.8% in 2019), but Black homeownership remained at 44.5% vs. 73.7% for whites. |
| Retirement Savings Gap | Households headed by someone under 35 had $0 in retirement accounts in 42% of cases, up from 38% in 2019. |
Future Trends and Innovations
The 2022 Survey of Consumer Finances hinted at shifts that would define the next decade. The rise of alternative assets—like cryptocurrency (held by 12% of households) and peer-to-peer lending—suggested a diversification of wealth-building strategies. However, the survey also warned that these new avenues were not democratized: 90% of crypto holders were in the top 50% of earners. This raised questions about whether decentralized finance would deepen inequality or offer a path to inclusion. Another looming trend was the intersection of climate risk and net worth. The SCF didn’t track environmental exposures directly, but regional disparities—like Florida’s median net worth ($280,000) vs. Minnesota’s ($320,000)—hinted at how climate-related migration and property values could reshape wealth. As extreme weather events increased, households in vulnerable areas faced asset depreciation risks, while those in resilient regions saw property value appreciation. The next SCF (due in 2025) may need to incorporate climate resilience as a wealth factor.
Conclusion
The 2022 Survey of Consumer Finances was more than a data dump; it was a mirror held up to America’s financial soul. The median US household net worth figure wasn’t just a number—it was a measure of who had been included in the economy’s recovery and who had been left behind. The data confirmed what activists and economists had long argued: wealth accumulation in the U.S. was not a meritocracy but a legacy system, where race, geography, and generational head starts determined outcomes. Yet, the survey also offered a glimmer of hope. The fact that the median had risen at all—even modestly—proved that policy interventions could work. The child tax credit, expanded unemployment benefits, and low-interest rates had all played a role. The challenge now was to build on these successes without repeating the mistakes of the past. The 2022 SCF wasn’t just a report; it was a call to action. Ignore its warnings, and the wealth gap would widen. Heed them, and the next survey might tell a different story—one where the median wasn’t just a statistic, but a step toward equity.Comprehensive FAQs
Q: How often is the Survey of Consumer Finances conducted?
A: The Federal Reserve releases the SCF every three years, with the most recent data covering 2022. The next survey is expected in 2025, though some microdata (like asset-level details) is available annually.
Q: Why does the median matter more than the mean in wealth discussions?
A: The median US household net worth represents the typical household, while the mean (average) is distorted by billionaire wealth. For example, in 2022, the mean was $1.08 million, but the median was $255,400—showing most Americans aren’t as wealthy as the average suggests.
Q: How did the pandemic affect the racial wealth gap?
A: The gap widened. While white households saw their median net worth rise by $20,000 from 2019 to 2022, Black households’ median grew by just $5,000. The SCF attributed this to home equity gains (higher for whites) and investment returns, which disproportionately benefited those already wealthy.
Q: Can I access the raw SCF data?
A: Yes, but with limitations. The public-use microdata (anonymized household-level details) is available on the Federal Reserve’s website, though some sensitive variables are suppressed to protect privacy. Researchers can apply for restricted-access datasets.
Q: How does student debt impact net worth?
A: The 2022 SCF showed that households with student loans had a median net worth 40% lower than those without. The burden was worse for Black and Hispanic borrowers, who faced higher default rates and lower post-graduation earnings.
Q: What’s the biggest misconception about the SCF?
A: Many assume the survey reflects real-time conditions, but its triennial cycle means it’s always one year behind. For example, the 2022 report doesn’t capture the 2022–2023 market downturn or the student debt relief debates of 2023.
Q: How do gig economy earnings show up in the SCF?
A: The 2022 survey included side hustle income for the first time, revealing that 22% of households earned gig money. However, these earnings were volatile—only 10% of gig workers had retirement savings tied to their side income.
Q: What policies could close the wealth gap based on SCF data?
A: The data supports three key strategies: 1. Automatic wealth-building tools (e.g., baby bonds, payroll-linked IRAs). 2. Homeownership expansion (e.g., down payment assistance, rent-to-own programs). 3. Debt relief (e.g., student loan forgiveness, medical debt elimination). The SCF shows these would have the most impact on Black and Hispanic households.
