
Common Myths About the Shark Tank Sharks List
The shark tank sharks list is frequently reduced to a collection of larger-than-life personalities, but the reality is more nuanced. One persistent myth is that every shark invests equally—whether in startups, real estate, or franchises. In truth, their portfolios reflect specialized interests. Mark Cuban, for instance, has historically favored tech and SaaS ventures, while Barbara Corcoran’s real estate deals dominate her track record. The show’s format obscures these distinctions, leading viewers to assume a uniformity that doesn’t exist. Another misconception is that the shark tank sharks list is static. Shark Tank’s rotating panel—with guest appearances and occasional departures—creates the impression of fluidity, but the core investors have remained consistent for over a decade. The show’s producers deliberately maintain this stability to preserve brand recognition, even as individual sharks’ business priorities evolve. For example, Robert Herjavec’s cybersecurity focus has grown alongside the rise of digital threats, yet his early deals in retail and tech often overshadow this shift in public memory.Myth 1: All Sharks Invest the Same Way
The idea that every shark on the shark tank sharks list evaluates deals through identical lenses is a simplification. Daymond John, for example, prioritizes branding and scalability, often seeking products with mass-market potential. His investment in companies like FUBU and The Shark Tank’s own merchandise line underscores his belief in storytelling as a driver of value. Meanwhile, Kevin O’Leary’s approach is rooted in hard metrics—revenue multiples, profit margins, and exit strategies. His demand for equity control reflects a hedge-fund mentality, not the entrepreneurial flexibility some assume. The confusion stems from the show’s editing, which emphasizes dramatic negotiations over strategic rationale. A shark’s first offer—whether it’s Cuban’s "$100,000 for 10%" or O’Leary’s "$500,000 for 50%"—becomes a shorthand for their entire philosophy. Yet behind these headlines lie vastly different risk appetites. Lori Greiner’s focus on consumer products with strong retail potential contrasts sharply with Herjavec’s emphasis on tech infrastructure. The shark tank sharks list is a spectrum, not a monolith.Myth 2: Sharks Only Invest in Profitable Companies
The notion that the shark tank sharks list backs only cash-flow-positive businesses ignores the show’s core premise: funding early-stage ventures. Many sharks, particularly those with entrepreneurial backgrounds, actively seek high-risk, high-reward opportunities. Barbara Corcoran’s early investments in struggling real estate projects—like her own turnaround of a failing Brooklyn property—demonstrate her willingness to bet on turnarounds. Similarly, John’s investments in unproven brands (e.g., S’well before its mainstream success) prove that his criteria include market fit over immediate profitability. The show’s structure amplifies this myth by spotlighting deals that close quickly, often with pre-revenue companies. Yet the shark tank sharks list includes investors who specialize in different stages: Cuban in growth-stage tech, O’Leary in acquisition targets, and Greiner in product-led scaling. The misconception arises because viewers associate "shark" with predatory efficiency, forgetting that many of these investors were once founders themselves—navigating the same uncertainties they now evaluate.Myth 3: The Sharks’ On-Screen Personas Define Their Investments
The shark tank sharks list thrives on larger-than-life personas—O’Leary’s bluntness, Cuban’s tech guru image, Corcoran’s folksy charm—but these traits rarely dictate deal terms. Behind the scenes, their investment committees (where they exist) and legal teams negotiate terms that align with their actual business models. For instance, Herjavec’s cybersecurity expertise might lead him to scrutinize a SaaS company’s data security protocols far more than his on-screen demeanor suggests. Similarly, Greiner’s retail background influences her due diligence on supply chains, even if she’s pitching a consumer product on TV. The disconnect between persona and practice is most evident in failed deals. A shark’s public criticism of a pitch (e.g., "This is a scam") doesn’t always reflect their private assessment. Some rejections stem from strategic misalignment—like Cuban passing on a hardware startup because it didn’t fit his software focus—rather than personal judgment. The shark tank sharks list is a performance, but the investments are calculated.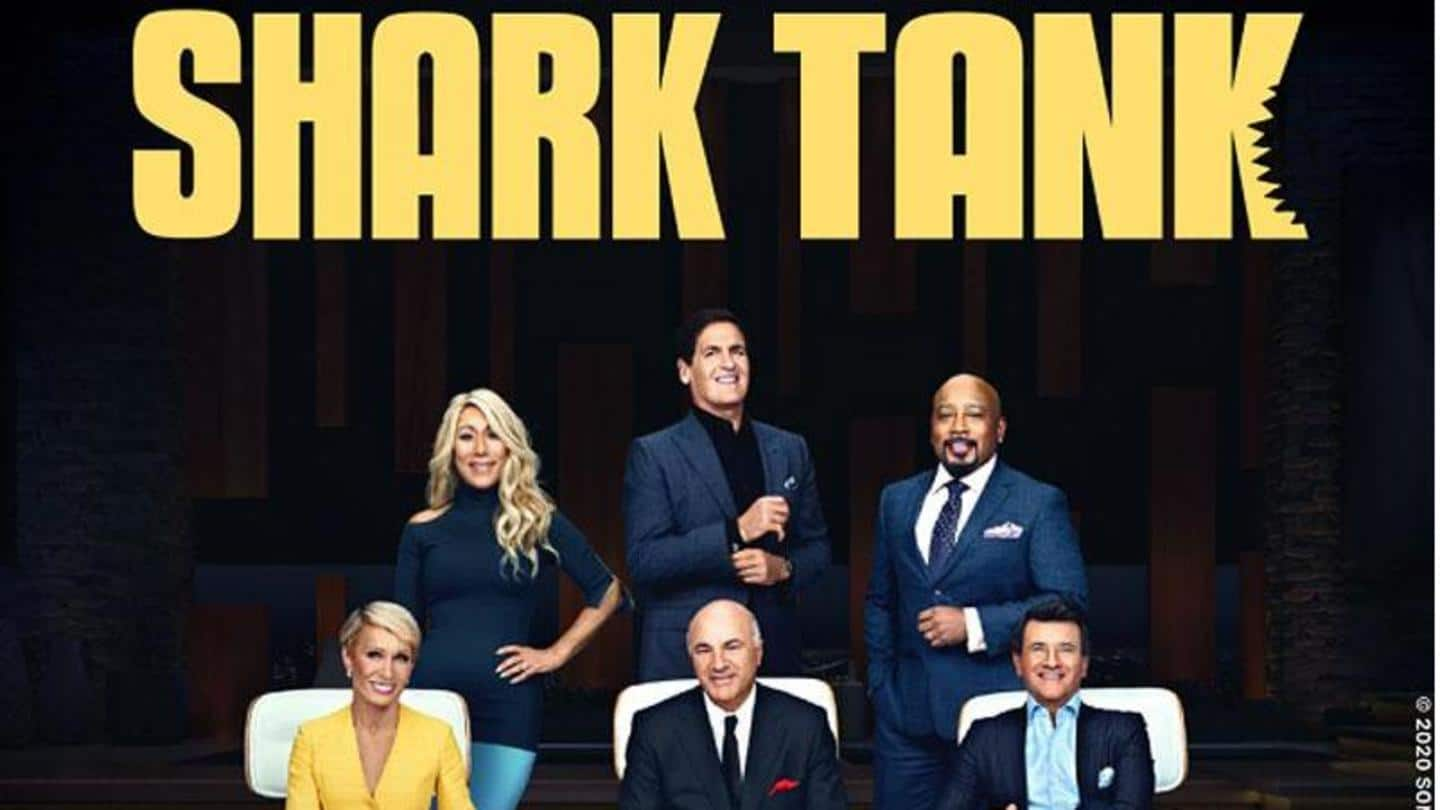
What Holds Up to Scrutiny
At its core, the shark tank sharks list functions as a hybrid of entertainment and venture capital. The sharks’ real value lies in their ability to provide not just funding but also validation, distribution channels, and operational expertise. For example, John’s connections in fashion and retail have helped portfolio companies like Feetures scale beyond what traditional VC could offer. Similarly, Cuban’s relationships with other tech investors (e.g., his partnership with Broadcast.com’s sale to Yahoo) create ripple effects for his startups. The show’s success as a business incubator is measurable, though often overlooked. According to PitchBook, Shark Tank-backed companies have raised over $1 billion in follow-on funding, with exits like Scrub Daddy (acquired for $140 million) and Ring (sold to Amazon for $1.8 billion) proving the model’s efficacy. Yet these figures mask the high failure rate—most Shark Tank deals don’t recoup their investment. The shark tank sharks list’s true metric isn’t the number of deals closed but the quality of those that thrive."We’re not just investors; we’re brand ambassadors. If I put my name on something, it’s got to be scalable—or I’m not doing it." —Daymond John, 2021 interview with Forbes
| Common Belief | What the Evidence Says |
|---|---|
| Sharks invest in every sector equally. | Portfolios skew toward their expertise: Cuban (tech), Greiner (retail), Herjavec (cybersecurity). |
| All deals are high-risk, high-reward. | Some sharks (e.g., O’Leary) prefer acquisition targets with proven revenue. |
| The show’s drama reflects real negotiation tactics. | Many terms are pre-negotiated; on-screen haggling is often staged for tension. |
Why the Confusion Persists
The shark tank sharks list’s dual role—as both investors and media personalities—creates inherent tension. The show’s producers prioritize conflict and charisma over educational value, leaving viewers to assume that every shark’s approach is interchangeable. Additionally, the panel’s longevity (since 2009) has blurred distinctions between their evolving strategies. A shark’s early deals—like Corcoran’s real estate ventures in the 2010s—are still referenced as representative of her current focus, even as her later investments in tech (e.g., HomeAdvisor) signal a shift. Social media exacerbates the problem. Memes and soundbites (e.g., "Kevin’s ‘Mr. Wonderful’ vibes") reduce complex investment philosophies to catchphrases. Meanwhile, the sharks themselves contribute to the mystique by maintaining controlled public images. John’s emphasis on mentorship, O’Leary’s financial acumen, and Cuban’s tech authority are all real—but the shark tank sharks list’s collective identity overshadows these individualities.
Conclusion
The shark tank sharks list is more than a cast of characters; it’s a case study in how celebrity and capital intersect. Their real impact lies in the synergies between their backgrounds and the startups they back. While the show’s entertainment value drives ratings, the sharks’ long-term success depends on their ability to adapt—whether by pivoting sectors (e.g., Herjavec’s AI focus) or refining their criteria (e.g., Greiner’s move toward DTC brands). The confusion around their strategies persists because the shark tank sharks list is both a product and a reflection of broader trends in venture capital: accessibility, branding, and the blurred line between founder and investor. For entrepreneurs, understanding the shark tank sharks list isn’t about memorizing their bios but recognizing how their pasts shape their present. A pitch to Cuban demands a tech narrative; one to Corcoran needs a real estate angle. The sharks’ diversity is their strength—and their greatest untapped resource for founders willing to look beyond the show’s surface.Comprehensive FAQs
Q: How do the sharks decide which pitches to accept?
The shark tank sharks list evaluates deals based on three pillars: alignment with their expertise, scalability, and personal connection. For example, a shark with a retail background (like Greiner) will scrutinize supply chain logistics, while a tech-focused shark (like Cuban) will probe product-market fit. Pre-show research—including financials and market data—plays a critical role, though the on-screen negotiation often obscures this due diligence.
Q: Can a shark invest in a company without appearing on the show?
Yes. The shark tank sharks list includes off-screen investments, particularly for follow-on funding or companies that don’t fit the show’s pitch format. For instance, Cuban has invested in non-Shark Tank startups like Maven (a healthcare platform) through his separate funds. The show’s producers may also invite sharks to evaluate deals behind the scenes, though these aren’t publicized to maintain the program’s drama.
Q: What’s the most common reason a shark rejects a deal?
According to industry insiders, the top reasons for rejection on the shark tank sharks list are: 1. Lack of scalability—the product or service can’t grow beyond a niche. 2. Misaligned valuation—founders demand terms that don’t reflect market reality. 3. Founder-market fit—the team lacks the credibility or skills to execute. Sharks like O’Leary are notorious for killing deals over valuation, while John often rejects pitches that don’t emphasize branding.
Q: How do the sharks’ personal brands affect their investments?
The shark tank sharks list’s personal brands serve as both assets and liabilities. A shark’s reputation can attract talent (e.g., John’s connections in fashion) or deter certain founders (e.g., O’Leary’s blunt style may intimidate first-time entrepreneurs). However, their brands also create expectations—like Cuban’s tech focus—that can limit their flexibility. For example, a shark known for retail (Greiner) might struggle to justify a non-consumer-facing investment to their audience, even if it’s financially sound.
Q: Are there sharks who’ve left the shark tank sharks list permanently?
As of 2024, the core shark tank sharks list remains stable, but guest appearances and temporary departures have occurred. Venture capitalist Chris Sacca was a guest shark in 2016 but didn’t return due to scheduling conflicts. Daymond John briefly considered leaving in 2019 over creative differences but ultimately stayed. The show’s producers prefer continuity to avoid disrupting the panel’s dynamic, though occasional changes (like Mark Cuban’s reduced screen time in later seasons) reflect shifting priorities.
Q: How do the sharks’ investments perform compared to traditional VC?
Data from CB Insights suggests Shark Tank-backed companies have a higher failure rate than those funded by traditional VCs (around 60% vs. 40%), but their success stories (e.g., S’well, Ring) generate outsized returns. The shark tank sharks list’s advantage lies in non-financial support—mentorship, distribution, and media exposure—that traditional VCs rarely provide. However, their smaller deal sizes and lack of structured follow-on funding limit their ability to scale portfolio companies like top-tier VC firms.
