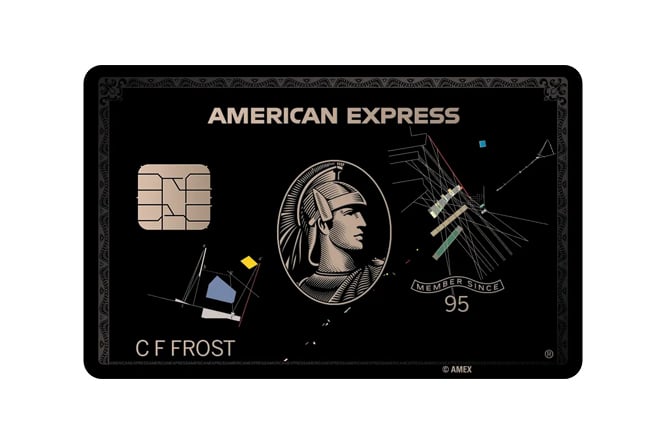
Where It All Began
The black card’s origins trace back to 1999, when American Express introduced the Centurion Card as a private-label offering for its most trusted clients. Unlike the Platinum Card, which was (and still is) marketed broadly, the black card was an invitation-only product. The first recipients were handpicked by Amex’s elite client managers, who relied on a mix of financial data, personal referrals, and—most critically—behavioral patterns. The card wasn’t just a credit tool; it was a signal. It told the world (and Amex’s partners) that you were someone who could be trusted with access to the most exclusive perks: private jet reservations, $200 bottle of wine credits, and concierge services that could arrange anything from a last-minute opera ticket to a diplomatic favor. The early signs of the black card’s power were subtle but undeniable. Holders reported being treated like VIPs not just at Amex’s own properties, but at high-end retailers, luxury hotels, and even private members’ clubs. Amex’s strategy was simple: create scarcity. By limiting distribution and making the approval process opaque, the black card became a status symbol that money alone couldn’t buy. The qualifications weren’t just financial; they were about lifestyle alignment. If you spent your weekends at the same clubs as Amex’s target demographic, if your travel patterns matched those of the global elite, and if your credit history suggested you were the kind of person who paid bills before they were due—then, just maybe, you’d get the call.The Early Signs
The first public hints about the black card American Express qualifications came in the early 2000s, when a few high-profile denials made headlines. A tech CEO with a net worth in the hundreds of millions was reportedly rejected after his concierge service logged a complaint about his "disruptive behavior" at a Michelin-starred restaurant. Meanwhile, a Wall Street banker with a seven-figure income was approved after his Amex Platinum spending—particularly his use of the card’s travel credits—demonstrated he was exactly the kind of client Amex wanted to cultivate. The message was clear: it wasn’t just about how much you had, but how you conducted yourself. By 2005, the black card had evolved into a tool for Amex’s most lucrative partnerships. Airlines like Emirates and Qatar Airways began offering black card holders priority boarding and access to business-class lounges that were off-limits to even first-class passengers. The qualifications, however, remained a moving target. Amex’s internal teams would adjust approval criteria based on real-time data—if too many holders were defaulting on high-limit loans, the bar would rise. If a particular demographic (say, international executives) was underrepresented, the algorithm would nudge toward those profiles. The result? A qualification process that was as dynamic as it was elusive.The Turning Point
The black card’s reputation shifted in 2011, when American Express officially rebranded the Centurion Card under the American Express Platinum Card umbrella—but kept the black card’s elite tier separate. This was the moment when Amex realized the card’s value wasn’t just in exclusivity, but in data monetization. The more high-net-worth individuals used the card, the more Amex learned about their spending habits, travel patterns, and even social connections. The qualifications became less about static metrics and more about predictive behavior. If you were likely to spend $50,000 on a single trip, if you booked private jet charters through Amex’s concierge, or if your annual travel spend exceeded six figures—then you were a candidate. The turning point wasn’t just about the numbers, though. It was about the psychology of access. Amex began using its black card holders as ambassadors, inviting them to exclusive events where they could network with other elite clients. The qualifications now included an element of social proof: if your peers had the card, you were more likely to get it. This created a feedback loop where the ultra-wealthy reinforced their own status, while those just below the threshold found themselves perpetually on the outside looking in."The black card isn’t a reward for wealth—it’s a reward for the kind of discretion that makes wealth sustainable. If you’re the kind of person who flaunts your success, Amex will find a way to say no." — Former Amex Elite Client Manager (2010–2018)
The Build-Up, Year by Year
The evolution of the black card American Express qualifications can be broken down into key phases, each reflecting shifts in Amex’s strategy and the financial behavior of its target clients.| Period | Key Developments |
|---|---|
| 1999–2003 | Black card introduced as a private offering. Qualifications based on personal referrals, high spending on Amex Platinum, and discretion. No public application process. |
| 2004–2008 | First public denials spark speculation. Amex begins tracking behavioral data (on-time payments, concierge usage, travel patterns). Income thresholds emerge as a secondary factor. |
| 2009–2012 | Global financial crisis leads Amex to tighten approvals. Black card becomes a tool for retaining high-value clients. Partnerships with luxury brands (e.g., Rolls-Royce, Aman Resorts) expand perks. |
| 2013–2016 | Leaked internal documents reveal that black card American Express qualifications now include social network analysis—who you associate with matters as much as what you spend. Amex starts courting "influential" clients (e.g., private jet operators, art collectors). |
| 2017–Present | Formalized "invitation-only" model. Amex uses AI to predict approval likelihood based on spending velocity, concierge interactions, and even charitable giving patterns. Black card holders now act as "brand ambassadors" for Amex’s luxury partnerships. |
Lessons From the Journey
The history of the black card’s qualifications reveals four critical truths about how elite financial products work: - Discretion is the real currency. Amex’s algorithms don’t just look at your bank balance—they analyze whether you’re the kind of person who might embarrass the brand. Late payments, public disputes, or even a single complaint to concierge can derail approval. - Spending habits matter more than raw income. If you’re not using Amex’s existing products (Platinum, Delta SkyMiles, etc.), you’re unlikely to qualify. The card rewards loyalty to the ecosystem, not just wealth. - Social capital is a qualification. If your friends, business partners, or even service providers (e.g., private bankers) are Amex black card holders, your approval odds improve. The card thrives on networks. - The bar is always moving. Amex adjusts qualifications in real time. If too many holders default, the criteria tighten. If a new luxury partnership emerges (e.g., a private island resort), the qualifications may shift to favor clients who align with that demographic.Where Things Stand Today
As of 2024, the black card American Express qualifications remain one of the most closely guarded secrets in finance. While Amex no longer issues the card without an application, the process is still invitation-only—and the invitations are extended based on a combination of financial data, behavioral patterns, and unwritten rules. The card is now tied to Amex’s Global Lounge Collection, offering access to over 1,300 lounges worldwide, as well as perks like $400 annual credits for fine dining, private jet reservations through NetJets, and even a 24/7 concierge service that can arrange anything from a last-minute table at Noma to a diplomatic visa on short notice. What hasn’t changed is the psychological test. Amex still looks for clients who understand that the black card isn’t a trophy—it’s a tool. Holders who treat it as a status symbol (e.g., flashing it at boutique hotels or using it for everyday purchases) risk losing access. The card’s true value lies in its utility for the ultra-wealthy: it’s a key to a world where money isn’t just spent, but leveraged. Whether you’re a hedge fund manager arranging a private yacht charter or a tech CEO securing a last-minute VIP experience for a client, the black card’s power comes from what it unlocks—not what it costs.
Conclusion
The black card’s qualifications have never been about meeting a single threshold. They’ve always been about proving you belong. American Express doesn’t just want your money—it wants your loyalty, your discretion, and your influence. The card’s approval process is a reflection of how the ultra-wealthy operate: not through public displays of wealth, but through quiet, consistent behavior that signals trustworthiness. For those who understand this, the black card isn’t just a credit card—it’s a membership in a silent economy, where access is more valuable than ownership. The irony? The more Amex tries to demystify the process, the more elusive it becomes. The qualifications aren’t published because they can’t be. They’re a living, breathing standard—one that shifts with the tides of wealth, power, and the unspoken rules of the elite. If you’re chasing the black card, remember this: the card isn’t the goal. It’s the byproduct of a life already lived on its terms.Comprehensive FAQs
Q: What is the minimum income required to qualify for the black card?
A: American Express does not disclose income thresholds, but industry estimates suggest figures around the $500,000–$1 million range are common for approval. However, income alone isn’t the deciding factor—spending habits, credit history, and behavioral data (e.g., concierge usage, travel patterns) play a larger role. Some applicants with lower incomes but high Amex spending (e.g., $50,000+ annually on Platinum cards) have been approved.
Q: Can I apply for the black card directly, or is it only by invitation?
A: As of 2024, Amex offers a formal application process for the black card (officially the American Express Centurion Card), but approval is still invitation-based. You can request an application through your Amex Platinum account or by calling Amex’s elite client line. However, the majority of approvals come from internal referrals—meaning your existing Amex relationship (e.g., high spending, concierge interactions) matters more than a standalone application.
Q: What happens if I’m denied for the black card?
A: Denials are rare but not unheard of. If you’re rejected, Amex may suggest upgrading to the Platinum Card or offer strategies to improve your approval odds (e.g., increasing spending, resolving credit issues). Some denied applicants have successfully reapplied after 12–18 months of demonstrating stronger financial behavior. However, public complaints or negative concierge feedback can lead to permanent disqualification.
Q: Are there non-financial factors that affect approval?
A: Yes. Amex’s internal teams review concierge service logs for complaints, travel patterns (e.g., frequent use of Amex travel credits), and even social connections. If your network includes other black card holders, private jet operators, or high-end service providers (e.g., art consultants, yacht brokers), your approval odds improve. Conversely, disruptive behavior (e.g., arguing with staff, excessive cancellations) can result in denial.
Q: How does the black card differ from the Platinum Card?
A: The Platinum Card is a mass-market premium product with a $695 annual fee, while the black card has a $5,000 fee (waived the first year for new applicants). Key differences include:
- Access: Black card holders get priority entry to Amex’s Global Lounge Collection, while Platinum members have limited access.
- Perks: Black card includes $400 annual dining credits, private jet reservations, and concierge services that can arrange VIP experiences (e.g., backstage passes, diplomatic favors).
- Network: Black card holders are often invited to exclusive Amex events where they can network with other elite clients.
Q: Can I get the black card if I live outside the U.S.?
A: Yes, but approval is region-specific. Amex has separate black card programs for the U.S., Canada, Europe, and Asia-Pacific. Qualifications vary by market—e.g., in Hong Kong or Singapore, local wealth thresholds (e.g., property ownership, business revenue) may carry more weight than in the U.S. Some international applicants have been approved after demonstrating high spending on Amex’s global products (e.g., Amex Platinum Europe, Amex Business Gold).
Q: What’s the best way to increase my chances of approval?
A: If you’re serious about qualifying for the black card American Express qualifications, focus on:
- Maximize Amex Platinum spending: Aim for $50,000+ annually on travel, dining, and entertainment using Amex’s existing products.
- Engage with concierge: Use the Platinum Card’s concierge for high-end bookings (e.g., private tours, luxury rentals) to build a positive service record.
- Network with holders: Attend Amex Platinum events or join elite travel clubs (e.g., NetJets, The Explorers Club) where black card holders gather.
- Maintain flawless credit: Even a single late payment can delay or derail approval.
Q: Is the black card worth the $5,000 fee?
A: For most applicants, the answer is no—unless you’re a high-frequency traveler or luxury consumer. The perks (e.g., lounge access, dining credits) are valuable, but the real benefit is the network. Black card holders often get invites to exclusive events, introductions to private jet operators, and access to experiences (e.g., private island stays, VIP concert access) that aren’t available to Platinum members. If you’re not using the card strategically (e.g., booking high-end travel, leveraging concierge for business), the fee may not justify the cost.
