
Where It All Began
The origins of modern wealth-building strategies trace back to the 1970s, when the first quant funds began exploiting market inefficiencies. But it wasn’t until the 2000s that the tools became accessible to the average investor. The rise of index funds, robo-advisors, and peer-to-peer lending platforms lowered the barrier to entry. What started as a niche practice—hedge fund managers using leverage to outperform benchmarks—became a blueprint for retail investors. The early signs were subtle. In 2012, the launch of crowdfunding platforms like Kickstarter revealed that non-accredited investors could fund ventures and earn equity-like returns. By 2015, platforms like RealtyMogul and Fundrise allowed individuals to invest in commercial real estate with as little as $500. These weren’t just new products; they were proof that wealth accumulation could be democratized—if investors were willing to move beyond the 60/40 portfolio and embrace higher-conviction strategies.The Early Signs
The shift from passive to active wealth-building accelerated when the first generation of "financial independents" began sharing their playbooks. In 2016, a Reddit thread titled "How I Turned $50K into $500K in 3 Years" went viral—not because the numbers were extraordinary, but because the methodology was replicable. The author didn’t rely on a single asset class; he layered dividend growth stocks, rental arbitrage, and a side business that scaled with his time. The key insight? Net worth growth in 2025 isn’t about picking one strategy—it’s about stacking them. By 2018, the data became undeniable. A study by the Federal Reserve found that the top 10% of households derived nearly half their wealth from business equity and real estate, not just wages. The implication was clear: traditional savings alone wouldn’t cut it. Those who wanted to increase net worth effectively in 2025 would need to think like owners, not just employees.The Turning Point
The catalyst was the 2020 market volatility. While the S&P 500 recovered swiftly, many investors realized their portfolios were still exposed to single-point failures—overconcentration in tech, lack of inflation hedges, or illiquid assets that couldn’t be sold in a crisis. The turning point wasn’t the crash itself but the realization that resilience required diversification beyond the usual suspects. The shift toward alternative assets—private equity, venture capital, and even crypto—wasn’t about chasing returns. It was about asset protection and liquidity control. Investors who’d once parked cash in CDs or money market funds began allocating to high-yield private credit funds, where returns hovered around 8-10% with lower volatility than public markets."The biggest mistake people make is treating wealth like a destination. It’s a system. In 2025, the systems that work are the ones that adapt to structural changes—not the ones that cling to what worked in 2010." — James Altucher, investor and author of Choose Yourself
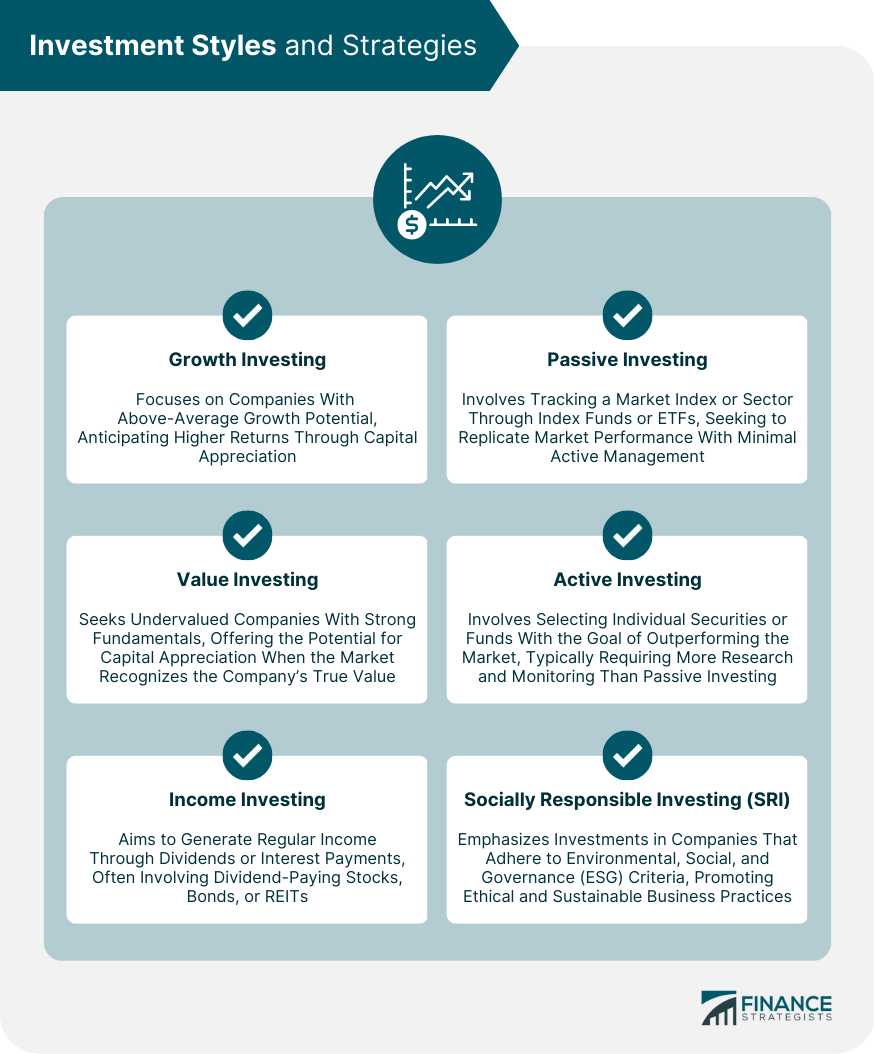
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2015–2017 | Rise of fractional investing (e.g., Stockpile, Robinhood) and automated tax optimization (e.g., Betterment’s tax-loss harvesting). The first wave of "micro-investing" apps emerged, lowering the barrier to entry for small-dollar investors. |
| 2018–2020 | Alternative asset platforms (RealtyMogul, Fundrise) gained traction, allowing retail investors to access private real estate and venture capital. The first AI-driven portfolio managers (e.g., Wealthfront’s automated rebalancing) proved that algorithms could outperform human discretion in certain cases. |
| 2021 | Inflation reared its head, exposing the flaws in traditional 60/40 portfolios. Investors pivoted to TIPS, gold, and inflation-linked REITs. The first crypto ETFs (like Bitwise’s) launched, though adoption remained niche. |
| 2022–2023 | Liquidity crises in private markets (e.g., venture capital dry powder) forced investors to seek secondary market solutions (e.g., Forge Global). The first generative AI-driven investment tools (e.g., AlphaSense for research) emerged, though regulatory hurdles limited mainstream use. |
| 2024–2025 | Structural shifts in asset allocation: The 60/40 portfolio is now a minority strategy. Instead, investors are layering:
|
Lessons From the Journey
- Tax efficiency is non-negotiable. Even a 1% tax drag on a $1M portfolio costs $10,000 annually. Strategies like roth conversions, municipal bonds, and tax-loss harvesting can shave 0.5–1.5% off effective returns.
- Leverage isn’t just for the rich. Margin accounts, HELOCs, and private credit funds allow investors to amplify returns—but only if deployed with strict risk management. The sweet spot is 20–30% leverage on assets with stable cash flow.
- Asset velocity matters more than asset size. A $50K side hustle that scales to $500K in three years beats a $500K investment that stagnates. Reinvestment speed is the hidden lever of wealth-building.
- Diversification isn’t about holding more—it’s about holding the right things. A portfolio with 10 uncorrelated assets (e.g., stocks, real estate, private equity, crypto, commodities) outperforms one with 50 correlated ones.
- Behavioral discipline trumps strategy. The average investor underperforms the S&P 500 by 3–5% annually due to emotional decisions. Automated rebalancing, stop-loss rules, and dollar-cost averaging mitigate this.
- The future belongs to those who own the tools. Whether it’s AI-driven alpha generation or blockchain-based liquidity, investors who control the infrastructure (e.g., staking crypto, running a node) gain asymmetric upside.
Where Things Stand Today
As of 2025, the wealth-building landscape is fragmented but more efficient. The days of "set it and forget it" portfolios are over. Instead, investors are actively managing their allocations—shifting between growth, income, and preservation based on macro trends. The most successful strategies aren’t about picking the next Bitcoin or meme stock; they’re about systematic edge creation. What’s clear is that effective strategies to increase net worth in 2025 require three things: 1. A multi-asset-class approach (no single asset should exceed 30% of the portfolio). 2. Leverage applied judiciously (not for speculation, but for capital efficiency). 3. A focus on cash flow and reinvestment (wealth compounds when profits are immediately redeployed). The biggest mistake? Assuming that past performance predicts future results. The investors who’ll thrive in 2025 are the ones who adapt their playbook—not the ones who repeat it.
Conclusion
Wealth isn’t built in straight lines. It’s built in cycles of adaptation. The investors who’ll see their net worth grow meaningfully by 2030 won’t be the ones who followed the crowd in 2020. They’ll be the ones who reverse-engineered the mechanics of compounding, optimized for tax efficiency and liquidity, and stacked high-conviction strategies without overconcentration. The good news? The tools are available. Fractional investing, automated tax optimization, and AI-driven portfolio management mean that even a $50K starting point can be scaled aggressively if executed correctly. The bad news? Discipline is the only real competitive advantage. The market rewards those who stay the course—not those who chase the next big thing. For those willing to treat wealth-building as a science, the next five years will be the most lucrative in decades.Comprehensive FAQs
Q: What’s the single biggest mistake people make when trying to increase net worth?
The biggest mistake is overemphasizing savings rate over asset allocation. Saving 50% of your income is impressive, but if that money sits in a savings account earning 0.5% APY, you’re losing ground to inflation. Effective strategies to increase net worth in 2025 require reinvesting aggressively—whether in stocks, real estate, or a side business—while minimizing drag from fees and taxes.
Q: Should I focus on stocks, real estate, or crypto in 2025?
There’s no one-size-fits-all answer, but the optimal approach is diversification. A balanced portfolio might look like:
- 60% equities (ETFs like VTI, QQQ, or sector-specific plays like ARKK for innovation).
- 20% real estate (REITs or direct ownership via crowdfunding).
- 10% crypto (Bitcoin as digital gold, Ethereum for DeFi exposure).
- 10% alternatives (private credit, venture capital, or commodities like gold).
Q: How much should I allocate to leverage?
Leverage can amplify returns, but it’s a double-edged sword. For most investors, 20–30% leverage (via margin accounts, HELOCs, or private credit funds) is a sweet spot—enough to boost returns without catastrophic risk. Never leverage more than you can afford to lose, and only use it on assets with stable cash flow (e.g., rental properties, dividend stocks).
Q: Is a side hustle worth it for increasing net worth?
Absolutely—if it’s scalable and reinvested. A side hustle that generates $10K/month in cash flow can be reinvested into assets (e.g., buying a rental property or funding a business). The real multiplier comes when the hustle compounds: turning $50K in revenue into $500K in assets over three years. Focus on businesses with high margins and low capital requirements (e.g., SaaS, digital products, or service-based models).
Q: How do I protect my wealth from inflation?
Inflation erodes purchasing power, so hedging is critical. The best inflation-proof assets in 2025 are:
- TIPS (Treasury Inflation-Protected Securities) – Direct hedge against CPI.
- Real estate – Rents and property values historically outpace inflation.
- Commodities (gold, silver, oil) – Tangible assets that retain value.
- Inflation-linked REITs – Companies that pass through rent increases.
Q: Should I use a robo-advisor or manage my own portfolio?
Robo-advisors (e.g., Betterment, Wealthfront) are great for tax efficiency and rebalancing, but they lack conviction. If you want higher returns, you’ll need to override the default allocations—e.g., increasing exposure to small-cap stocks or private equity. Best approach? Use a robo-advisor for core holdings (60%) and manage the remaining 40% actively (high-conviction stocks, alternatives).
Q: What’s the role of AI in wealth-building strategies for 2025?
AI is transforming three key areas:
- Alpha generation – Tools like AlphaSense use NLP to identify mispriced stocks faster than humans.
- Portfolio optimization – AI can dynamically rebalance based on macro trends (e.g., shifting to bonds during inflation spikes).
- Tax efficiency – Automated tax-loss harvesting and Roth conversion timing can save thousands annually.
Q: How often should I review and adjust my portfolio?
Quarterly reviews are ideal—but only if you’re making data-driven changes. Many investors over-trade, leading to higher fees and taxes. Instead, set rebalancing triggers (e.g., "Sell 10% if an asset exceeds 30% of the portfolio") and stick to them. The goal isn’t to time the market but to optimize for long-term growth.
