The first time Mayer Amschel Rothschild set foot in Frankfurt in 1744, the city was a modest trading hub, its streets lined with merchants and money changers who operated in the shadows of imperial decrees. He was a Jew in a world where financial success for his community was tightly circumscribed—yet within decades, his descendants would reshape global capitalism. By the time the 19th century dawned, the Rothschild name had become synonymous with
the total net worth of the Rothschild family, a fortune so vast it could fund armies, influence monarchs, and outlast empires. The family’s rise wasn’t just about money; it was about control. They didn’t merely accumulate wealth—they engineered systems where wealth flowed toward them, generation after generation.
Today, the Rothschilds remain a study in financial endurance. Their empire spans private banks, art collections, real estate, and strategic investments across Europe, the Americas, and beyond. Unlike modern billionaires who flaunt their fortunes, the Rothschilds have long operated with discretion, their influence measured in whispers rather than headlines. Yet their
wealth accumulation strategy—rooted in risk management, political leverage, and intergenerational planning—offers lessons even in an era of algorithmic trading and cryptocurrency. The question isn’t just how rich they are, but how they’ve sustained that dominance for over 250 years.
Where It All Began

The Rothschild story begins with Mayer Amschel Rothschild, a pawnbroker’s son who transformed Frankfurt’s Jewish ghetto into a financial command center. His breakthrough came when he secured a monopoly on coinage for the Holy Roman Empire, a lucrative deal that allowed him to mint money—literally. But it was his five sons who scattered across Europe that turned the family into a continental powerhouse. Nathan in London, James in Paris, Solomon in Vienna, Carl in Naples, and Amschel in Frankfurt each became nodes in a vast, decentralized network. This structure wasn’t just logistical; it was a survival tactic. When Napoleon’s armies marched, one Rothschild branch could fund resistance while others remained neutral, ensuring the family’s continuity.
The early signs of their ascendancy were subtle but unmistakable. By the 1810s, the Rothschilds had cornered the market in British government bonds, effectively underwriting the cost of the Napoleonic Wars. Their ability to move capital faster than any other institution turned them into the world’s first true
global financial arbitrageurs. The family’s reputation for discretion was equally critical—when the Bank of England faced a liquidity crisis in 1825, it was a Rothschild who quietly bailed them out, saving the institution without fanfare. This was the birth of the Rothschild brand: invisible yet indispensable.
The Turning Point
The 19th century was when the Rothschilds transitioned from wealthy bankers to architects of modern finance. Their
total net worth ballooned not just from traditional lending, but from their role in financing infrastructure—railroads, telegraph lines, and even the Suez Canal. The family’s political connections were unparalleled; they dined with kings, married into aristocracy, and advised governments on debt restructuring. By the time Baron James de Rothschild hosted the first international financial conference in 1867, the family’s influence was undeniable.
What changed wasn’t just the scale of their wealth, but the nature of it. The Rothschilds stopped being creditors to nations and started shaping the rules of capitalism itself. Their private bank,
Rothschild & Co., became a model for modern investment banking, blending philanthropy with profit. The turning point wasn’t a single event, but a series of calculated moves—diversifying into art, land, and even wine (Château Lafite Rothschild remains one of the world’s most prestigious vineyards). Their ability to anticipate economic shifts, from the Industrial Revolution to the rise of the stock market, ensured that their fortune remained untouchable.
"Wealth is not measured in gold, but in the ability to command it." — Attributed to a Rothschild family member, c. 1850.
The Build-Up, Year by Year
|
Period | Key Developments | Impact on Wealth |
|--------------------------|-----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|-----------------------------------------------------------------------------------------------------------|
| 1744–1815 | Mayer Amschel’s pawnbroker shop → coinage monopoly → five sons establish branches across Europe. Funded Napoleon’s wars, then his downfall. | Transition from local merchant to continental financiers. |
| 1815–1870 | Underwrote British debt, built railways, acquired vineyards (Lafite Rothschild). Married into European nobility. | Total net worth grew exponentially; became the backbone of 19th-century capitalism. |
| 1870–1945 | Survived wars, diversified into mining, textiles, and real estate. Baron Edmond de Rothschild became a Zionist pioneer, investing in Palestine’s infrastructure. | Weathered two world wars; wealth preserved through strategic asset allocation. |
Lessons From the Journey
The Rothschilds’ longevity isn’t accidental. Their strategy includes:
-
Decentralization: No single branch controls everything—risk is distributed.
- Political Neutrality: They’ve avoided overtly siding with any faction, ensuring survival through crises.
- Liquidity First: Always maintain cash reserves to exploit opportunities others can’t.
- Legacy Over Short-Term Gains: Philanthropy (e.g., Rothschild Foundation) reinforces social capital.
- Discretion: Their wealth is a tool, not a trophy—flaunting it invites regulation or envy.
- Adaptability: From coinage to cryptocurrency, they’ve always anticipated the next financial frontier.
Where Things Stand Today
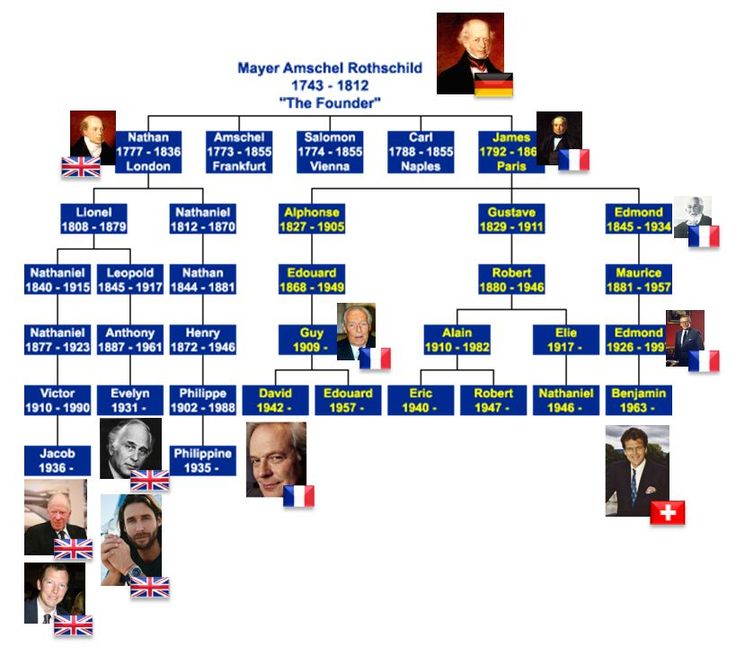
The Rothschilds remain one of the world’s most discreetly wealthy families, though pinpointing their current total net worth is impossible without insider access. Estimates place their combined holdings—spanning private banks, art (including works by Monet, Picasso, and Rembrandt), real estate (from London’s New Court to Parisian châteaux), and strategic investments in technology and renewable energy—in the hundreds of billions. What’s clear is that they’ve avoided the pitfalls of modern wealth: no public feuds, no reckless acquisitions, and no reliance on a single industry.
Their modern empire is a study in quiet dominance. Rothschild & Co. still operates as a private bank, advising sovereign wealth funds and high-net-worth clients. The family’s art collection is among the most valuable in the world, with pieces rarely sold. Their influence extends to think tanks, universities, and even space exploration (Rothschild Foundation supports Breakthrough Initiatives). The key to their endurance? They’ve never treated wealth as an end—only as a means to preserve power.
Conclusion
The Rothschild family’s story is more than a tale of money; it’s a masterclass in financial engineering across centuries. Their total net worth isn’t just a number—it’s a living entity, shaped by war, innovation, and an unshakable belief in their own relevance. In an era where fortunes rise and fall with market cycles, the Rothschilds have done the opposite: they’ve built a machine that converts risk into certainty.
Their legacy isn’t just in the vaults of New Court or the vineyards of Bordeaux, but in the systems they helped create. Central banking, modern equity markets, even the concept of a "global economy"—all bear their imprint. The question for the 21st century isn’t whether the Rothschilds will remain wealthy, but how they’ll adapt to a world where traditional finance is being rewritten by algorithms and decentralized ledgers. One thing is certain: if history is any guide, they’ll be ready.
Comprehensive FAQs
#### Q: How do the Rothschilds compare to other ultra-wealthy dynasties like the Rockefellers or the Waltons?
The Rothschilds’ advantage lies in their diversification and longevity. While the Rockefellers built their fortune on Standard Oil and the Waltons on retail (Walmart), the Rothschilds have never relied on a single industry. Their wealth is spread across banking, art, real estate, and strategic investments, making them less vulnerable to sector-specific downturns. Additionally, their political neutrality—avoiding overt ties to any government or corporation—has allowed them to operate across borders without the scrutiny faced by other dynasties.
#### Q: Are the Rothschilds still active in banking today?
Yes, but in a highly controlled manner. Rothschild & Co. remains one of the world’s oldest private banks, serving sovereign wealth funds, high-net-worth individuals, and institutional clients. Unlike commercial banks, it doesn’t take retail deposits and operates with extreme discretion. The family also maintains stakes in Rothschild Investment Corporation and other vehicles, but their involvement is largely behind the scenes.
#### Q: How do they manage to keep their wealth private?
The Rothschilds employ a mix of legal structures, offshore entities, and generational trust arrangements. Many of their assets are held in private foundations or family-limited partnerships, which restrict transparency. Their art collection, for example, is often leased to museums rather than sold, keeping transactions out of public records. Additionally, their decentralized ownership—spread across branches in London, Paris, Zurich, and elsewhere—makes it difficult to trace the full extent of their holdings.
#### Q: What’s the biggest threat to the Rothschild fortune today?
The biggest risks are regulatory scrutiny and digital disruption. As governments crack down on tax evasion and money laundering, the Rothschilds’ use of offshore structures could come under pressure. Meanwhile, the rise of blockchain and decentralized finance (DeFi) challenges traditional banking models. That said, the family has already shown adaptability—some branches are exploring crypto assets and fintech, ensuring they stay ahead of the curve.
#### Q: Do the Rothschilds still control the same level of power as in the 19th century?
Their influence is different, not diminished. In the past, they could single-handedly stabilize economies; today, their power is more subtle. They still move capital at scale, advise governments, and shape policy through think tanks and philanthropy. However, the financial system is now more fragmented, with central banks and sovereign wealth funds competing for their role. That said, no other family has their combination of historical capital, global network, and discretion.
#### Q: How do they pass wealth across generations without triggering taxes or legal challenges?
The Rothschilds use a combination of trusts, dynastic trusts (where assets pass without probate), and gifting strategies within legal limits. Many of their European branches operate under civil law jurisdictions (like Switzerland or Luxembourg), which offer more flexibility in wealth transfer. They also employ philanthropic vehicles—such as the Rothschild Foundation—to move assets into charitable structures, which can reduce taxable exposure.