
Breaking Down the Numbers
The financial stakes of nickel stainless production are less about headline-grabbing price swings and more about the cumulative impact of incremental changes. Nickel’s share of stainless steel costs can range from 20% to 40%, depending on the alloy grade. When LME nickel futures surged past $100,000 per tonne in early 2022, mills worldwide scrambled to adjust formulations, sometimes substituting manganese or nitrogen to reduce nickel dependency. The shift wasn’t uniform—high-end applications like aerospace maintained premium nickel content, while consumer goods manufacturers adopted leaner alloys where possible. This bifurcation reflects a broader industry trend: the erosion of one-size-fits-all solutions. Nickel stainless is no longer a monolithic category but a spectrum of trade-offs. For instance, replacing 2% nickel with nitrogen in Type 430 can cut costs by roughly 10-15% without sacrificing basic corrosion resistance. However, such substitutions come with caveats—weldability may degrade, and long-term performance in aggressive environments could suffer. The numbers don’t lie, but the interpretations do.The Verified Baseline
Publicly available data confirms that nickel stainless production accounts for roughly 60% of global stainless steel output, with Europe and Asia leading consumption. The European Union’s strict regulations on chromium VI have accelerated demand for nickel-rich alloys, as they offer better compliance with REACH standards. Meanwhile, China’s dominance in stainless steel production—nearly 60% of global capacity—has made it the de facto arbiter of nickel stainless supply chains. Trade data shows that nickel imports into China for stainless steel manufacturing have remained resilient, even during price volatility, though exact figures are obscured by state-controlled reporting. What’s undeniable is the material’s endurance in critical sectors. The aerospace industry, for example, continues to specify nickel stainless for components exposed to jet fuel and high temperatures, with no viable alternatives in sight. Similarly, the medical device sector relies on high-nickel alloys for biocompatibility, despite the added cost. These applications represent the "non-negotiable" segment of the market, where performance outweighs price considerations.What the Estimates Suggest
Industry estimates suggest that the cost premium for nickel stainless over standard grades could widen in the coming years, particularly if nickel prices remain elevated. Analysts at CRU Group have projected that stainless steel producers may need to absorb margins of 15-20% higher than pre-2022 levels to maintain profitability, assuming nickel stays above $25,000 per tonne. This pressure is pushing some manufacturers toward regional sourcing—Europe, for instance, is exploring domestic nickel production to reduce reliance on Indonesia and Russia, though scaling up such operations will take years. Speculation also abounds about the long-term viability of nickel stainless in green energy applications. As hydrogen fuel cells and offshore wind turbines become more prevalent, the demand for corrosion-resistant materials could surge. However, the industry faces a Catch-22: nickel is a critical component of both stainless steel and lithium-ion batteries, creating potential bottlenecks. Some estimates place the additional demand for nickel stainless in renewable energy at around 5-10% of current usage by 2035, though this depends heavily on policy incentives and technological breakthroughs in battery recycling.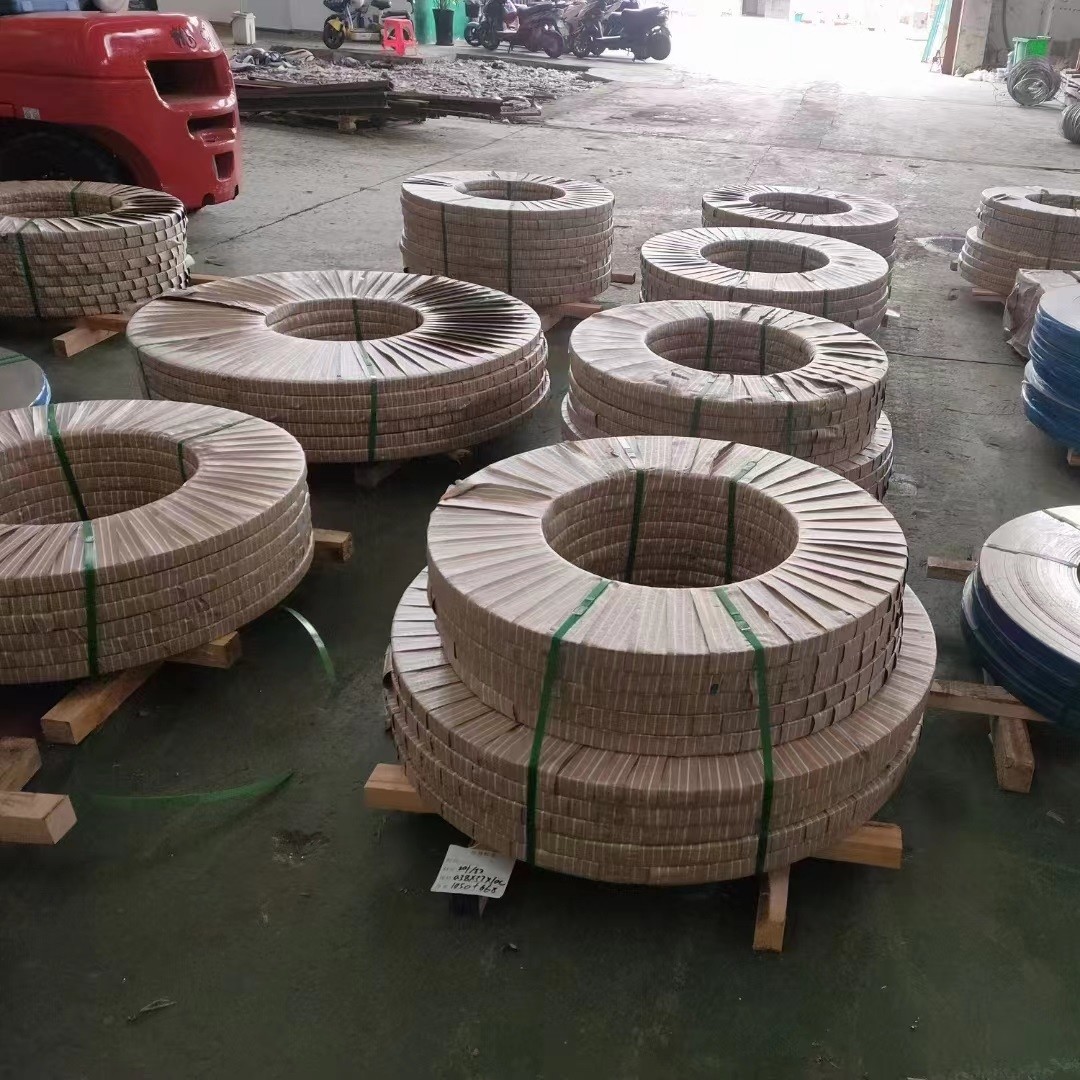
Case Study: A Closer Look
ThyssenKrupp’s decision to pause nickel stainless production at its German mill in 2023 serves as a microcosm of the industry’s challenges. The move wasn’t about nickel stainless being obsolete—it was about survival. With energy costs soaring and nickel prices unpredictable, the company pivoted to lower-nickel alloys for automotive clients while maintaining high-grade production for niche markets. The shift required retraining workers, retooling lines, and renegotiating contracts with suppliers. Yet the gamble paid off: by 2024, ThyssenKrupp reported stabilizing its stainless steel margins, albeit with a reduced reliance on premium nickel stainless grades. The case underscores a harsh truth: flexibility is the new currency. Companies that can quickly adapt formulations—whether by tweaking nickel content or exploring substitutes—are the ones thriving. This adaptability extends beyond production. For example, Outokumpu, a Finnish stainless steel leader, has invested in digital twins to simulate how different alloy compositions perform under varying conditions. The goal isn’t to eliminate nickel stainless but to use it more strategically, ensuring it’s deployed where its unique properties are irreplaceable."Nickel stainless isn’t going away, but its role is evolving. We’re moving from a mindset of 'how much nickel can we use?' to 'where does nickel add the most value?' That shift is forcing innovation across the supply chain." — Antti Rantamäki, Outokumpu’s Head of R&D
| Factor | Estimated Impact |
|---|---|
| Nickel price volatility | Forces mills to adopt dynamic pricing models, with some passing costs to end-users. |
| Substitution with nitrogen/manganese | Reduces corrosion resistance in aggressive environments by up to 15% in certain alloys. |
| Regional nickel sourcing | Increases lead times by 30-50% for European producers relying on domestic mines. |
| Automotive lightweighting demand | Drives up demand for high-nickel alloys in EV components, offsetting declines in traditional sectors. |
| ESG compliance pressures | May lead to 10-20% higher costs for nickel stainless if producers adopt stricter sustainability certifications. |
What This Means Going Forward
The future of nickel stainless isn’t binary—it’s layered. For industries where performance is non-negotiable, such as aerospace or medical devices, the material will remain a cornerstone. But for sectors willing to compromise, alternatives like duplex stainless steel (with lower nickel) or titanium alloys are gaining traction. The key variable isn’t whether nickel stainless will disappear, but how its usage becomes more intentional. This means better forecasting, smarter alloy design, and a willingness to accept that "good enough" might sometimes suffice. What’s clear is that the material’s trajectory is now tied to macroeconomic forces beyond metallurgy. Geopolitical tensions, climate policies, and technological disruptions will all shape its evolution. The companies that navigate this landscape successfully will be those that treat nickel stainless not as a static product but as a dynamic tool—one that can be optimized, substituted, or even phased out in favor of emerging solutions when the cost-benefit equation shifts.
Conclusion
Nickel stainless steel has spent decades as the unsung hero of modern industry, its contributions often overshadowed by the end products it enables. Yet its current challenges—rising costs, supply chain fragility, and the push for sustainability—have forced a reckoning. The material isn’t in crisis; it’s in transition. The question for manufacturers, policymakers, and consumers alike isn’t whether nickel stainless will endure, but how its legacy will be rewritten in an era of scarcity and innovation. One thing is certain: the era of treating nickel stainless as a commodity is over. From now on, its value will be measured not just in tons produced or dollars spent, but in its precision—where it’s used, how it’s optimized, and what it enables. That precision may well define the next chapter of industrial progress.Comprehensive FAQs
Q: Can nickel stainless be recycled without losing its properties?
A: Yes, but with caveats. Nickel stainless retains most of its original characteristics through recycling, though repeated melting can degrade certain mechanical properties. The process is energy-intensive, however, and economic viability depends on scrap availability. High-grade alloys like Type 316 are more commonly recycled than leaner grades due to their retained value.
Q: Are there nickel-free alternatives to stainless steel?
A: Several exist, but each comes with trade-offs. Titanium offers excellent corrosion resistance but is costly and difficult to work with. Aluminum alloys are lighter but lack the strength of stainless steel in high-temperature applications. For food-grade uses, some producers use chromium-free stainless steel (e.g., ferritic grades), though these may not meet medical or aerospace standards.
Q: How does nickel stainless compare to regular stainless steel in terms of cost?
A: The difference can be significant. Regular stainless steel (e.g., Type 430) may cost $1.50–$2.50 per kilogram, while high-nickel alloys like Type 316 can exceed $3.00–$5.00/kg, depending on nickel prices. The gap narrows for lower-nickel grades but widens in specialized applications where performance justifies the premium.
Q: Is nickel stainless safe for food and medical use?
A: Yes, provided it meets relevant standards (e.g., FDA, ISO 10993 for medical devices). Nickel stainless alloys like Type 304 and 316 are widely used in food processing and surgical tools due to their biocompatibility and resistance to contamination. However, some individuals may experience nickel allergies, prompting manufacturers to offer nickel-reduced alternatives in consumer products.
Q: What industries rely most heavily on nickel stainless?
A: Aerospace, chemical processing, and medical devices are the top sectors. Aerospace uses it for jet engine components and structural parts, while chemical plants depend on it for tanks and pipes exposed to corrosive substances. The medical industry prefers nickel stainless for its sterilizability and durability in surgical instruments.
Q: How is the nickel shortage affecting stainless steel production?
A: The shortage has led to production rationing, particularly in Asia, where mills have prioritized contracts with long-term clients. Some producers have temporarily shifted to lower-nickel alloys or delayed expansions. The impact is most acute in high-end applications, where substitutes aren’t readily available, while consumer-grade stainless steel has seen more stable supply.
Q: Can nickel stainless be used in renewable energy infrastructure?
A: Absolutely, though its role is evolving. Offshore wind turbines use nickel stainless for corrosion-resistant components like bolts and fasteners. In hydrogen fuel cells, it’s being explored for bipolar plates, though cost remains a barrier. The challenge lies in balancing performance with the need for scalable, affordable materials in rapidly growing green energy sectors.
