Where It All Began
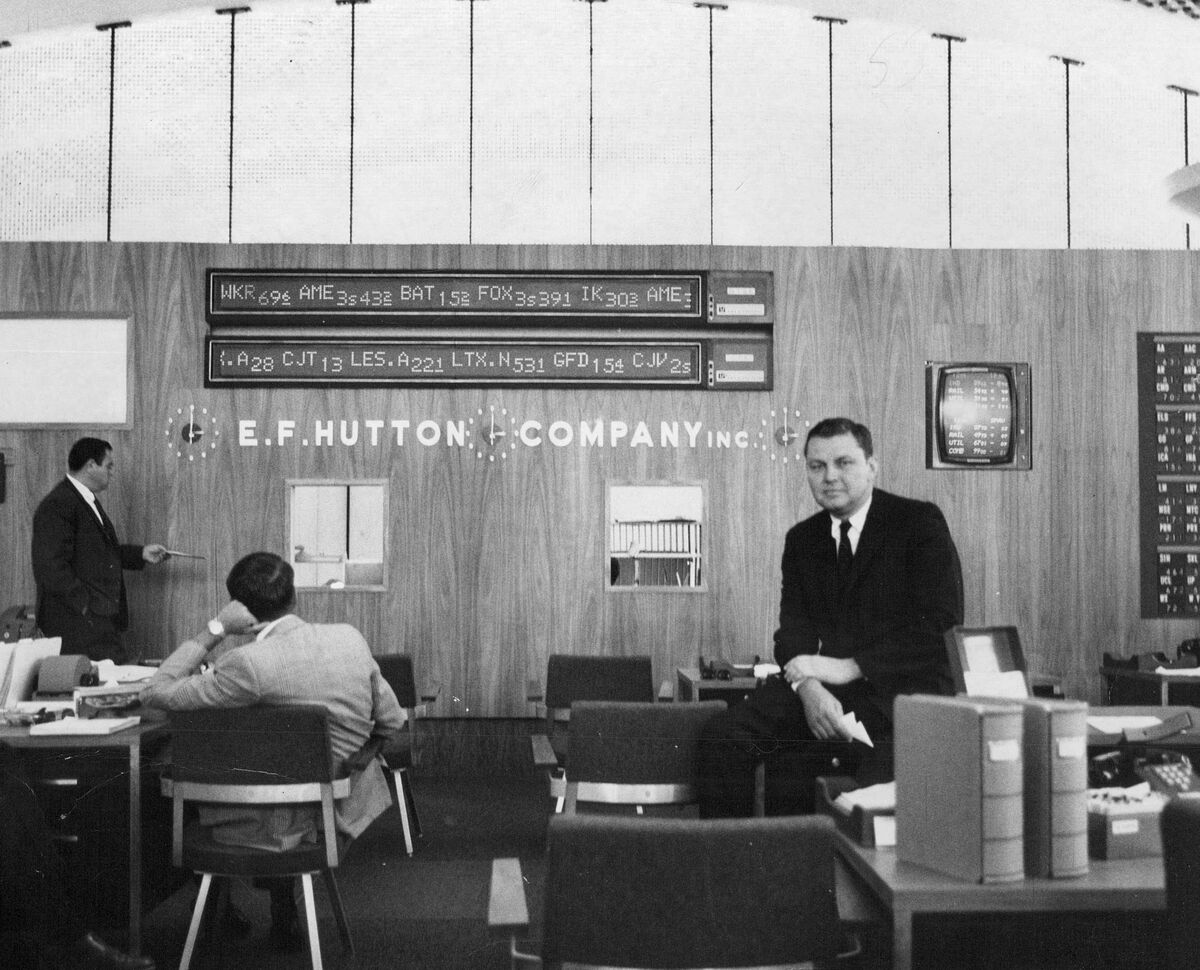
EF Hutton’s origins trace back to 1904, when Edward Francis Hutton—a former stockbroker with a knack for spotting opportunities—founded the firm in Boston. What started as a modest operation quickly grew into a regional powerhouse, known for its aggressive trading strategies and deep ties to New England’s industrial elite. By the 1960s, the firm had expanded nationally, leveraging its reputation for bold moves in the market. The name "EF Hutton" became synonymous with a brokerage that didn’t just follow trends—it set them. The early signs of its dominance were undeniable. Under the leadership of figures like William Donaldson, who later became SEC chairman, EF Hutton cultivated an image of infallibility. Its advertisements, featuring a confident voiceover declaring, "When EF Hutton talks, people listen," weren’t just marketing—they were a promise. Clients, from small investors to Fortune 500 CEOs, trusted the firm’s judgment. By the mid-1970s, EF Hutton’s net worth was estimated to be in the billions, a reflection of its market influence and client base. But beneath the surface, the firm was playing a dangerous game: one where leverage and reputation were treated as interchangeable assets.The Early Signs
The first red flags appeared in the late 1970s, as EF Hutton’s growth outpaced its risk management. The firm had built its empire on the back of aggressive trading, often using client funds to finance speculative bets. While this strategy yielded short-term profits, it also created a house-of-cards scenario where losses could spiral uncontrollably. Regulators began to take notice, but the firm’s political connections—including ties to key figures in Washington—allowed it to evade scrutiny for years. Then came the turning point: a series of high-profile losses that exposed the firm’s vulnerabilities. In 1986, EF Hutton’s trading desk suffered a devastating blow when a single bad bet on a commodities futures contract wiped out hundreds of millions in client funds. The firm’s leadership, rather than admitting fault, doubled down on deception. Internal documents later revealed that EF Hutton had been falsifying financial statements to mask its true financial health. The lie was unsustainable—and when it collapsed, it took the firm with it.The Turning Point
The final straw came in January 1987, when EF Hutton’s parent company, Shearson Loeb Rhoades, announced it would no longer support the brokerage. The move was a death knell. Overnight, EF Hutton’s net worth—once a source of envy—was reduced to a liability. The firm’s collapse sent shockwaves through Wall Street, not just because of its size, but because it symbolized the dangers of unchecked ambition in finance. The fallout was immediate. Clients fled, lawsuits piled up, and the firm’s once-impeccable reputation was in tatters. What had been a multibillion-dollar enterprise was sold off in pieces, with Shearson absorbing its assets at a fraction of their former value. The scandal also led to criminal charges against key executives, including former CEO Donaldson, who pleaded guilty to securities fraud. The case became a textbook example of how a brokerage’s net worth could be eroded by a single misstep—when trust was the only real currency."When EF Hutton talks, people listen." —The firm’s iconic tagline, now a bitter irony.
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1960s–1970s | EF Hutton expands nationally, leveraging its reputation for bold trading. Net worth swells as client base grows, but risk management lags behind growth. |
| 1980–1985 | Aggressive trading leads to high-profile losses. Regulatory scrutiny intensifies, but political connections shield the firm from immediate consequences. |
| 1986–1987 | Commodities bet collapses, exposing financial mismanagement. Shearson Loeb Rhoades cuts ties, triggering the firm’s collapse. Net worth evaporates as assets are liquidated. |
Lessons From the Journey
The EF Hutton saga offers six critical lessons for any financial institution—or individual investor—today: - Reputation is an asset, but it’s not a shield. EF Hutton’s brand was its greatest strength, but it became its undoing when trust was broken. - Leverage amplifies both gains and losses. The firm’s aggressive trading strategies worked until they didn’t—and when they failed, the consequences were catastrophic. - Regulatory blind spots can be fatal. Political connections delayed accountability, but they couldn’t prevent the inevitable collapse. - Transparency is non-negotiable. The firm’s attempts to hide losses only deepened the crisis when the truth emerged. - Market cycles don’t care about legacy. Even the most storied firms are vulnerable to systemic risks beyond their control. - The cost of hubris is always higher than the reward. EF Hutton’s downfall wasn’t just financial—it was a cautionary tale about the dangers of overconfidence.Where Things Stand Today
Decades after its collapse, EF Hutton’s name still lingers in financial history as a cautionary tale. The firm’s assets were absorbed by Shearson, which later merged into what is now part of Morgan Stanley. While EF Hutton’s net worth is no longer a topic of public fascination, its legacy persists in the way regulators and investors view risk management. For those who remember the era, the story of EF Hutton serves as a reminder that financial empires are built on more than just balance sheets—they’re built on trust, discipline, and an understanding of limits. The firm’s rise and fall also highlight how quickly perceptions can shift. What was once a symbol of invincibility became a footnote in a single generation.
Conclusion
EF Hutton’s net worth story is more than a numbers game—it’s a narrative about power, failure, and the fragility of financial systems. The firm’s collapse wasn’t just about bad trades or poor management; it was about a culture that prioritized image over substance. In an industry where perception often dictates reality, EF Hutton’s downfall remains a stark warning. Today, as markets evolve and new players emerge, the lessons of EF Hutton are just as relevant. The question isn’t whether another firm will face a similar fate—but when, and how the industry will respond. One thing is certain: the ghosts of Wall Street’s past never truly fade.Comprehensive FAQs
Q: What was EF Hutton’s peak net worth?
While exact figures are difficult to pin down due to the firm’s private nature, industry estimates suggest EF Hutton’s net worth peaked in the $2–3 billion range in the late 1970s and early 1980s. This included assets, client funds, and market influence—but not the intangible value of its reputation.
Q: How did EF Hutton’s collapse affect its clients?
Thousands of clients lost money when the firm’s financial mismanagement was exposed. Many faced lawsuits and regulatory actions, while others simply lost access to their funds during the liquidation process. The collapse also led to stricter client protection rules in the brokerage industry.
Q: Were any executives criminally charged?
Yes. Former CEO William Donaldson and other executives pleaded guilty to securities fraud in 1988, marking one of the most high-profile financial crimes of the era. Donaldson served a prison sentence, and the case set a precedent for corporate accountability.
Q: Does EF Hutton still exist today?
No. The firm’s assets were absorbed by Shearson Loeb Rhoades in 1987, which later merged into what is now part of Morgan Stanley. The name "EF Hutton" no longer operates as an independent entity, but its story remains a case study in financial history.
Q: What was the biggest mistake EF Hutton made?
The firm’s fatal flaw was treating its reputation as a substitute for risk management. By leveraging client funds for speculative bets and hiding losses, EF Hutton gambled that its name alone would protect it—until the house of cards collapsed.
