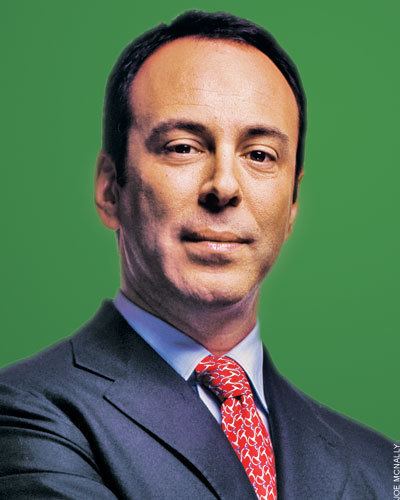
5 Things Worth Knowing About Edward Lampert
The narrative around Edward Lampert is one of contradictions. He is both a savior and a villain, a visionary and a vulture, depending on who you ask. His career trajectory—from a young quant at Salomon Brothers to the architect of Sears’ restructuring—offers a masterclass in how private equity can either revive or dismantle institutions. Yet his methods have drawn scrutiny, particularly in an age where corporate accountability is under increasing pressure. What follows are five critical dimensions of his career that explain why his name still provokes debate.1. The Quant Who Built an Empire
Edward Lampert’s origins trace back to the 1980s, when he was a rising star at Salomon Brothers, trading fixed-income securities with an analytical precision that would later define his investment philosophy. By 1993, he founded ESL Investments, a hedge fund that would become a powerhouse in distressed debt and corporate restructuring. Unlike many of his peers, Lampert didn’t chase flashy IPOs or tech bubbles; instead, he focused on undervalued assets in distress, a strategy that aligned with his background in quantitative modeling. His early successes—including profitable bets on companies like Kmart and Blockbuster—demonstrated an ability to identify structural weaknesses before they became catastrophic. Yet it was his later moves, particularly at Sears, that would test the limits of his approach. Lampert’s strategy at Sears was rooted in the belief that the company’s real estate portfolio was its most valuable asset, a thesis that clashed with the retailer’s fading relevance in an omnichannel world. The outcome—bankruptcy, liquidation, and the loss of tens of thousands of jobs—became a case study in how even the most disciplined financial engineering can fail when confronted with irreversible market shifts.2. The Sears Gambit and Its Aftermath
No single event has defined Edward Lampert’s legacy more than his involvement with Sears. In 2005, Lampert’s ESL Investments took a controlling stake in the struggling retailer, betting that a leaner, asset-focused operation could return it to profitability. For a time, it seemed to work: Sears’ stock rallied, and Lampert’s reputation as a turnaround artist grew. But beneath the surface, the company was hemorrhaging cash, saddled with bloated real estate holdings and a business model that couldn’t compete with Amazon. By 2018, the unraveling was complete. Sears filed for bankruptcy, and Lampert’s vision—centered on monetizing the company’s land and buildings—led to the shuttering of hundreds of stores and the loss of iconic brands like Craftsman and Kenmore. Critics argued that Lampert prioritized short-term gains for creditors over the company’s long-term viability. Supporters countered that he was merely executing on a distressed-debt strategy, one that required tough choices. The bankruptcy court’s eventual decision to liquidate Sears rather than restructure it under Lampert’s plan dealt a blow to his reputation, though he emerged with a reported windfall from the sale of the company’s real estate.3. The Chicago Bulls: Sports as a Side Hustle
While Lampert’s financial maneuvers dominate headlines, his ownership of the Chicago Bulls offers a glimpse into a different facet of his persona. Acquired in 2010, the Bulls were a financial liability when Lampert took over—a team mired in debt, with a roster that included rising stars like Derrick Rose but also systemic issues. Unlike traditional sports owners who chase trophies, Lampert approached the franchise with the same analytical rigor he applied to distressed assets. He slashed payroll, sold underperforming players, and focused on rebuilding through the draft. The strategy paid off in unexpected ways. The Bulls’ resurgence under Lampert’s ownership, culminating in a deep playoff run in 2015, demonstrated that even in sports, his disciplined approach could yield results. Yet his tenure also highlighted tensions between his business mindset and the emotional stakes of sports fandom. When he sold the team in 2020, it was less about financial failure and more about shifting priorities—another chapter in a career where diversification is as much a strategy as it is a lifestyle.4. The Art of the Corporate Raid
Lampert’s playbook extends beyond turnarounds and sports. His investments in companies like Sears, Kmart, and even the Washington Commanders (formerly the Redskins) reveal a pattern: he targets assets with undervalued real estate or intellectual property, then restructures them to maximize liquidity. This approach has drawn comparisons to the aggressive tactics of corporate raiders like Carl Icahn, though Lampert’s methods are often more surgical, focusing on asset stripping rather than hostile takeovers. What sets him apart is his ability to operate within the system while bending its rules. At Sears, for example, he navigated bankruptcy courts to prioritize creditors over unions and employees, a move that sparked legal challenges and public backlash. His ability to leverage regulatory loopholes—such as the use of "pre-packaged" bankruptcy plans—has made him both a feared and a formidable figure in corporate America. The result is a legacy that straddles the line between innovation and exploitation, depending on whose side of the deal you’re on."Lampert’s strategy at Sears wasn’t about saving the company—it was about extracting value from its collapse. That’s the reality of distressed investing, but it’s a reality that doesn’t sit well with the public when the human cost becomes visible." — Former Sears executive, speaking anonymously to Bloomberg in 2019
5. The Man Behind the Deals
Publicly, Edward Lampert is a study in restraint. Unlike the flamboyant figures of Wall Street lore, he avoids interviews, eschews social media, and maintains a low profile despite his influence. This reticence has fueled speculation about his personal motivations. Is he driven by profit, prestige, or something else? His decision to keep ESL Investments private—unlike many hedge funds—suggests a desire to operate without the scrutiny that comes with public markets. Yet his actions speak louder than his silence. From his early days as a quant to his current role as a behind-the-scenes power broker, Lampert’s career reflects a man who thrives in ambiguity. He doesn’t seek the spotlight, but his fingerprints are everywhere: in the boardrooms of failed retailers, in the balance sheets of sports franchises, and in the legal battles that follow his investments. Understanding him requires looking past the headlines and into the systems he navigates—a world where finance, law, and power intersect in ways that are as opaque as they are consequential.
How These Facts Connect
The threads of Edward Lampert’s career weave together into a single, unmistakable pattern: a relentless focus on asset optimization, even at the expense of long-term sustainability. His success at Kmart and early bets on distressed debt proved that his quantitative approach could identify value where others saw only risk. But Sears exposed the limitations of that strategy when market forces—namely, the rise of e-commerce—made traditional retailing obsolete. The contrast between his financial victories and the collapse of Sears underscores a fundamental tension in his philosophy: Can a company be saved by extracting its assets, or does that extraction signal its inevitable demise? Lampert’s foray into sports ownership further illustrates his ability to adapt. The Bulls, like Sears, were a liability when he acquired them, but his disciplined approach to payroll and asset management transformed them into a competitive franchise. This duality—between destruction and creation—is the hallmark of his career. He doesn’t just invest in companies; he reshapes their ecosystems, often leaving behind a trail of winners and losers. The Chicago Bulls’ resurgence, for instance, required sacrificing short-term fan favorites for long-term stability, a trade-off that mirrors his decisions at Sears, where employee layoffs were justified as necessary for creditor recovery. | Dimension | Key Strategy | Outcome | Criticism | Legacy Impact | |-----------------------------|-------------------------------------------|--------------------------------------|----------------------------------------|----------------------------------------| | Distressed Debt Investing | Asset-focused restructuring | Profitable exits (Kmart, early bets) | Sears liquidation, job losses | Redefined distressed investing | | Sears Turnaround | Real estate monetization | Bankruptcy, creditor payouts | Accelerated collapse, union battles | Case study in retail failure | | Chicago Bulls Ownership | Payroll discipline, draft focus | Playoff contention, franchise value | Fan backlash over roster moves | Proved PE logic applies to sports | | Corporate Raiding | Leveraging bankruptcy courts | Creditor prioritization | Legal challenges, public scrutiny | Expanded use of "pre-pack" bankruptcies| | Low-Profile Influence | Private equity, boardroom control | Quiet accumulation of power | Lack of transparency | Shaped industries without headlines | The table above distills Lampert’s career into its essential components. Each row reveals a different facet of his approach, but the common thread is clear: he operates at the intersection of finance and power, where the rules are written by those who can afford to bend them. His ability to navigate these spaces—whether through quantitative models, legal maneuvering, or sports strategy—explains why he remains a polarizing figure. To his supporters, he’s a master of his craft; to his detractors, he’s a symptom of a financial system that prioritizes extraction over sustainability.
Conclusion
Edward Lampert’s story is one of contradictions. He is the architect of some of the most high-profile corporate restructurings of the past two decades, yet his name is inextricably linked to the collapse of Sears. He built a hedge fund empire on the back of distressed assets, only to diversify into sports ownership—a move that suggests his interests extend beyond mere profit. And while he maintains a low public profile, his influence is felt in boardrooms, courtrooms, and the balance sheets of companies he’s touched. What his career ultimately reveals is the tension between efficiency and ethics in modern finance. Lampert’s methods are not inherently unethical; they are, however, a product of a system that rewards short-term gains over long-term viability. His interventions at Sears, for example, were legally permissible but morally fraught, forcing a reckoning with the human cost of financial engineering. Similarly, his ownership of the Bulls demonstrated that even in sports—where passion often trumps profit—his business mindset could deliver results. The question his career poses is whether such strategies are sustainable, or merely a reflection of a broader economic shift toward asset stripping over stewardship. As industries continue to evolve, Lampert’s legacy will be measured not just by his successes but by the lessons his failures impart. His ability to identify undervalued assets and restructure them for profit is undeniable. But the collapse of Sears serves as a cautionary tale about the limits of that approach in an era where traditional business models are being disrupted. For better or worse, Edward Lampert’s story is far from over—and its next chapter may well redefine the boundaries of corporate power.Comprehensive FAQs
Q: How much is Edward Lampert worth?
As of recent estimates, Edward Lampert’s net worth is reported to be in the range of $10–12 billion, though precise figures fluctuate based on market conditions and the value of his private holdings. His wealth stems primarily from ESL Investments and his stake in companies like the Chicago Bulls and the Washington Commanders.
Q: What happened to Sears after Lampert’s involvement?
After filing for bankruptcy in 2018, Sears was liquidated in 2019, with its assets—including real estate and intellectual property—sold off. Lampert’s strategy of prioritizing creditors over the company’s long-term operations was a key factor in its collapse. The liquidation process resulted in the closure of hundreds of stores and the loss of tens of thousands of jobs.
Q: Does Lampert still own the Chicago Bulls?
No, Edward Lampert sold the Chicago Bulls in 2020 to Jerry Reinsdorf and a group of investors. His ownership spanned a decade, during which he transformed the franchise’s financial health while navigating the challenges of rebuilding a competitive roster. The sale marked a shift in his focus, though he retains interests in other sports properties.
Q: How does Lampert’s investment style differ from other hedge fund managers?
Unlike many hedge fund managers who focus on public trading or venture capital, Lampert specializes in distressed debt and corporate restructuring. His approach involves taking control of struggling companies, often through bankruptcy proceedings, and then extracting value—typically through asset sales—rather than attempting to revive the core business. This contrasts with growth-oriented funds that bet on future potential.
Q: Has Lampert faced any major legal challenges?
Yes, Lampert has been involved in several high-profile legal battles, particularly related to his handling of Sears. Creditors and unions challenged his restructuring plan in bankruptcy court, arguing that it unfairly prioritized his interests over those of employees and smaller stakeholders. While he prevailed in most legal disputes, the cases highlighted the contentious nature of his strategies.
Q: What industries is Lampert currently active in?
Beyond his early focus on retail, Lampert’s investments now span sports ownership (Washington Commanders), private equity, and real estate. His hedge fund, ESL Investments, continues to hold stakes in distressed companies, though he has diversified into other sectors where his asset-focused approach can be applied.
Q: Why does Lampert keep such a low public profile?
Lampert’s reticence is likely a strategic choice. By avoiding media attention, he minimizes scrutiny of his investments and maintains flexibility in negotiations. His low-key approach also aligns with his quantitative background—he prefers data-driven decisions over public relations. This contrasts with more visible figures in finance who use their platforms to shape narratives.
