
The Complete Overview of Ralph H. Kiyosaki and His Financial Philosophy
Ralph H. Kiyosaki’s influence stems from his ability to distill complex financial concepts into digestible, often provocative, soundbites. His core argument? That traditional education systems fail to teach the skills needed to build wealth, and that financial literacy is a survival tool in an economy where jobs are increasingly unstable. Unlike conventional financial advisors who emphasize saving and frugality, Kiyosaki advocates for asset acquisition—buying income-generating properties, stocks, or businesses—as the path to true financial freedom. His message resonates particularly with entrepreneurs, real estate investors, and those disillusioned with the 9-to-5 grind. Yet his approach isn’t without detractors. Financial planners and economists often critique his oversimplification of taxes, leverage, and market risks. His emphasis on "cash flow" over net worth, for instance, has led to debates about whether his methods prioritize short-term gains over long-term stability. Kiyosaki himself acknowledges the controversy, frequently stating that his goal isn’t to provide a step-by-step manual but to provoke critical thinking about money. The result? A legacy that’s equal parts revered and reviled, a testament to his ability to spark dialogue even when the answers remain elusive.Historical Background and Evolution
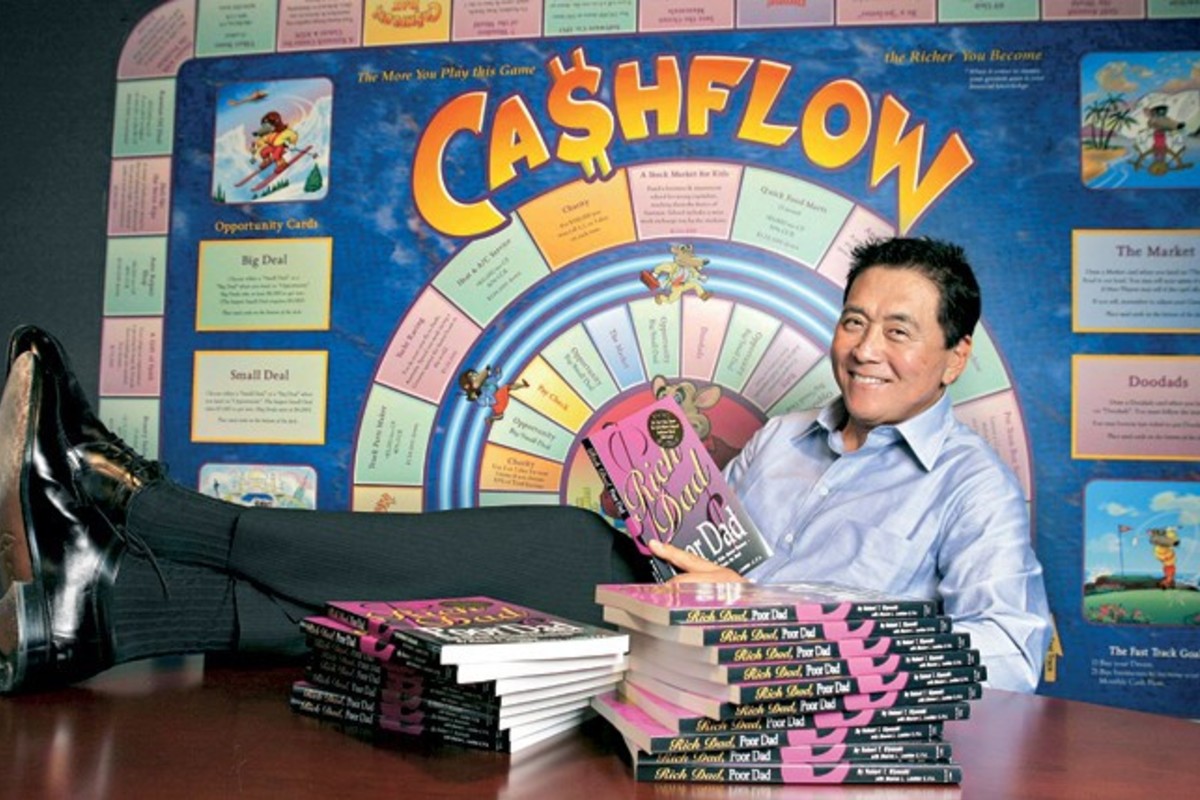
Ralph H. Kiyosaki’s journey began in the 1960s, when he dropped out of the U.S. Marine Corps School of Infantry to pursue entrepreneurship. His early career was eclectic: selling copies of the Washington Post on the streets of Hawaii, founding a company that manufactured surfboards and later sold them to a major retailer, and even working as a salesman for Xerox. It was during this period that he met his "Rich Dad," a man who introduced him to the world of real estate investing and the idea that wealth is built through assets, not liabilities. This encounter became the seed for his later teachings. The turning point came in 1997 with the publication of Rich Dad Poor Dad, a book that became a cultural touchstone. Written in a conversational, almost fable-like style, it positioned financial struggle as a moral dilemma rather than a technical one. The book’s success—spawning sequels, a board game, and a global speaking tour—cemented Kiyosaki as a thought leader. However, his career took a sharp turn in the 2010s, as legal troubles and public backlash over his tax filings (including a 2010 IRS settlement where he agreed to pay $4.5 million in back taxes) tarnished his image. Yet rather than retreat, he doubled down, reframing his controversies as part of his larger narrative about financial resilience.Core Mechanisms: How It Works
At its core, Ralph H. Kiyosaki’s philosophy hinges on three pillars: asset acquisition, financial education, and mindset shifts. His "Rich Dad" teachings argue that most people are trapped in the "employee" mindset, where they trade time for money. In contrast, the "rich" focus on acquiring assets—properties, businesses, or investments—that generate passive income. This isn’t just about real estate; it’s a broader critique of how society defines success. Kiyosaki often uses the analogy of an "E" (employee) versus an "S" (self-employed) versus an "I" (investor), suggesting that true wealth requires moving up this hierarchy. The second mechanism is financial literacy as a tool for empowerment. Unlike traditional finance books that focus on budgeting or retirement planning, Kiyosaki’s approach is aggressive: it’s about understanding how money works in the real world, including the role of taxes, leverage, and market cycles. His "Cashflow Quadrant" model—dividing people into E, S, B (business owners), and I—serves as a framework for readers to assess their own financial trajectory. The third, often overlooked, element is psychology. Kiyosaki frequently emphasizes that fear and scarcity are the biggest barriers to wealth, and that adopting an "abundance mindset" is critical to financial success.Key Benefits and Crucial Impact
The Ralph H. Kiyosaki empire has undeniably shifted how millions view money. His books have been translated into dozens of languages, and his seminars draw crowds in cities from Tokyo to New York. For many, his teachings provided a much-needed wake-up call about the limitations of conventional financial advice. The "Rich Dad" brand has spawned a cottage industry of courses, workshops, and even a Cashflow board game that teaches financial concepts through play. Critics, however, argue that his methods can be risky, particularly for those without prior financial experience or access to capital. What’s undeniable is the Kiyosaki effect on popular culture. Phrases like "don’t work for money" and "the rich don’t work for money" have entered the lexicon of entrepreneurs and side-hustlers alike. His influence extends beyond finance into politics, where his critiques of government policies and central banking have found an audience among libertarian-leaning audiences. Yet for every success story attributed to his methods, there are cautionary tales of individuals who took on excessive debt or made poor investments based on his advice."The single biggest problem in education is that it teaches students how to live in the past, how to be dependent on others, how to follow instead of lead, and how to consume rather than produce." — Ralph H. Kiyosaki, Rich Dad Poor Dad
Major Advantages
- Democratization of financial education: Kiyosaki’s books and courses make complex topics like real estate and taxes accessible to laypeople, filling a gap left by traditional financial institutions.
- Mindset shift: His emphasis on assets over liabilities challenges conventional wisdom, encouraging readers to think differently about money and opportunity.
- Entrepreneurial focus: By prioritizing business ownership and investing, his teachings align with the growing gig economy and the rise of side hustles.
- Global reach: His message transcends borders, resonating with audiences in emerging markets where traditional financial systems are less accessible.
- Cultural relevance: Kiyosaki’s ability to frame financial struggles as moral dilemmas has made his work relatable to a broad audience.
- Adaptability: His brand has evolved with the times, incorporating digital tools, podcasts, and even NFTs to stay relevant in a changing media landscape.
Comparative Analysis
| Ralph H. Kiyosaki | Traditional Financial Advisors |
|---|---|
| Focuses on assets, leverage, and cash flow over net worth. | Prioritizes saving, diversification, and long-term stability. |
| Critiques traditional education systems as obstacles to wealth. | Often aligns with institutional financial education (e.g., 401(k)s, IRAs). |
| Emphasizes real estate and entrepreneurship as primary wealth-building tools. | Typically recommends stocks, bonds, and mutual funds for passive growth. |
| Controversial due to legal issues and aggressive tax strategies. | Generally seen as more conservative and regulated. |
Future Trends and Innovations
As Ralph H. Kiyosaki continues to evolve his brand, his focus has increasingly turned to digital assets and decentralized finance. His recent forays into cryptocurrency and blockchain—including endorsements of Bitcoin and discussions about NFTs—reflect a broader trend among financial gurus to adapt to the digital economy. Yet his core message remains consistent: the future belongs to those who understand how money flows, not just how to save it. The challenge for Kiyosaki and his followers will be navigating an increasingly complex financial landscape where traditional assets like real estate compete with digital currencies and AI-driven investment tools. One potential innovation is the integration of Kiyosaki’s teachings with emerging technologies. For example, his "Cashflow" board game could evolve into a blockchain-based platform where users simulate investments in real-world assets. Meanwhile, his seminars may incorporate virtual reality to provide immersive financial education. The bigger question, however, is whether his philosophy can remain relevant in an era where automation threatens traditional job structures. If anything, Ralph H. Kiyosaki’s legacy suggests that the conversation about money—and who controls it—will only grow more urgent.
Conclusion
Ralph H. Kiyosaki is a paradox: a self-made millionaire whose methods have made him millions more, yet whose career has been defined by as much controversy as acclaim. His ability to simplify financial complexity has made him a folk hero to some and a cautionary tale to others. What’s clear is that his impact extends beyond personal finance—he’s forced a reckoning with how society teaches (or fails to teach) money management. Whether his teachings are universally applicable or merely a reflection of his own experiences, they’ve undeniably reshaped the discourse around wealth. The Ralph H. Kiyosaki phenomenon also raises broader questions about the role of gurus in modern capitalism. In an age where financial literacy is often an afterthought, his work fills a void—but it also highlights the risks of uncritical consumption of financial advice. As the economy continues to evolve, Kiyosaki’s legacy may well be measured by how well his principles adapt to new challenges. One thing is certain: the debate over his methods will persist, ensuring that Ralph H. Kiyosaki remains a defining figure in the world of personal finance.Comprehensive FAQs
Q: Is Ralph H. Kiyosaki’s advice legally sound?
Kiyosaki’s methods—particularly his views on taxes and leverage—have faced legal scrutiny. While his core principles (like asset acquisition) are widely discussed in financial circles, his specific recommendations should be vetted by professionals. His past tax disputes (e.g., the 2010 IRS settlement) serve as a reminder that aggressive financial strategies carry risks.
Q: How did Ralph H. Kiyosaki make his first million?
Kiyosaki’s early wealth came from entrepreneurship, including selling Washington Post newspapers, founding a surfboard company, and later investing in real estate. His "Rich Dad" narrative, however, is more about philosophy than a step-by-step blueprint for wealth. His first major financial breakthrough came with the publication of Rich Dad Poor Dad in 1997.
Q: Are Ralph H. Kiyosaki’s books still relevant today?
Yes, but with caveats. While his core messages about assets and mindset remain relevant, some of his specific advice (e.g., on real estate markets or tax strategies) may need updating. His later works, like The Business of the 21st Century, reflect attempts to modernize his teachings for the digital age.
Q: What’s the biggest criticism of Ralph H. Kiyosaki’s teachings?
The most common critique is that his methods oversimplify complex financial concepts, potentially leading readers to take on excessive debt or make poor investment decisions. Critics also argue that his "Rich Dad" narrative ignores systemic barriers to wealth, such as racial or economic disparities.
Q: Does Ralph H. Kiyosaki endorse cryptocurrency?
Yes, Kiyosaki has publicly supported cryptocurrencies like Bitcoin, framing them as part of a broader shift toward digital assets. He argues that traditional currencies are losing value and that decentralized finance offers new opportunities for wealth-building.
Q: How does Ralph H. Kiyosaki’s approach differ from Warren Buffett’s?
Kiyosaki focuses on assets, leverage, and entrepreneurship, while Buffett emphasizes long-term value investing in stocks. Kiyosaki’s methods are more aggressive and hands-on, whereas Buffett’s strategy is passive and research-driven. Their philosophies reflect fundamentally different views on how wealth is created.
Q: Can you really get rich by following Ralph H. Kiyosaki’s advice?
There’s no guarantee, but many of his followers credit his teachings with improving their financial literacy and encouraging them to take action. Success depends on execution, market conditions, and individual circumstances. As Kiyosaki himself often says, "Education isn’t about learning facts—it’s about learning how to learn."
