Where It All Began
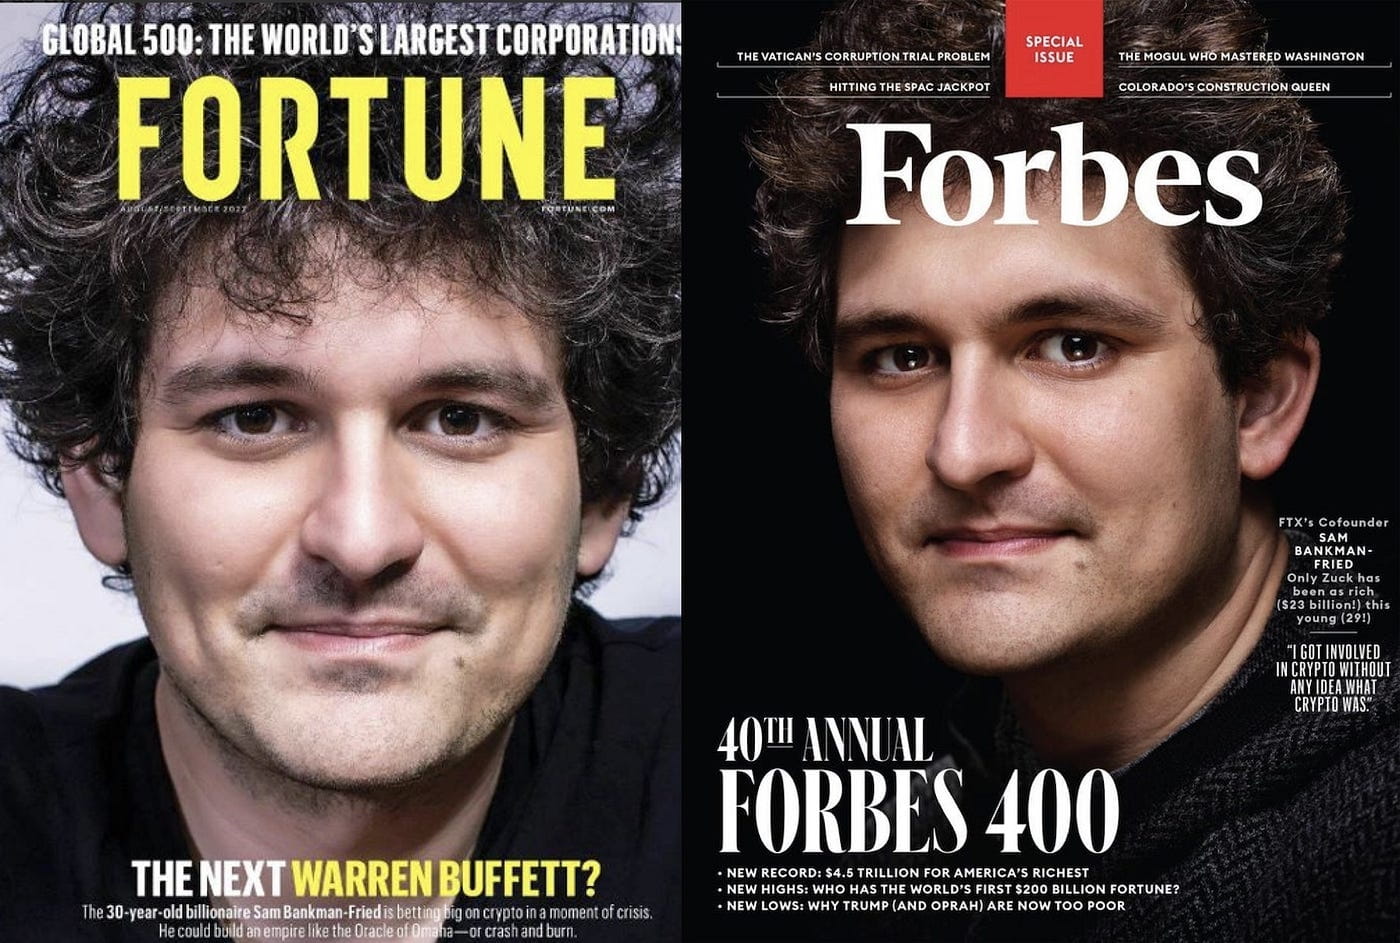
Sam Bankman-Fried’s origins read like a Silicon Valley origin myth, but with a twist: instead of coding in a garage, he was crunching numbers in a dorm room. Born in 1992 to two Stanford law professors, he was an early adopter of the quant mindset—obsessed with probability, utility theory, and the idea that markets could be gamed if you just applied enough logic. By his early 20s, he was trading futures at Jane Street Capital, where he developed a reputation for ruthless efficiency. Colleagues described him as a machine: calm under pressure, hyper-focused, and utterly devoid of ego. That detachment would later become both his superpower and his undoing. The shift to crypto came in 2017, when he spotted an opportunity in the unregulated chaos of digital assets. With a small team, he launched Alameda Research, a trading firm that would become the shadow bank of the crypto world. The strategy was simple: exploit inefficiencies across exchanges, borrow aggressively, and deploy capital with surgical precision. Early wins were staggering. By 2020, Alameda was reportedly managing billions, and Bankman-Fried was positioning himself as the industry’s moral compass—donating millions to effective altruism, lobbying for crypto-friendly regulation, and preaching the gospel of risk parity. The message was clear: sam bankman fried crypto wasn’t just another trader. He was the architect of a new financial paradigm.The Early Signs
Even at its height, Alameda’s model was a house of cards. The firm relied on leverage so extreme that a single bad trade could trigger a cascade. Insiders later revealed that Bankman-Fried’s risk management was less about hedging and more about praying to the god of volatility. Worse, the lines between Alameda and FTX—the exchange he founded in 2019—were nonexistent. FTX wasn’t just a customer; it was Alameda’s ATM. The exchange’s native token, FTT, was used as collateral for loans, creating a feedback loop where Alameda’s losses could be masked by FTX’s own reserves. By 2021, the cracks were showing. Competitors whispered about FTX’s shaky finances. Journalists dug into the lack of transparency around withdrawals. But Bankman-Fried dismissed concerns, confident that his brainpower would outmaneuver the market. The final irony? His downfall wasn’t a hack or a black swan event—it was a simple liquidity crunch, triggered when a rival hedge fund demanded its money back. What followed was a domino effect of revelations: missing funds, forged documents, and a balance sheet that was, in the words of one examiner, "a fiction."The Turning Point
The moment sam bankman fried crypto became a household name wasn’t his rise—it was his fall. On November 2, 2022, CoinDesk published a leaked balance sheet from Alameda Research. The numbers were catastrophic: liabilities dwarfed assets, and much of the firm’s "capital" was backed by FTT tokens—worthless unless FTX honored them. The crypto world froze. Within days, Binance CEO Changpeng Zhao announced he was liquidating his FTT holdings, triggering a bank run. FTX’s reserves evaporated overnight. The turning point wasn’t just financial—it was psychological. Bankman-Fried, who had spent years portraying himself as the rational savior of crypto, suddenly looked like a man who had bet everything on a house of mirrors. His public statements grew increasingly frantic, then defensive, then bizarre. In a now-infamous tweet, he compared the situation to a "confidence game" where everyone was bluffing. The truth was simpler: sam bankman fried crypto had built a pyramid scheme, and the music had stopped."I fucked up. I take full responsibility. I was wrong about a lot of stuff." — Sam Bankman-Fried, December 12, 2022 (first public apology)
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2017–2018 | Bankman-Fried leaves Jane Street to launch Alameda Research, focusing on arbitrage across crypto exchanges. Early profits fund FTX’s founding in 2019, positioned as a "customer-first" platform. Regulators take little notice. |
| 2019–2020 | FTX grows rapidly, offering leveraged trading and derivatives. Alameda’s losses are masked by FTX loans backed by FTT tokens. Bankman-Fried becomes a crypto celebrity, donating millions to political campaigns and effective altruism causes. |
| 2021 | FTX’s valuation hits $32 billion. Alameda’s leverage reaches unsustainable levels. Internal audits allegedly raise concerns, but Bankman-Fried dismisses them. Competitors like Binance begin questioning FTX’s solvency. |
| November 2022 | CoinDesk publishes Alameda’s balance sheet, exposing a $6 billion shortfall. Binance’s CZ sells FTT holdings, sparking a withdrawal frenzy. FTX files for bankruptcy. |
| December 2022–Present | Bankman-Fried is arrested in the Bahamas, extradited to the U.S., and charged with fraud. FTX’s assets are liquidated; customers recover pennies on the dollar. The industry grapples with the aftermath. |
Lessons From the Journey
- Transparency isn’t optional—it’s the foundation of trust. FTX’s collapse proved that even the most sophisticated traders can’t outrun a lack of accountability.
- Leverage is a double-edged sword. Alameda’s model assumed markets would always favor the bold; reality showed that hubris has no hedge.
- The cult of the "genius" is dangerous. Bankman-Fried’s reputation as an infallible quant blinded him—and others—to basic controls.
- Regulation isn’t the enemy—it’s the safety net. The absence of oversight in crypto didn’t just fail FTX; it failed thousands of investors who trusted the system.
Where Things Stand Today
As of 2024, sam bankman fried crypto is a defendant in one of the most high-profile financial fraud cases in decades. His trial in New York has exposed a web of deceit: misappropriated funds, forged documents, and a culture of fear at FTX where whistleblowers were ignored. The legal team’s strategy—painting him as a well-meaning but flawed idealist—has done little to soften the charges. Prosecutors argue that his actions were deliberate, not just reckless. The crypto industry, meanwhile, is in damage control mode. Exchanges that once emulated FTX’s aggressive growth models are now scrambling to prove their solvency. Regulators, from the SEC to global financial watchdogs, are tightening grip. And Bankman-Fried? He’s become a cautionary figure, his name synonymous with the risks of unchecked ambition. Whether he serves as a warning or a footnote remains to be seen—but one thing is clear: sam bankman fried crypto’s legacy isn’t just about the money. It’s about the trust that money represents.
Conclusion
The story of sam bankman fried crypto is a microcosm of the crypto era itself: a time of boundless promise and reckless experimentation. Bankman-Fried wasn’t a villain in the traditional sense—he was a product of an industry that rewarded speed over substance, and ideology over prudence. His downfall wasn’t a fluke; it was the inevitable consequence of treating finance like a game where the rules could be bent, ignored, or rewritten on a whim. Yet for all the lessons, the cycle may repeat. New exchanges rise, new traders emerge, and the allure of outsized returns remains. The difference now? The scars of FTX’s collapse are still fresh, and the industry—however reluctantly—is learning that sam bankman fried crypto’s greatest sin wasn’t fraud. It was the belief that genius alone could replace governance.Comprehensive FAQs
Q: How much money did FTX lose before collapsing?
Exact figures are still under legal scrutiny, but industry estimates suggest FTX’s liabilities exceeded assets by roughly $8 billion at the time of collapse. The bankruptcy proceedings revealed that customer funds were used to prop up Alameda Research, with no clear audit trail.
Q: Is Sam Bankman-Fried still involved in crypto?
No. Since his arrest, Bankman-Fried has distanced himself from the industry, focusing on his legal defense. He has expressed interest in returning to trading but faces significant barriers, including travel restrictions and the stigma of his past actions.
Q: What charges is he facing?
Bankman-Fried is accused of securities fraud, wire fraud, and money laundering under U.S. law. The indictment alleges he misled investors, used FTX customer funds for personal use (including political donations and real estate), and engaged in a Ponzi-like scheme to sustain Alameda’s losses.
Q: How are FTX customers being compensated?
Recovery efforts are ongoing, but most customers have received only a fraction of their lost funds. The FTX bankruptcy trustee has prioritized secured creditors, leaving retail investors at the back of the line. Some estimates suggest recovery rates could be as low as 5–10%.
Q: Did Bankman-Fried’s political donations influence regulation?
There’s no direct evidence that his donations—totaling millions to both Democrats and Republicans—altered policy, but they did embed him in Washington’s crypto debate. Critics argue his lobbying efforts created a perception of influence, which may have delayed scrutiny of FTX’s operations.
Q: What’s the biggest lesson for crypto investors?
The FTX collapse underscored three critical risks: lack of transparency, over-reliance on leverage, and the dangers of centralized control. Investors are now advised to diversify across exchanges, demand proof of reserves, and treat high-risk assets with the same caution as traditional markets.
Q: Could this happen again?
Absolutely. While regulators are tightening oversight, the crypto industry’s decentralized nature means new risks emerge constantly. The key difference now is awareness—though history shows that even awareness isn’t always enough to prevent greed from taking over.
