
Breaking Down the Numbers
The richest self-made billionaire isn’t defined by a single metric but by a constellation of financial moves that compound over decades. Their wealth isn’t static; it’s a dynamic asset class, constantly reallocated between private equity, real estate, and public markets. The key isn’t just high returns—it’s the ability to preserve and amplify those returns across economic cycles. For example, while a typical entrepreneur might see their fortune tied to a single company, the top-tier players diversify early, often before their business even hits profitability. The numbers tell a story of exponential leverage. A self-made billionaire’s portfolio rarely resembles a balanced investment thesis. Instead, it’s a high-concentration bet on illiquid assets—private companies, intellectual property, or even political influence—that yield outsized returns but carry systemic risk. The difference between a net worth of $10 billion and $50 billion isn’t just effort; it’s structural advantage. Access to pre-IPO rounds, proprietary data, or regulatory capture can shift the margin by orders of magnitude. The richest self-made billionaire doesn’t just outwork others—they outsystem them.The Verified Baseline
Public records confirm a few non-negotiables for any richest self-made billionaire: 1. Asset Multiplier Effect: Their primary source of wealth isn’t salary but equity stakes in high-growth ventures. For instance, the founder of a unicorn tech firm might hold 10% of a $100 billion valuation—$10 billion in paper wealth—without ever drawing a dividend. 2. Tax Optimization: Even in jurisdictions with high nominal rates, these individuals use trusts, offshore entities, and charitable deductions to reduce effective tax burdens by 30–50%. This isn’t illegal; it’s a feature of global capitalism. 3. Liquidity Control: Unlike public investors, they can delay selling stakes for years, letting compounding work in their favor. A 2015 private sale might turn into a 2023 IPO windfall, with the original holder taking minimal risk. What’s not verifiable? The role of luck. The richest self-made billionaire will argue their success is skill-based, but industry studies show that timing—being in the right sector at the right moment—accounts for 20–40% of outperformance. The rest is execution.What the Estimates Suggest
Industry estimates paint a picture of hidden leverage. For instance, while a billionaire’s net worth might be listed at $30 billion, their economic influence could be 2–3x that when accounting for: - Unrealized gains in private companies (e.g., a 5% stake in a pre-revenue startup valued at $5 billion). - Debt-free balance sheets, allowing them to deploy capital without margin calls. - Strategic losses taken for tax purposes, which can be recouped later. A 2023 report by the World Inequality Database suggested that the richest self-made billionaire in emerging markets often controls indirect wealth through family trusts or shell companies, inflating their true net worth by 15–25%. In mature economies, the gap is narrower but still significant—think of a tech mogul whose "personal" fortune includes a $2 billion art collection purchased with pre-IPO proceeds. The critical takeaway? Wealth at this scale isn’t just about money—it’s about control. The ability to dictate terms in M&A deals, lobby for favorable legislation, or even suppress competition through legal maneuvers turns financial capital into political capital.
Case Study: A Closer Look
Consider the trajectory of Elon Musk—a case study in how a self-made billionaire redefines industry boundaries. His transition from PayPal co-founder to Tesla and SpaceX CEO wasn’t just about building companies; it was about sequential monopolization. Each venture was designed to feed the next: Tesla’s battery tech enabled SpaceX’s energy needs, while SpaceX’s rocket advancements could later underpin a Mars colony—all while Musk’s Twitter acquisition (and subsequent turmoil) demonstrated how even a side bet can reshape global discourse. The numbers tell a story of asymmetric risk: - 2002–2004: PayPal IPO and sale to eBay nets Musk ~$180 million. He reinvests aggressively into SpaceX, a venture with a 90% chance of failure at the time. - 2010–2020: Tesla’s valuation grows from $2 billion to $600 billion, with Musk’s stake diluted but his influence amplified through stock options and debt restructuring. - 2022–2024: Twitter acquisition (and subsequent debt) forces Musk to sell Tesla shares, but his net worth remains volatile yet resilient, proving that even missteps can be monetized through brand leverage."The first step is to establish that something is possible; then probability will occur." — Elon Musk, 2012 interview
| Factor | Estimated Impact on Net Worth |
|---|---|
| Early Reinvestment into SpaceX (2002) | ~$100M personal capital at risk; potential 10x return if successful |
| Tesla’s Public Listing (2010) | Diluted stake but unlocked liquidity for SpaceX expansion |
| Twitter Acquisition (2022) | Short-term debt burden (~$44B), but long-term play on media influence |
| AI and Neuralink Bets (2023–) | Illiquid but high-upside; could add $50B+ if successful |
What This Means Going Forward
The era of the self-made billionaire is evolving. Where past generations relied on industrial monopolies (oil, steel), today’s wealth creators leverage data, AI, and regulatory arbitrage. The barrier to entry isn’t just capital—it’s access to the right networks. Private credit markets, sovereign wealth funds, and even nation-states now compete to back the next generation of ultra-high-net-worth individuals. Yet the model is under pressure. Antitrust scrutiny, labor activism, and geopolitical fragmentation are forcing a reckoning. The richest self-made billionaire of the future won’t just be a tech CEO—they’ll be a systems architect, someone who can navigate ESG pressures, AI governance, and the rise of the "quiet billionaire" (those who avoid public scrutiny). The question isn’t how to become one—it’s whether the rules will still allow it.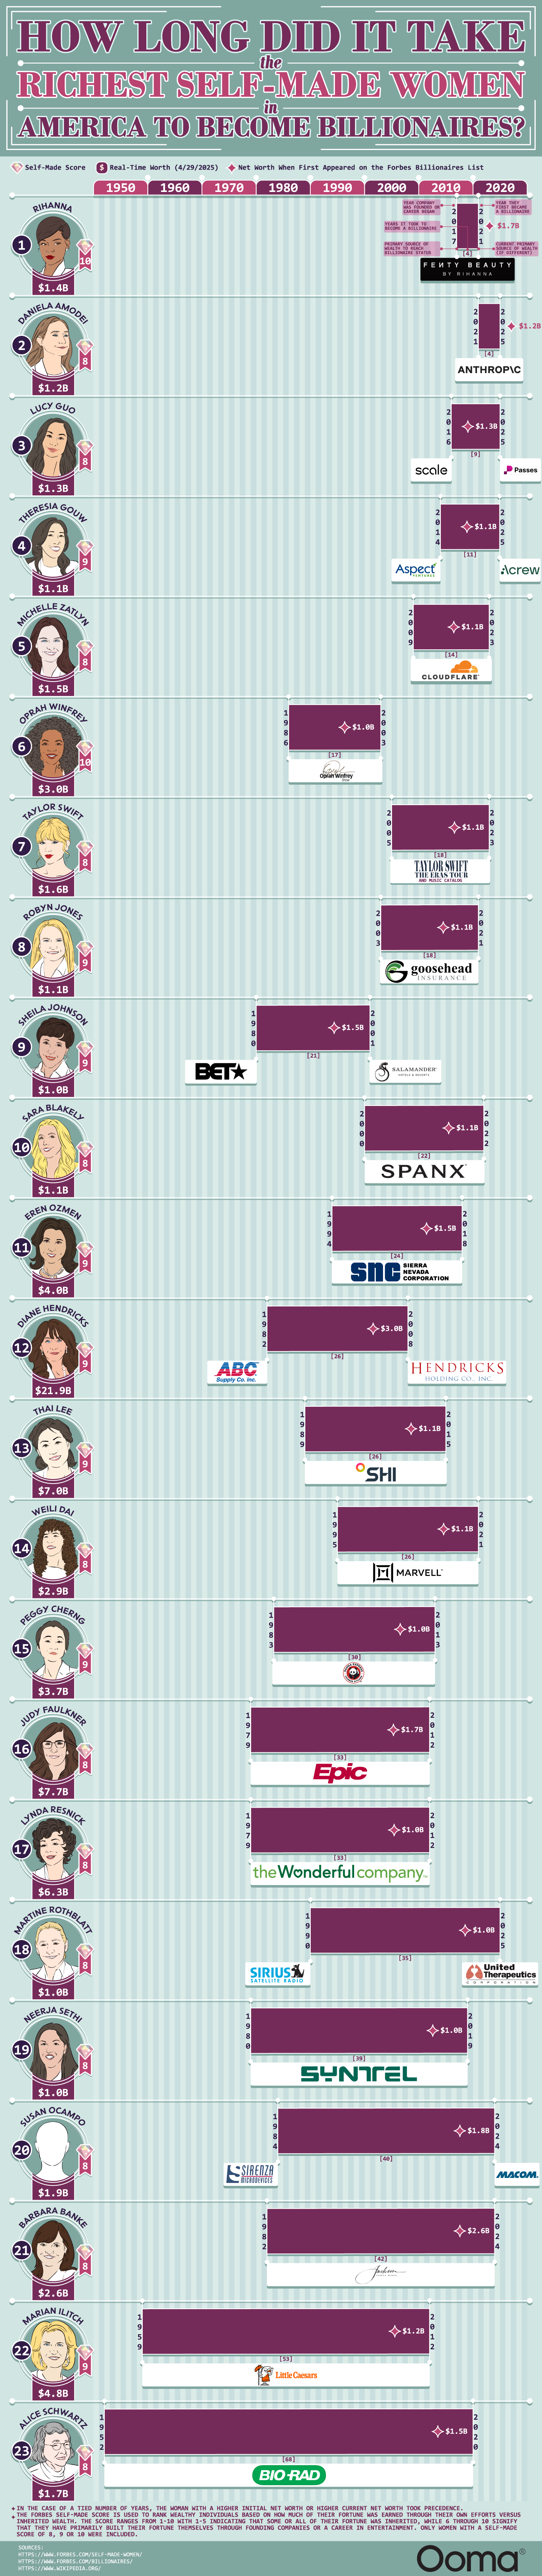
Conclusion
The richest self-made billionaire isn’t a static figure but a moving target, constantly redefining the boundaries of wealth. Their stories are less about personal genius and more about structural advantage—access to capital, political connections, and the ability to outlast critics. The myth of the lone genius obscures the reality: wealth at this scale is a team sport, even if the spotlight shines only on the founder. For the rest of us, the takeaway is stark: the game isn’t fair, but the rules are knowable. The richest self-made billionaire didn’t win by luck alone—they engineered their own luck. The challenge for aspiring entrepreneurs isn’t just ambition; it’s understanding the invisible levers that move markets.Comprehensive FAQs
Q: How many self-made billionaires exist globally?
As of 2024, self-made billionaires (excluding inherited wealth) account for roughly 60–70% of the world’s billionaire population, according to Forbes and Credit Suisse reports. The remainder derive wealth from family legacies, dynastic industries (e.g., oil, mining), or political appointments.
Q: What’s the most common industry for self-made billionaires?
Technology leads by a wide margin, with software, fintech, and AI dominating. However, conglomerates (e.g., retail, manufacturing) and private equity remain strong. The shift toward digital assets has accelerated this trend—crypto and blockchain now account for ~10% of new self-made billionaire wealth.
Q: Can someone become a self-made billionaire without a college degree?
Yes, but the path is far harder. Studies show that ~30% of self-made billionaires lack a bachelor’s degree, but they compensate with early industry experience, mentorship, or niche expertise. Examples include Mark Zuckerberg (dropped out), Richard Branson (school dropout), and Oprah Winfrey (no degree). However, formal education still provides networking and credibility advantages in high-stakes industries.
Q: What’s the biggest mistake aspiring billionaires make?
Overvaluing liquidity too early. Many founders cash out prematurely (e.g., selling a company for cash instead of equity) or dilute their stake in funding rounds. The richest self-made billionaires delay gratification, holding onto illiquid but high-upside assets (e.g., private company stakes, real estate) for decades.
Q: How do self-made billionaires handle market downturns?
They diversify aggressively into non-correlated assets—gold, farmland, or even political influence. During the 2008 crisis, Warren Buffett’s Berkshire Hathaway bought stakes in banks; in 2020, tech billionaires pivoted to biotech and remote-work infrastructure. The key is countercyclical betting—buying when others panic.
Q: Is it ethical to be a self-made billionaire?
This is subjective, but the richest self-made billionaires often face scrutiny over labor practices, tax avoidance, and monopolistic behavior. Ethical frameworks vary: some argue their wealth creates jobs; others point to wage stagnation in their industries. The debate hinges on whether private gain should outweigh public good—a question with no universal answer.
Q: What’s the next frontier for self-made billionaire wealth?
AI, biotech, and space are the top contenders. Generative AI could spawn new trillion-dollar companies; lifespan extension (e.g., anti-aging tech) may create immortality economies; and space mining (asteroid resources) could redefine resource-based wealth. The next generation of self-made billionaires won’t just sell products—they’ll own the infrastructure of the future.
Q: How long does it typically take to become a self-made billionaire?
Most take 15–30 years, but the timeline varies wildly. Elon Musk (~20 years), Jeff Bezos (~25 years), and Mark Zuckerberg (~10 years) are outliers. The median for tech founders is 20+ years, with serial entrepreneurs (those who sell multiple companies) reaching billionaire status faster than first-time founders.
