7 Things Worth Knowing About the Richest Investment Banker
The richest investment banker thrives in a paradox: their wealth is invisible until it’s not. Their power lies in the ability to make markets move without ever being the center of attention. What follows are the seven pillars that sustain their dominance—each a testament to how capitalism’s elite operate at a level most never see.1. Their Wealth Is Often Hidden in Plain Sight
The richest investment banker rarely tops Forbes’ billionaire lists, yet their personal fortunes dwarf those of traditional tycoons. The reason? Compensation structures that reward performance in ways that avoid scrutiny. Bonuses, carried interest from private equity, and deferred earnings can stretch over decades, creating wealth that’s only partially visible in annual reports. Take the case of a top Goldman Sachs partner whose total compensation—including carried interest from the firm’s investment arms—has been estimated to exceed $1 billion over a career, yet their public net worth might appear modest by comparison. The discrepancy lies in how these earnings are structured: deferred, in trusts, or through complex holding companies that obscure direct ownership. What’s more, the richest investment banker often reinvests rather than flaunts. A $500 million bonus isn’t spent on yachts or private islands—it’s deployed into real estate, art, or other illiquid assets that don’t trigger taxable events. The result? A fortune that grows quietly, shielded from the volatility of public markets. This is the art of financial stealth: building wealth in ways that evade both regulators and the public eye.2. Their Networks Are More Valuable Than Their Trades
In investment banking, relationships are the ultimate currency. The richest investment banker doesn’t just have clients—they have gatekeepers. A single call to a central bank governor, a sovereign wealth fund CEO, or a tech mogul can unlock deals worth billions. These networks aren’t built overnight; they’re cultivated over decades, often through elite education (Harvard, Oxford, or Wharton), shared membership in exclusive clubs (the Links, the Explorers Club), and a rotating door of power brokers who move between finance, politics, and industry. Consider the case of a former JPMorgan Chase banker who leveraged connections forged during his time at the Treasury Department to secure a $10 billion financing deal for a Middle Eastern sovereign client. The bank’s profit? A fraction of that. His personal influence? Priceless. The richest investment banker understands that access to capital is secondary to access to decision-makers. This is why firms like Goldman Sachs spend fortunes on maintaining relationships with world leaders—not just for business, but as a strategic reserve for when markets turn.3. They Dominate Through Proprietary Advantage
The richest investment banker doesn’t just execute trades; they create the markets that make those trades possible. Take the example of Citadel Securities, the market-making arm of Ken Griffin’s hedge fund empire. By providing liquidity in ways that traditional banks can’t, Citadel has become indispensable to hedge funds and asset managers worldwide. Its revenue model—earning spreads on trades—isn’t just profitable; it’s systemic. When markets stress, Citadel’s ability to absorb volatility without failing becomes a public good, reinforcing its dominance. Similarly, private equity firms like Blackstone and KKR don’t just invest—they reshape industries. By acquiring distressed assets during crises, they become the de facto owners of entire sectors, from real estate to infrastructure. The richest investment banker in this ecosystem isn’t just a financier; they’re an industrialist, using capital to control supply chains, labor markets, and even regulatory outcomes. This is the next frontier of banking: not just moving money, but owning the infrastructure that moves it.4. Their Risks Are Systemic, Not Personal
The richest investment banker operates under a unique immunity. When a bank like Lehman Brothers collapses, it’s the shareholders who bear the cost—not the executives who bet the firm. When a hedge fund like Long-Term Capital Management (LTCM) nearly brings down global markets, the Federal Reserve steps in to bail it out, with the implicit understanding that too big to fail applies to individuals as much as institutions. This isn’t just luck; it’s the result of structural protections. Carried interest rules, regulatory arbitrage, and the sheer scale of their operations mean that personal liability is a myth. Even when mistakes happen—like the 2012 "London Whale" trade that cost JPMorgan $6 billion—the fallout rarely extends to the architects. The richest investment banker knows that in finance, failure is an option, as long as the system absorbs the cost. This creates a perverse incentive: take bigger risks, because the downside is always socialized. The result? A culture where recklessness is rewarded, and caution is punished.5. They’re Judged by What They Don’t Do
The richest investment banker’s greatest skill isn’t making money—it’s avoiding losses. In a world where a single misjudged trade can erase years of profit, the ability to walk away from bad bets is more valuable than any coup. This is why the most successful operators in the field are often the least visible: they don’t chase the next big IPO or the hottest tech sector. Instead, they allocate capital with surgical precision, knowing when to deploy and when to retreat. Consider the case of a top Blackstone partner who, during the 2008 financial crisis, avoided the real estate bubble that crushed competitors. While others were betting big on distressed assets, he focused on liquid alternatives—private credit, infrastructure, and cash-rich sectors that weathered the storm. His firm’s returns during the downturn were among the highest in the industry, not because he took more risk, but because he took less. The richest investment banker understands that in finance, preservation is the ultimate profit.6. Their Legacy Is Measured in Influence, Not Just Money
"The best bankers don’t just make deals—they make history. And history is written by those who control the narrative, not those who execute it." — Former Goldman Sachs partner, speaking off-record to a private equity forumThe richest investment banker doesn’t just accumulate wealth; they shape the future. Through think tanks like the Council on Foreign Relations, lobbying efforts, or even philanthropy, they ensure that the rules of the game favor their playbook. A single donation to a university’s finance department can produce the next generation of bankers who think like them. A quiet conversation with a regulator can alter policy in ways that benefit their firms for decades. Take the example of a former Treasury official turned private equity titan who now advises central banks on monetary policy. His ability to influence interest rates—even indirectly—affects the valuation of trillions in assets under management. The richest investment banker doesn’t just win deals; they redraw the boundaries of what’s possible. This is why their influence extends far beyond Wall Street: they are the architects of the financial order itself.
7. They’re Always One Step Away from the Next Crisis
The richest investment banker operates in a state of perpetual vigilance. While the public focuses on quarterly earnings, they’re scanning for the next inflection point—the regulatory shift, the geopolitical flashpoint, or the technological disruption that will reshape their world. This is why the most successful among them are antifragile: they don’t just survive crises; they thrive in chaos. During the 2020 COVID-19 market crash, while retail investors panicked, hedge funds like Citadel and Point72 made billions by shorting volatility and deploying capital into distressed assets. The richest investment banker didn’t just profit from the crisis—they engineered the conditions for their gains. This is the dark side of their power: their ability to exploit systemic shocks while the rest of the world suffers. The line between opportunity and exploitation is thin, and they know how to blur it.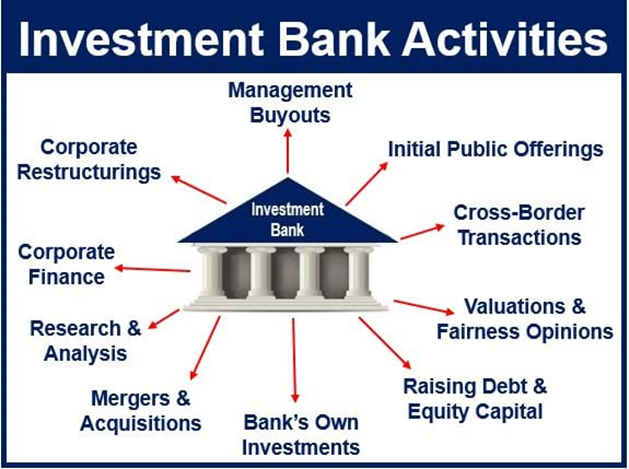
How These Facts Connect
The richest investment banker doesn’t exist in a vacuum. Their power is the sum of structural advantages—access, scale, and the ability to externalize risk—that create an almost impenetrable moat. Their wealth isn’t just personal; it’s systemic, embedded in the financial architecture that governs global capital flows. What connects these seven truths is the realization that their dominance isn’t accidental. It’s the result of a feedback loop: the more money they make, the more influence they wield; the more influence they wield, the more money they can make. This isn’t capitalism as most people experience it—where hard work and innovation determine success. For the richest investment banker, access and timing are the real drivers. They don’t compete on merit; they control the playing field. The table below contrasts the visible and invisible forces that sustain their position:| Visible Power | Invisible Power |
|---|---|
| Billion-dollar bonuses, luxury assets, public recognition | Regulatory capture, deferred compensation, proprietary networks |
| High-profile M&A deals, IPOs, and market-making | Control over liquidity, access to central bankers, influence on policy |
| Public perception of "winning" | Ability to socialize losses while privatizing gains |

Conclusion
The richest investment banker is a study in asymmetry. They operate under rules that don’t apply to anyone else, wielding capital as a weapon while insulating themselves from its risks. Their world is one of calculated opacity, where transparency is a liability and influence is the ultimate currency. Yet for all their power, they remain vulnerable—not to markets, but to the systems they’ve built. A single misstep in regulation, a shift in global sentiment, or a technological disruption could unravel decades of advantage. What’s clear is that their dominance isn’t going anywhere. If anything, the concentration of wealth and power in finance is accelerating, with the richest investment banker at the center of it all. The question isn’t whether they’ll remain untouchable—it’s what happens when the rest of society finally demands a seat at the table. Until then, their world will continue to operate by its own rules, where the only constant is change—and the only certainty is that someone, somewhere, is always one step ahead.Comprehensive FAQs
Q: Who is currently considered the richest investment banker?
A: As of recent estimates, figures like Ken Griffin (Citadel) and Stephen Schwarzman (Blackstone) frequently appear at the top of wealth rankings tied to investment banking. However, precise rankings fluctuate due to deferred compensation, carried interest, and private holdings. Griffin’s net worth is often cited in the $40 billion range, though exact figures are speculative given his diverse asset base. Schwarzman’s fortune, tied to Blackstone’s performance fees, has been estimated around $30 billion at its peak. The title is fluid—what matters more than individual names is the structural dominance of their firms in capital allocation.
Q: How do the richest investment bankers avoid taxes?
A: Tax avoidance for the richest investment banker is a multi-layered strategy. Carried interest—where profits from private equity are taxed at lower capital gains rates—is a primary tool. Offshore entities, trusts, and illiquid asset holdings (real estate, art, private equity stakes) further obscure taxable income. Additionally, earnings deferral means bonuses are paid over years, spreading tax liability. While legal, these structures exploit loopholes that Congress has repeatedly failed to close. The result? Effective tax rates that can be half or less of what middle-class earners pay.
Q: Can someone outside Wall Street become the richest investment banker?
A: Theoretically, yes—but the barriers are nearly insurmountable. The path requires decades of insider access, elite education, and a willingness to operate in the gray areas of finance. Most who try either burn out, get excluded by the old boys’ network, or lack the proprietary information that fuels the richest investment banker’s edge. Even then, success depends on timing—being in the right place when a crisis or opportunity arises. The system is designed to reward insiders and punish outsiders, making organic entry nearly impossible without pre-existing connections.
Q: What’s the biggest risk to their wealth?
A: The richest investment banker’s greatest vulnerability isn’t market downturns—it’s regulatory overreach. A single law changing carried interest rules, breaking up "too big to fail" institutions, or imposing wealth taxes could erode their fortunes overnight. Geopolitical shocks—like a U.S.-China decoupling or a European financial crisis—also pose existential threats to their global networks. Unlike traditional CEOs, their wealth is systemically tied to capital flows, meaning any disruption to the financial plumbing they control could unravel their empires faster than they can reinvest.
Q: How do they maintain their networks over decades?
A: Network maintenance is a relentless, institutionalized process. The richest investment banker leverages alumni networks (Harvard Business School, Goldman’s "Marquee" program), rotating doors between finance and government, and exclusive clubs (the Links, the Explorers Club) to keep relationships warm. They also deploy strategic philanthropy—donating to universities, think tanks, and cultural institutions to ensure future generations of elites are indebted to them. The key? Reciprocity. A favor given today is a favor called in tomorrow, often with compounding interest.
Q: Is there a dark side to their influence?
A: Absolutely. The richest investment banker’s power comes with systemic costs. Their ability to exploit information asymmetry has led to scandals like the 2008 financial crisis, where reckless bets were socialized while profits were privatized. Their control over liquidity can amplify market bubbles, as seen in the 2021 meme-stock frenzy, where hedge funds like Citadel made billions while retail investors lost. Additionally, their lobbying efforts often delay or weaken regulations that could protect the public—like the Dodd-Frank rollbacks that increased systemic risk. The dark side isn’t just moral; it’s structural.
Q: How do they handle failure?
A: Failure for the richest investment banker is never personal. When a trade goes wrong, the firm absorbs the loss, and the architect moves on to the next opportunity. The culture of no blame in elite finance means even catastrophic mistakes (like the London Whale trade) rarely result in career-ending consequences. Instead, they’re treated as learning experiences—and the banker in question is often promoted for their risk-taking. The real failure isn’t losing money; it’s not learning how to lose bigger next time.
Q: What’s the future of their dominance?
A: The richest investment banker’s future hinges on three wildcards: technology, regulation, and public backlash. AI and algorithmic trading could either democratize finance (reducing their edge) or concentrate power further (if only a few firms control the best models). Regulation remains the biggest threat—if governments act decisively, they could break up the "too big to fail" complex. Public sentiment is also shifting, with movements like Occupy Wall Street and Bernie Sanders’ wealth taxes signaling growing resistance. The question isn’t whether their dominance will end—it’s how. The richest investment banker has always thrived in chaos; the challenge is whether society will let them.
