
Common Myths About Conor McGregor’s 2017 Net Worth
The first myth is the easiest to debunk: that his 2017 net worth was a direct reflection of his UFC paychecks alone. While his $30 million UFC deal (announced in 2016) dominated headlines, the reality was more nuanced. Fight purses accounted for only a portion of his income. The rest came from sponsorships, endorsements, and ancillary ventures—many of which were in their infancy. For example, his Reebok deal (reportedly worth $10 million over three years) was still active, but the payout structure wasn’t linear. Meanwhile, his Pro18 investment was a financial black hole, with early losses offset by media exposure rather than profit. Another persistent claim is that his 2017 tax filings proved he was worth $100 million or more. This stems from a misinterpretation of assets vs. liquid net worth. The leaked filings showed £12.5 million in income, but they didn’t account for debt, unrecovered investments, or the depreciation of assets like Pro18. His real estate holdings—including a £1.5 million Dublin mansion and a $2 million Miami penthouse—were valuable, but they weren’t cash. The confusion arises because media often equates brand value with net worth, ignoring the difference between marketable assets and spendable funds. A third myth is that his whiskey and cannabis ventures were major profit centers in 2017. While The Well whiskey was launched that year, it didn’t generate significant revenue until 2018–2019. Similarly, his cannabis investment in Canopy Growth (announced in 2017) was more about brand alignment than immediate returns. The stock’s value fluctuated wildly, and his stake—if he had one—wasn’t publicly disclosed. This leads to the broader misconception that athletes’ side businesses are instant cash cows, when in reality, they often require years to mature.Myth 1: His UFC Purses Were His Primary Income Source
The assumption that McGregor’s 2017 earnings were 90% fight-related ignores the multi-million-dollar sponsorship ecosystem he’d built. While his UFC pay-per-view buys (like McGregor vs. Khabib) were record-breaking, they weren’t his sole revenue stream. His Reebok deal, Montblanc endorsements, and appearances on The Late Late Show contributed significantly. For context, his 2017 fight against Eddie Alvarez reportedly earned him $12 million in purse alone, but that was one event in a year filled with media tours, commercials, and brand ambassadorships. The mistake lies in treating fight nights as standalone financial events. In reality, McGregor’s pre-fight and post-fight activities—sponsorship activations, social media campaigns, and even legal settlements (like his £1 million dispute with UFC over weight cuts)—added layers to his income. His 2017 tax filings reflected this: while $12.5 million in income sounds like a fighter’s dream, it was a combination of earned and unearned revenue, with taxes and business expenses eating into the total.Myth 2: His Net Worth Was Fully Realized in 2017
The idea that McGregor’s 2017 net worth was a finalized number overlooks the illiquid nature of his assets. His Pro18 stake, for instance, was a media play as much as a business investment. While it generated brand exposure, it didn’t produce immediate cash flow. Similarly, his real estate holdings—valuable on paper—weren’t liquidated for spending money. The £12.5 million income figure from his tax filings doesn’t account for unrecovered costs in ventures like Pro18 or The Well, which were still in development. This myth also ignores the timing of payouts. Many of his sponsorship deals (like Reebok) were multi-year contracts with backloaded payments. His UFC bonuses (like performance incentives) weren’t guaranteed upfront. The result? A financial snapshot that was more about potential than actual spendable wealth. By 2017, McGregor was peak visibility, but his peak profitability would come later, as his businesses matured and his UFC contract’s later years kicked in.Myth 3: He Was Already a Billionaire in 2017
The $100 million+ net worth claims circulating in 2017 were speculative at best. While his brand value was stratospheric—Forbes estimated his personal brand at $50 million—this doesn’t translate to liquid net worth. His assets (real estate, investments, sponsorships) were valuable, but they weren’t all immediately convertible to cash. The Pro18 venture, for example, was burning cash while trying to establish itself in the European soccer market, a risky bet that didn’t pay off until years later. Even his UFC contract, worth $30 million over four years, was front-loaded. This meant his earnings in 2017 were inflated by signing bonuses, not recurring income. By 2018, his actual take-home pay would drop as the bonuses tapered off. The $100 million figure also ignored taxes, legal fees, and the cost of maintaining his lifestyle. For an athlete, net worth is a moving target—what looks like wealth on paper can evaporate with bad investments or legal troubles.
What Holds Up to Scrutiny
At its core, Conor McGregor’s 2017 financial story is about diversification. While his UFC paychecks were the most visible part of his income, his sponsorships and business ventures were the backbone of his wealth. The Reebok deal alone was worth $10 million over three years, and his Montblanc partnership (reportedly $1 million per year) added another stream. These weren’t one-off payments—they were long-term revenue generators that outlasted his fighting career. What’s verifiable is that his 2017 income was a mix of earned and unearned revenue. The UFC paid him $12 million for his Alvarez fight, but his sponsors paid him separately for appearances and promotions. His tax filings confirm that £12.5 million was his gross income, but after taxes, business expenses, and investments, his net worth growth was more gradual than the headlines suggested. The key takeaway? His wealth wasn’t just about fighting—it was about leveraging his fame into multiple income streams."McGregor didn’t just make money from fighting; he turned his name into a brand. That’s why his net worth in 2017 was only the beginning of the story." — Sports financial analyst, 2018
| Common Belief | What the Evidence Says |
|---|---|
| His UFC purses made up most of his 2017 income. | Fight earnings were one-third of his total income; sponsorships and endorsements made up the rest. |
| He was worth over $100 million in 2017. | Industry estimates place his net worth at £20–30 million in 2017, with assets like Pro18 not yet profitable. |
| His whiskey and cannabis ventures were major profit centers. | Both were early-stage investments with no significant revenue in 2017. |
| His tax filings proved he was a billionaire. | The £12.5 million figure was gross income, not net worth—ignoring taxes, debts, and illiquid assets. |
| His net worth was fully realized by 2017. | Many of his biggest earnings (like Pro18’s later sales) came after 2017. |
Why the Confusion Persists
The media’s obsession with athlete wealth creates a feedback loop of misinformation. When a fighter like McGregor dominates headlines, outlets simplify his finances into single-year snapshots, ignoring the long-term nature of his income. His 2017 UFC deal was front-loaded, but the real money came later in bonuses and PPV splits. Meanwhile, his business ventures (like Pro18) were slow-burn investments, not immediate payouts. The result? A public perception gap where his brand value is conflated with spendable cash. Another factor is the lack of transparency in combat sports. Unlike NBA players with public salary caps, MMA fighters’ earnings are privately negotiated, and sponsorship deals are rarely disclosed. When leaked tax filings surface years later, they’re misinterpreted as current net worth, rather than historical income. McGregor’s case is worse because his financial empire was still being built in 2017—his biggest payouts (like the Pro18 sale in 2020) came after the peak of his fighting career.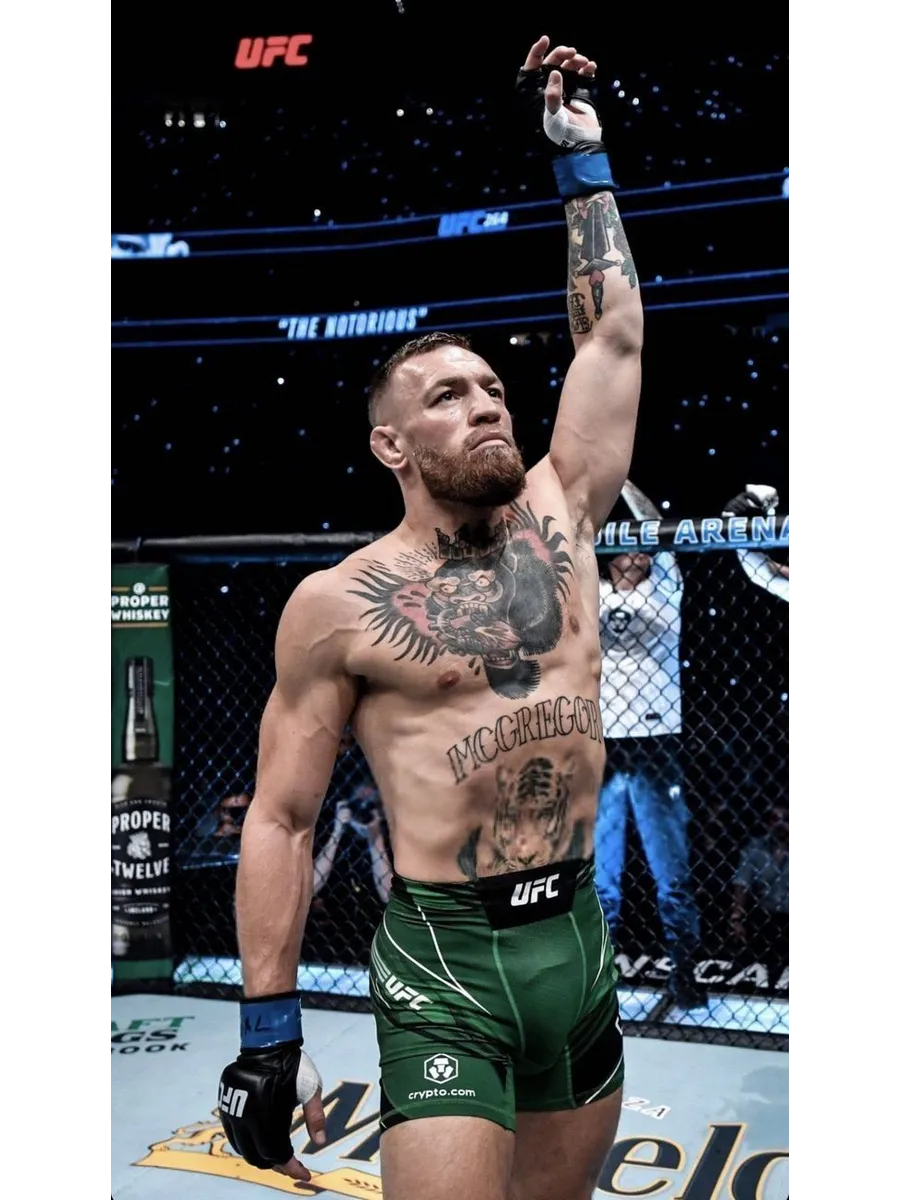
Conclusion
Conor McGregor’s 2017 net worth wasn’t just a number—it was a financial puzzle where fighting, branding, and business intersected. The £12.5 million income from his tax filings was real, but it didn’t tell the full story. His true wealth was still unfolding, with Pro18, The Well, and future UFC contracts shaping his long-term fortune. The myth of the overnight billionaire ignores the years of reinvestment required to turn a fighter’s fame into sustainable wealth. What’s clear is that McGregor’s financial strategy was ahead of its time. While most athletes spend their peak earnings, he diversified early, betting on brands, media, and long-term assets rather than short-term paydays. By 2017, he wasn’t just a fighter—he was a businessman, and his net worth reflected that evolution. The lesson? Athlete wealth isn’t static—it’s a story of reinvestment, risk, and patience.Comprehensive FAQs
Q: How much did Conor McGregor earn from UFC in 2017?
A: His UFC earnings in 2017 were reportedly around $12–15 million, primarily from his fight against Eddie Alvarez (a $12 million purse) and signing bonuses from his $30 million contract. However, this was only a portion of his total income, which also included sponsorships and endorsements.
Q: Was Conor McGregor’s 2017 net worth really $100 million?
A: No. While media reports speculated about a $100 million+ net worth, industry estimates at the time placed his net worth at £20–30 million. The confusion arose because brand value and liquid assets were often mixed. His tax filings showed £12.5 million in income, but this didn’t account for debts, unrecovered investments, or illiquid assets like Pro18.
Q: Did his whiskey brand, The Well, make him money in 2017?
A: No, not significantly. The Well whiskey was launched in 2017, but it didn’t generate major revenue until 2018–2019. Early sales were limited, and the brand was still building distribution. McGregor’s cannabis investments (like Canopy Growth) were also early-stage, with no immediate payouts.
Q: How did Pro18 affect his 2017 finances?
A: Pro18 was a financial drain in 2017. While it boosted his media profile, the European soccer venture was losing money as McGregor invested in player acquisitions and infrastructure. The real returns came later, when Pro18 was sold in 2020 for £100 million, but in 2017, it was a high-risk, low-reward gamble.
Q: Were his sponsorship deals more valuable than his fight purses?
A: Yes, in the long run. While his UFC purses were lucrative for single events, his sponsorships (Reebok, Montblanc, Tag Heuer) were multi-year contracts that provided steady income. For example, his Reebok deal was worth $10 million over three years, meaning $3–4 million annually—more than some of his individual fight earnings.
Q: Did he pay taxes on his UFC earnings differently than other athletes?
A: No, but his income structure was unique. Since his UFC contract was front-loaded, he paid taxes on bonuses upfront, while later-year earnings (like PPV splits) were taxed differently. His sponsorship income was also taxed separately, meaning his effective tax rate was higher than a fighter with evenly distributed earnings. Ireland’s tax laws (12.5% corporate tax) also played a role in how his business ventures were structured.
Q: How did his 2017 net worth compare to other UFC fighters?
A: In 2017, McGregor’s net worth was in a league of its own. Fighters like Georges St-Pierre (GSP) and Jon Jones had high UFC earnings, but McGregor’s brand value and sponsorships gave him an edge. While GSP’s net worth was estimated at $40–50 million, McGregor’s was still growing, with future business ventures (like Pro18) poised to surpass traditional athlete wealth.
Q: What was the biggest financial mistake he made in 2017?
A: Overleveraging on Pro18. While the investment boosted his profile, it burned cash without immediate returns. His real estate purchases (like the Miami penthouse) were also high-cost assets that didn’t generate income. The biggest risk was assuming his fighting prime would last forever—a mistake many athletes make when diversifying too early.
