Breaking Down the Numbers
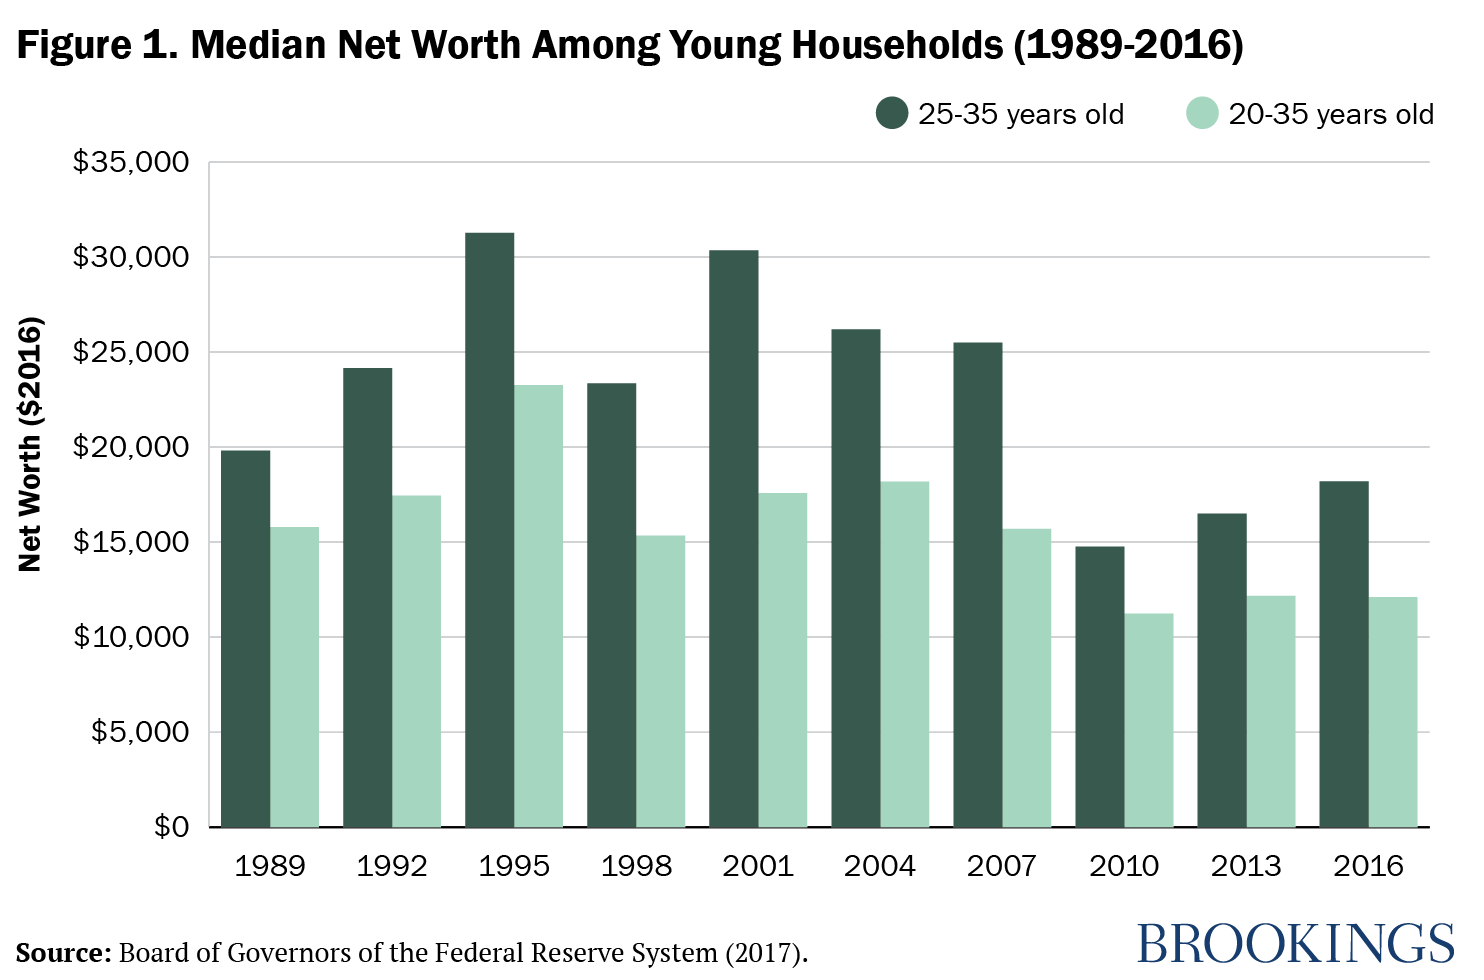
The average millennial net worth is a product of three interlocking forces: economic conditions, personal financial habits, and policy environments. Unlike previous generations, millennials entered adulthood during the 2008 financial crisis, which delayed career momentum for many. Student loan debt—now exceeding $1.7 trillion nationally—acts as a wealth drain, with borrowers in their 30s owing an average of $28,000, according to the Federal Reserve. Even those without degrees face stagnant wage growth, while housing costs in major cities have outpaced salary increases by nearly 50% over the past decade. The result? A generation that’s wealthier on paper than Gen X was at the same age, but with far less liquidity. What’s often overlooked is how these numbers vary by geography. In San Francisco or New York, the average millennial net worth is inflated by tech salaries and venture capital windfalls, but in Detroit or Memphis, it reflects lower home values and fewer high-paying local jobs. The Federal Reserve’s Survey of Consumer Finances reveals that millennials in the top 10% of earners have net worths nearing $1 million, while those in the bottom 25% struggle to clear $10,000. The median—$72,000 for millennials aged 35–44—paints a more accurate picture of the generation’s financial reality: precarious, but not uniformly dire.The Verified Baseline
Publicly available data from the Federal Reserve and Pew Research Center provides the most reliable benchmarks for the average millennial net worth. As of 2022, the median net worth for millennials aged 35–44 stood at $72,000, up from $53,000 in 2016—a gain driven largely by stock market recovery and home price appreciation. However, this median obscures critical details: homeownership rates for millennials remain 10 percentage points lower than for Gen X at the same age, and retirement savings lags, with only 41% of millennials reporting any 401(k) contributions. The data also confirms that racial wealth gaps persist; Black and Hispanic millennials have net worths 30–40% lower than their white counterparts, even when controlling for income. The most cited source, the Federal Reserve’s triennial Survey of Consumer Finances, breaks down net worth by age and income percentile. For millennials aged 25–34, the median net worth in 2022 was $45,000, with the top 10% holding $300,000+ and the bottom 25% under $5,000. These figures align with broader trends: millennials are the most educated generation in U.S. history, yet their wealth accumulation hasn’t kept pace with their qualifications. The disconnect stems from structural costs—student loans, childcare, healthcare—that weren’t as pronounced for earlier generations.What the Estimates Suggest
Beyond verified data, industry estimates and anecdotal trends offer context for the average millennial net worth. Financial planners suggest that millennials entering their 40s will see net worths climb 2–3x by retirement if they maintain disciplined saving, but this assumes stable employment and no major financial shocks. Estimates from wealth management firms like Fidelity project that millennials with $100,000+ in investable assets by age 35 are on track for $2 million+ by 65—provided they avoid lifestyle inflation and capitalize on compound growth. However, these projections rely on optimistic assumptions about market returns and career stability. Other estimates focus on the “side hustle” economy, where gig work and freelancing supplement traditional incomes. A 2023 McKinsey report found that 40% of millennials derive 20% or more of their income from non-primary sources, which can boost net worth but also introduce volatility. For example, a millennial earning $80,000 from a corporate job but $20,000 from consulting may appear wealthier than someone on a $100,000 salary with no additional streams. These estimates highlight a key reality: the average millennial net worth is less about fixed figures and more about adaptive strategies in an unstable economy.
Case Study: A Closer Look
Consider the experience of a 38-year-old software engineer in Austin, Texas, whose average millennial net worth trajectory reflects both opportunity and constraint. She entered the workforce in 2012 with $30,000 in student debt, a common starting point for millennials in professional fields. By 2020, her salary had grown to $110,000, but 60% of her take-home pay went toward debt repayment, rent, and healthcare—leaving little for investments. Her net worth in 2020 was $85,000, primarily tied to her home (purchased in 2018) and a modest 401(k) balance. The pandemic then disrupted her side income from freelance writing, temporarily halting her wealth growth. Her story illustrates how the average millennial net worth is shaped by three critical factors: debt burden, asset allocation, and external shocks. While her peers in tech with lower debt or equity compensation saw net worths exceed $200,000, hers stagnated until she refinanced her loans in 2022 and redirected savings into index funds. The case underscores that millennial wealth isn’t static—it’s a series of trade-offs between liquidity and long-term growth.“You can’t out-earn bad systems. My net worth would’ve been double if I’d bought my home in 2015, but I was paying off loans then. Now I’m playing catch-up, and the rules keep changing.” — A 38-year-old Austin software engineer
| Factor | Estimated Impact on Net Worth Growth |
|---|---|
| Student Debt Repayment (2012–2020) | Delayed home purchase by 2 years; ~$50,000 less in equity accumulation. |
| Side Income Volatility (2020–2022) | Temporarily reduced savings rate by 15–20% during pandemic. |
| Refinancing & Investment Shift (2022–2024) | Projected $30,000+ increase in net worth annually if market trends hold. |
What This Means Going Forward
The average millennial net worth isn’t just a reflection of past economic conditions—it’s a predictor of future financial resilience. Millennials are the first generation to face simultaneous crises: housing unaffordability, healthcare costs, and retirement insecurity. Yet, they’re also the most financially literate generation, with 70% tracking spending via apps and 55% using robo-advisors, per a 2023 Bankrate survey. This duality suggests that while structural barriers persist, millennials are developing tools to navigate them. The challenge lies in scaling these strategies—whether through policy changes (e.g., student debt relief) or cultural shifts (e.g., prioritizing wealth-building over consumption). What’s clear is that the average millennial net worth will diverge sharply over the next decade. Those who leverage high-income skills, automate savings, and mitigate debt will see net worths 3–5x by retirement. Others, particularly in low-wage sectors or without college degrees, may struggle to surpass $100,000 by age 50. The gap isn’t just generational—it’s a function of access. Millennials who inherit wealth, receive employer-matched retirement contributions, or benefit from family networks will outpace their peers by a wide margin. The question isn’t whether the average millennial net worth will rise, but how equitably that rise will be distributed.
Conclusion
The data on the average millennial net worth tells a story of resilience amid adversity, but also of systemic inequity. Millennials are wealthier than Gen X was at the same age—but only in median terms. The reality for most is a precarious balance between debt, housing costs, and the fading promise of traditional retirement. What’s often missing from the conversation is agency: millennials aren’t passive victims; they’re recalibrating their financial strategies in real time. From prioritizing homeownership over luxury spending to embracing gig economies as wealth-building tools, the generation is redefining what “average” means. The implications for policymakers and financial advisors are stark. If the average millennial net worth continues to lag behind earlier generations, the economic consequences will ripple through Social Security, healthcare, and housing markets. The solution isn’t just personal—it requires structural changes, from student debt reform to affordable childcare. For millennials themselves, the takeaway is clear: wealth isn’t just about earning more; it’s about controlling what you can—debt, spending, and investments—while advocating for systems that level the playing field.Comprehensive FAQs
Q: How does the average millennial net worth compare to Gen X at the same age?
The median net worth for millennials aged 35–44 ($72,000) is higher than Gen X’s median at the same age ($62,000 in 2007 dollars), but the gap narrows when adjusted for student debt and housing costs. Gen X benefited from a stronger job market in the 1990s and lower education costs, while millennials faced the 2008 crash and soaring tuition.
Q: Why do some millennials have negative net worth?
Negative net worth occurs when liabilities (debt, mortgages) exceed assets. For millennials, this is common among those with $50,000+ in student loans and no home equity. The Federal Reserve estimates 15% of millennials under 35 have negative net worth, primarily due to high debt-to-income ratios and limited asset accumulation.
Q: Can millennials realistically achieve a $1 million net worth by retirement?
Yes, but only for those in the top 20% of earners with disciplined saving. Fidelity’s “Rule of 150” suggests saving $150/month for every $1,000 of income can yield $1M+ by 65. However, 80% of millennials would need to save $500+/month in a tax-advantaged account to hit this target, which is unrealistic for many given living costs.
Q: How does homeownership affect the average millennial net worth?
Homeownership is the single largest driver of millennial wealth. The median net worth for millennial homeowners is $180,000, versus $30,000 for renters. However, high down payments and mortgage costs have delayed homebuying for many, with only 44% of millennials owning homes by age 35—down from 60% for Gen X.
Q: Are millennials saving enough for retirement?
No. The average millennial has $35,000 in retirement savings, with 41% contributing to a 401(k). Financial advisors recommend saving 15% of income, but only 28% of millennials meet this benchmark. The median retirement account balance for millennials is $12,000, far below the $100,000+ needed for modest retirement income.
Q: How does student debt impact the average millennial net worth?
Student debt reduces net worth by $20,000–$50,000 over a lifetime, depending on repayment terms. Millennials with bachelor’s degrees owe $28,000 on average, while graduate debt holders face $50,000+. Even after repayment, the opportunity cost—delayed homebuying, lower risk tolerance—can cut net worth growth by 30–40% compared to debt-free peers.
Q: Will the average millennial net worth recover by 2030?
Partial recovery is likely, but with significant regional and income-based variations. The Federal Reserve projects median millennial net worth to reach $120,000–$150,000 by 2030, assuming stable employment and modest inflation. However, 20% of millennials may see stagnant or declining net worth due to wage stagnation, healthcare costs, and housing market volatility.
Q: What’s the biggest myth about millennial wealth?
The myth that millennials are “financially irresponsible” ignores structural barriers. While some overspend, the average millennial saves 5–7% of income (vs. Gen X’s 3–5%), but faces higher costs for education, healthcare, and childcare. The real issue isn’t personal habit—it’s systemic: student debt, wage suppression, and asset inflation that outpace earnings.
