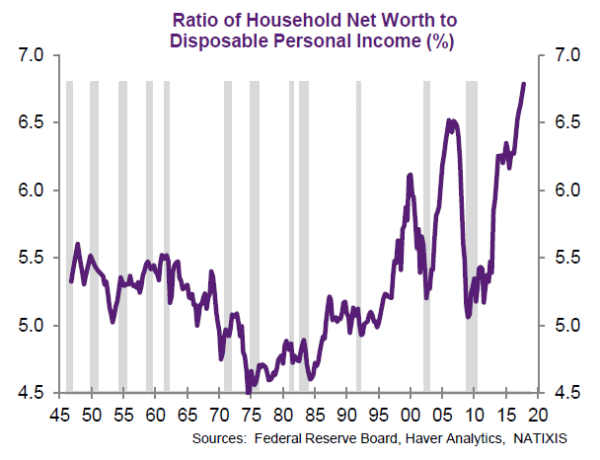
6 Things Worth Knowing About the Ratio of Household Net Worth to Income
The ratio of household net worth to income isn’t just a number—it’s a story. It tells us who’s building generational wealth, who’s stuck in a cycle of debt, and where systemic failures leave families struggling. Below are six key insights that reshape how we think about money.1. The ratio has collapsed for younger generations
For decades, the ratio of household net worth to income grew steadily, especially for those in their 40s and 50s. But for Millennials and Gen Z, the picture is stark. According to Federal Reserve data, the median net worth of households headed by someone under 35 fell by nearly 30% between 2007 and 2021, even as their incomes stagnated. The ratio of net worth to income for this group now sits at roughly 2.5:1—meaning a household earning $60,000 might have just $150,000 in assets after debt. The culprits? Skyrocketing housing costs, student loans, and the fact that entry-level wages haven’t kept pace with essential expenses. What’s worse, this decline isn’t temporary. Unlike past downturns, where younger workers eventually caught up, today’s economic conditions—rising interest rates, corporate layoffs, and the cost of childcare—suggest the ratio may not rebound for years. For many, homeownership, once the primary wealth-building tool, is now out of reach unless they inherit or receive financial gifts. The ratio isn’t just a personal failure; it’s a generational headwind.2. Homeownership remains the single largest wealth multiplier
The ratio of household net worth to income is heavily skewed by real estate. For older Americans, home equity accounts for over 60% of total net worth, according to the Urban Institute. A home isn’t just shelter; it’s the most reliable asset for building wealth over time. But this advantage is fading. In cities like San Francisco or New York, where median home prices exceed $1 million, first-time buyers often need parental assistance or inheritances just to enter the market. The result? A shrinking pool of households with high net worth-to-income ratios, while those who own homes see theirs balloon disproportionately. The flip side is equally stark: renters, who make up nearly 40% of U.S. households, have a net worth ratio that’s one-third that of homeowners. Even when adjusted for income, the gap persists. This isn’t just about choice—it’s about access. Zoning laws, predatory lending practices in certain neighborhoods, and the lack of affordable starter homes all distort the ratio. Without intervention, the wealth gap will widen as younger generations are priced out of the only asset that historically lifts net worth relative to income.3. Student debt is a wealth killer—even for high earners
Student loans don’t just reduce disposable income; they shrink the ratio of net worth to income by delaying asset accumulation. A 2023 Brookings Institution study found that borrowers with graduate degrees but high debt loads had net worth ratios 20% lower than similar earners without loans. The reason? Student debt forces graduates to delay home purchases, investing, or even saving for retirement. For example, a lawyer earning $150,000 with $100,000 in student debt may have a net worth ratio of 1.8:1—far below peers who entered the workforce debt-free. The impact isn’t limited to the borrowers themselves. Parents who co-signed loans or took out PLUS loans to help children often see their own net worth ratios stagnate, as they prioritize repayments over investments. Unlike a mortgage, which builds equity, student debt is an income drag with no appreciating asset attached. This is why even high-earning professionals with advanced degrees can find themselves in the bottom quartile of net worth-to-income distributions.4. The ratio varies wildly by race and geography
No discussion of the ratio of household net worth to income is complete without addressing racial disparities. The median white household has a net worth 10 times that of the median Black household, according to the Federal Reserve’s Survey of Consumer Finances. When you adjust for income, the ratio for white families is still nearly 5 times higher. This isn’t coincidence—it’s the result of redlining, predatory lending, wealth stripping through incarceration, and the lack of intergenerational wealth transfers in Black and Latino families. Geography plays a role too. In states with strong labor unions, progressive tax policies, and affordable housing—like Massachusetts or Minnesota—the ratio tends to be higher. Conversely, in sunbelt states with weak wage growth and high cost of living, such as Florida or Texas, the ratio is often 15-20% lower than the national average. Even within cities, neighborhoods with historic disinvestment see ratios depressed by decades of lost equity. The ratio isn’t just a personal metric; it’s a geographic and racial equity issue."Wealth isn’t just about what you earn—it’s about what you own, and who gets to own what. The ratio of net worth to income is the best way to see how policy, history, and luck shape financial outcomes." — Darrick Hamilton, economist and professor at The New School
5. Retirement savings are the wild card
For most Americans, retirement accounts—401(k)s, IRAs, and pensions—are the second-largest component of net worth, after home equity. But the ratio of net worth to income here is volatile. A household earning $120,000 with $300,000 in a 401(k) might have a healthy ratio of 2.5:1, while a similar earner with only $50,000 in savings could see that ratio drop to 0.4:1. The problem? Only 60% of workers have access to a retirement plan, and among low-wage earners, participation drops to 40%. Without employer matches or automatic enrollment, the ratio suffers. The ratio also reveals a gender gap. Women, who live longer and earn less on average, have retirement savings that are 30% lower than men’s, even when adjusted for income. This means their net worth-to-income ratio in retirement is often half that of men. Social Security alone won’t bridge the gap—yet many women delay saving because they assume they’ll rely on spousal benefits. The ratio here isn’t just about numbers; it’s about lifetime financial planning.6. The ratio is a leading indicator of economic crises
When the ratio of household net worth to income falls too far, it’s a warning sign. Before the 2008 financial crisis, the median net worth-to-income ratio for U.S. households was 5.5:1. By 2010, it had plummeted to 3.2:1 as home values collapsed and unemployment spiked. Today, with housing costs at record highs and wage growth stagnant, the ratio is hovering around 4.0:1—still below pre-crisis levels. Economists track this metric closely because a sharp decline signals reduced consumer spending, which can trigger recessions. The ratio also explains why stimulus checks and rent relief worked differently across income groups. Households with high net worth-to-income ratios had more liquid assets to absorb shocks, while those with low ratios relied on debt or government aid. This is why central banks and policymakers monitor the ratio: it predicts who will spend, who will save, and who will default in tough times. Ignoring it means missing the early signs of financial instability.
How These Facts Connect
The ratio of household net worth to income isn’t just a collection of statistics—it’s a feedback loop. High ratios enable homeownership, which boosts ratios further. Low ratios trap families in renting, student debt, or gig work, making it nearly impossible to climb. This is why the wealth gap persists across generations: those who start with a strong ratio can pass assets to their children, while those who don’t are left playing catch-up with every economic cycle. The data also reveals a hidden cost of modern life. Rising education costs, healthcare expenses, and housing inflation have all compressed the ratio for younger generations. Meanwhile, older Americans—who benefited from lower home prices, stronger unions, and fewer student loans—enjoy ratios that allow them to retire comfortably. The result? A two-tiered economy: one where wealth compounds for those who already have it, and another where debt and stagnant wages keep others trapped. | Factor | Impact on Net Worth-to-Income Ratio | Demographic Most Affected | Policy/Leverage Point | |--------------------------|----------------------------------------|----------------------------------------|------------------------------------------| | Homeownership | +3.0 to +5.0x higher ratio | Homeowners over 50 | Zoning reform, first-time buyer grants | | Student Debt | -0.5x to -1.5x ratio | Millennials, graduate professionals | Loan forgiveness, income-based repayment | | Retirement Savings | +1.0x to +2.5x ratio (if optimized) | Workers with 401(k) access | Auto-enrollment, employer matches | | Racial Disparities | -5x to -10x ratio (Black vs. White) | Black and Latino households | Wealth-building programs, tax credits | | Geographic Location | -0.2x to -0.3x ratio (high-cost areas) | Renters in coastal cities | Affordable housing incentives |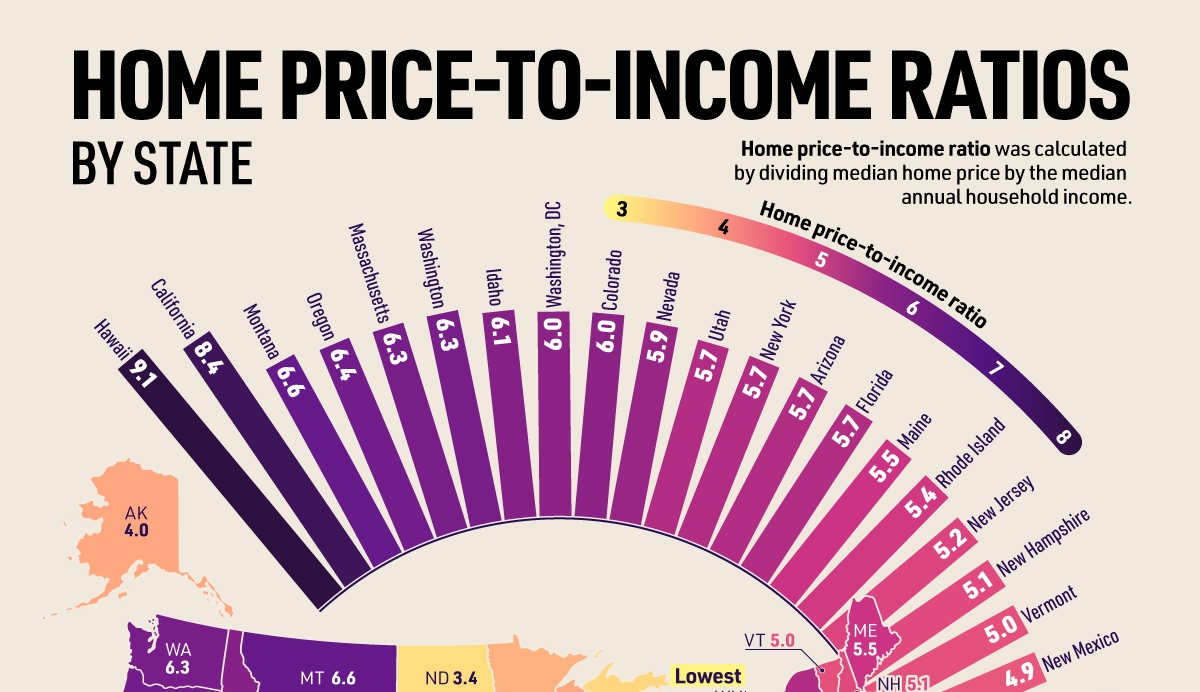
Conclusion
The ratio of household net worth to income is more than a financial metric—it’s a report card on economic opportunity. It shows who’s winning in today’s economy and who’s being left behind. For individuals, it’s a wake-up call: income alone doesn’t guarantee wealth, and debt can erase decades of progress. For policymakers, it’s a roadmap: without targeted interventions, the ratio will continue to favor those who already have advantages. The good news? The ratio can be improved—through smarter saving, strategic debt management, and advocacy for policies that level the playing field. But the first step is understanding what it really measures. It’s not just about how much you make; it’s about what you control, what you owe, and what you can pass forward. In an era of widening inequality, that distinction matters more than ever.Comprehensive FAQs
Q: How do I calculate my own ratio of net worth to income?
A: Subtract your total liabilities (debt, mortgages, loans) from your total assets (cash, investments, home equity, retirement accounts). Divide that net worth by your annual gross income. For example, if your net worth is $250,000 and you earn $80,000 yearly, your ratio is 3.1:1. Most financial advisors consider a ratio above 3.0:1 as healthy for long-term stability.
Q: What’s a “good” ratio of net worth to income?
A: There’s no universal benchmark, but historical data suggests: - Under 2.0:1: Vulnerable to economic shocks; may struggle with emergencies or retirement. - 2.0–4.0:1: Solid foundation, but could improve with debt reduction or asset growth. - 4.0+:1: Strong financial position, often seen in older households or those with significant home equity/investments.
Q: Does the ratio of net worth to income vary by country?
A: Yes. In Nordic countries, where social safety nets reduce housing costs and healthcare expenses, the ratio tends to be more balanced across income groups. In U.S. and UK, where homeownership is the primary wealth driver, the ratio is more polarized. For example, the median net worth-to-income ratio in Denmark is around 5.0:1, while in the U.S., it hovers near 4.0:1—but with far greater disparity between rich and poor.
Q: Can a high income but low net worth ratio still be stable?
A: Not necessarily. A high earner with a low ratio (e.g., $150,000 income, $200,000 net worth) may have high debt or liquidity risks. While they can afford luxuries, they lack a buffer for job loss, medical emergencies, or market downturns. Stability requires both income and asset growth—not just one.
Q: How does divorce or separation affect the ratio?
A: Dramatically. Divorce often splits assets (like home equity or retirement accounts) while doubling liabilities (child support, legal fees). A couple with a 5.0:1 ratio pre-divorce might see it drop to 1.5:1 post-split, especially if one spouse takes on alimony or loses primary custody of high-value assets. Remarriage can help, but without careful financial planning, the ratio may never recover.
Q: Are there ways to improve a weak ratio without earning more?
A: Yes, but it requires strategic asset building: - Pay down high-interest debt (credit cards, private loans) first—this directly boosts net worth. - Increase home equity by refinancing or making extra mortgage payments. - Maximize tax-advantaged accounts (IRAs, HSAs) to grow wealth faster. - Avoid lifestyle inflation—direct extra income toward assets, not spending. - Leverage employer benefits (401(k) matches, HSA contributions) for passive wealth growth.
Q: How does inflation affect the ratio of net worth to income?
A: Inflation erodes purchasing power, but its impact on the ratio depends on asset types: - Cash and bonds lose value in inflation, lowering net worth relative to income. - Real estate and stocks often outpace inflation, protecting (or even boosting) the ratio. - Wages rarely keep up with inflation, so income stagnates while asset values fluctuate. This is why asset allocation—not just salary growth—matters for maintaining a strong ratio.
