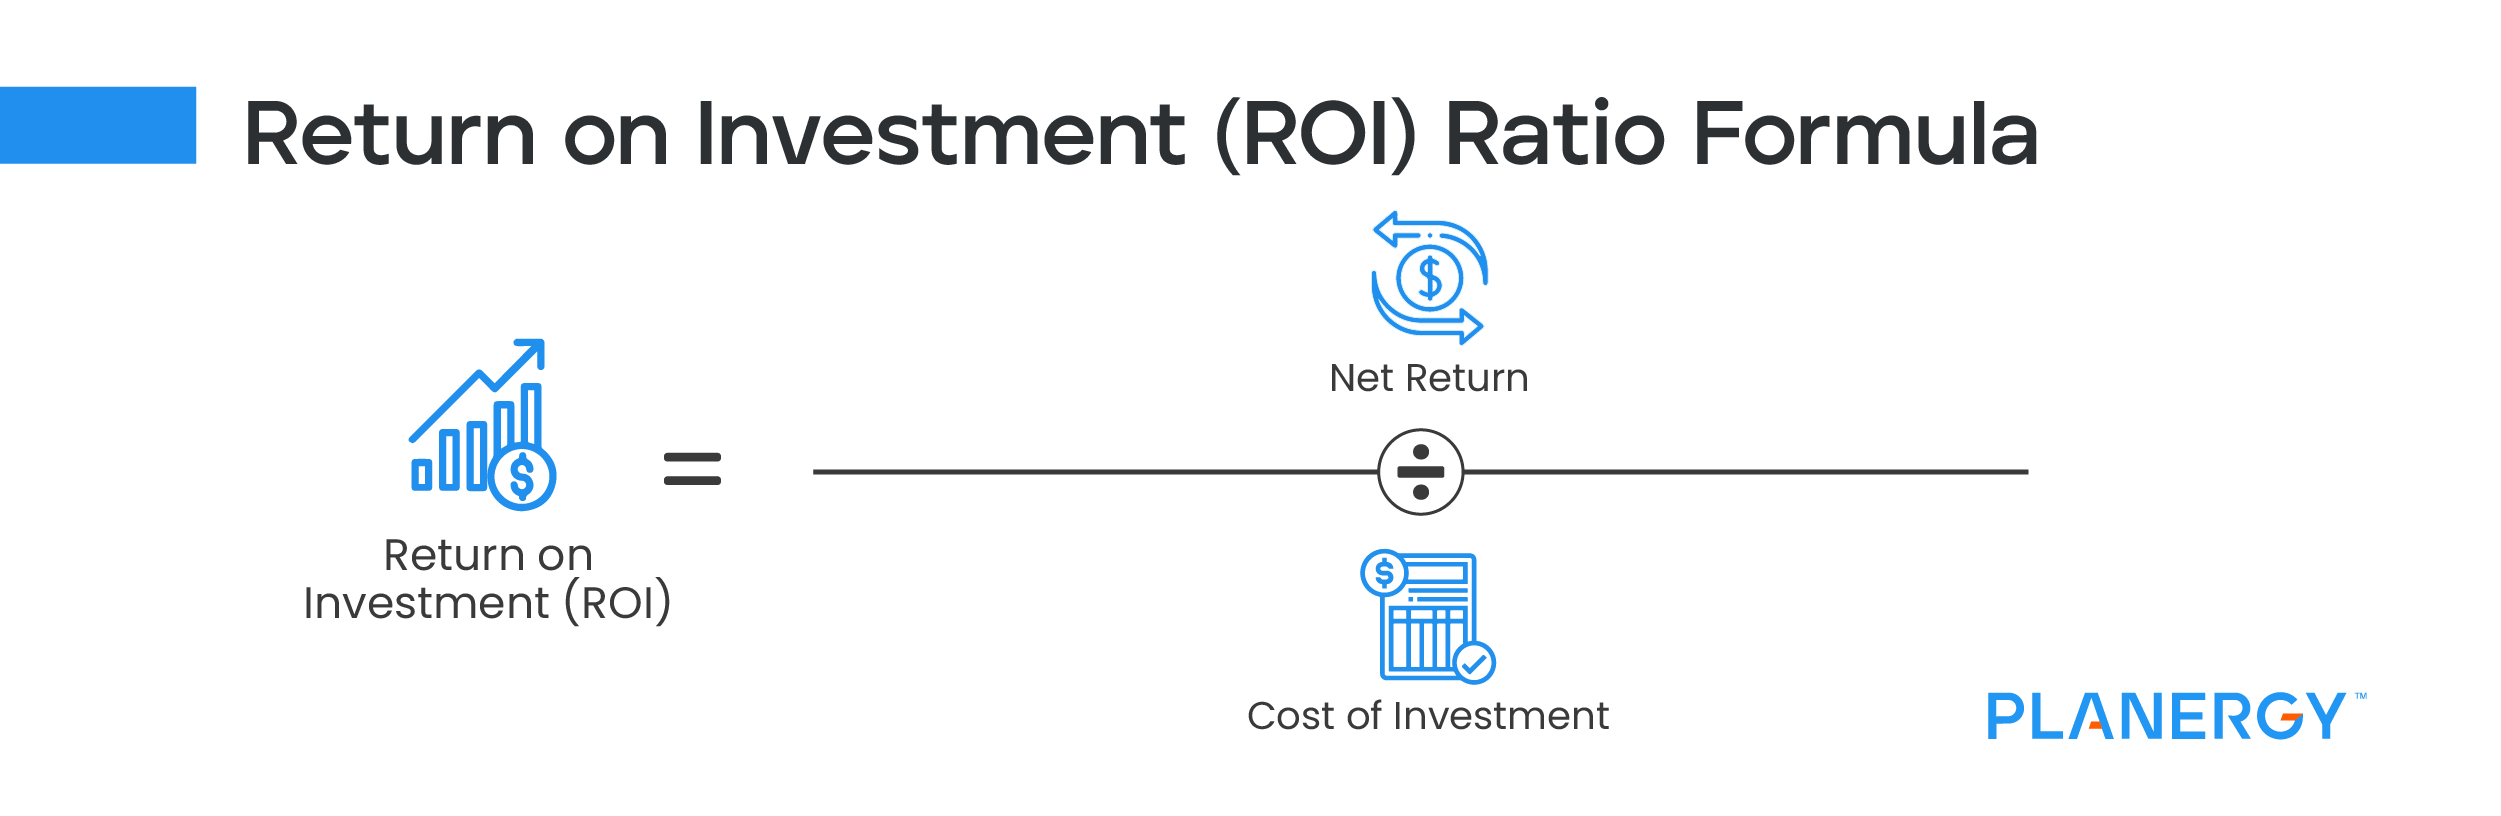
7 Things Worth Knowing About the Ratio for Return on Net Worth
The ratio for return on net worth isn’t just another financial ratio—it’s a lens that reframes how you think about wealth accumulation. It challenges the conventional wisdom that more money always means more options. Here’s what you need to understand before calculating yours.1. It’s Not Just About Investments—It’s About Everything
Most people assume the ratio for return on net worth is purely an investment metric, but that’s like judging a chef’s skill by only tasting the dessert. Your net worth includes cash, real estate, businesses, retirement accounts, and even non-liquid assets like collectibles or intellectual property. Each category has its own return profile. A rental property might yield 6% annually, while a Roth IRA with a 7% average return over 30 years effectively compounds at a far higher rate when considering tax-free growth. The ratio forces you to account for opportunity cost: that £50,000 sitting in a low-interest savings account isn’t just "safe"—it’s actively losing purchasing power to inflation, dragging down your overall return. What’s often overlooked is how liabilities factor into the equation. A mortgage with a 3% interest rate might seem like a good deal, but if your investments are only returning 4%, the net effect is a negative contribution to your ratio for return on net worth. Similarly, a car loan or credit card debt at 18% interest is a wealth destroyer, not just an expense. The ratio doesn’t just measure what your assets are doing—it measures what your entire financial ecosystem is doing.2. The Higher the Ratio, the More Leverage You Have
A ratio for return on net worth above 5% is often considered strong for someone in their peak earning years. Above 7%? You’re in the realm of financial acceleration, where compounding starts working in your favor at an exponential rate. The reason this matters is leverage: a higher ratio means you can achieve financial independence faster, take more career risks (like starting a business or switching to part-time work), or weather economic downturns without panic. Historically, the S&P 500 has returned around 10% annually over long periods, but individual portfolios rarely hit that due to fees, taxes, and behavioral mistakes. That’s why ultra-high-net-worth individuals often aim for ratios in the 8–12% range—not by chasing speculative bets, but by structuring their wealth to benefit from multiple return streams. The flip side is that a ratio below 3% is a red flag. At that level, you’re essentially relying on human capital (your ability to earn) rather than passive income or asset growth. This is why many high-earning professionals in their 40s or 50s suddenly feel financial panic—they’ve built a large net worth but never optimized it for returns. The ratio for return on net worth is the early warning system for this trap.3. Lifestyle Inflation Is the Silent Killer of Your Ratio
There’s a psychological phenomenon where people with growing incomes spend more rather than invest more. A £50,000 salary might see £30,000 go to rent, groceries, and discretionary spending. A £150,000 salary might see £100,000 allocated the same way—just with fancier labels. The ratio for return on net worth collapses under this pressure because the denominator (net worth) grows, but the numerator (annual returns) stagnates. The solution isn’t austerity—it’s intentional allocation. Someone with a £1 million net worth who spends £80,000 a year on a lavish lifestyle might only have £20,000 left for investments, yielding a paltry 2%. That same person could live on £60,000, invest the rest, and see their ratio climb to 5% or higher. The ratio exposes another harsh truth: conspicuous consumption doesn’t build wealth. A £200,000 annual budget for a family of four might sound luxurious, but if your net worth is £3 million, that’s a 6.6% burn rate—leaving little room for growth. Meanwhile, someone with the same net worth but a £80,000 lifestyle could deploy the rest into assets yielding 8%, creating a self-sustaining cycle.4. Taxes and Fees Eat Returns Faster Than You Think
A common mistake is assuming that a 7% investment return is a 7% gain—but after taxes, fees, and inflation, the real return might be closer to 4%. The ratio for return on net worth must account for these friction costs. For example: - Capital gains taxes can reduce equity returns by 15–25% depending on jurisdiction. - Management fees on mutual funds or ETFs might shave off 0.5–1% annually. - Inflation erodes purchasing power, turning a 5% nominal return into a 2% real return in high-inflation periods. High-net-worth individuals often use tax-efficient structures—like holding stocks in tax-advantaged accounts, using trusts, or investing in assets with deferred taxation—to preserve their ratio. The difference between a 6% ratio and a 4% ratio over 20 years is the gap between financial freedom and perpetual employment.5. The Ratio Changes as You Age—And That’s Okay
A 25-year-old with a £50,000 net worth generating £1,000 in annual returns has a 2% ratio. That’s not terrible for someone early in their career, but it’s also not optimized. By 40, that same person might have a £500,000 net worth but only £15,000 in returns—a 3% ratio. The issue isn’t the ratio itself; it’s the lack of progression. Wealth-building should follow a trajectory where the ratio improves over time, not flatlines. This is why asset diversification becomes critical in later years. A young professional might rely on a single high-growth stock or a side hustle, but as net worth grows, the focus shifts to diversified income streams—rental income, dividends, private equity, or even royalties—that collectively push the ratio higher. The ratio also reflects risk tolerance. A 35-year-old might accept a 10% ratio with volatility, while a 65-year-old might prioritize stability and settle for a 4–5% ratio. The key is aligning the ratio with your life stage—not the other way around.6. The 401(k) and IRA Are Your Ratio Multipliers
Retirement accounts aren’t just savings vehicles—they’re return accelerators. The ratio for return on net worth improves dramatically when contributions are made to tax-advantaged accounts because: - Tax deferral allows investments to grow faster. - Employer matches (if available) act as a guaranteed return. - Compound growth is amplified over decades. For example, someone contributing £10,000 a year to a 401(k) with a 7% return will have a far higher ratio than someone putting the same amount into a taxable brokerage account. The ratio doesn’t just reflect current returns—it reflects future potential. This is why financial planners often say that time in the market beats timing the market. The ratio for return on net worth is the tangible proof of that principle.7. The Ratio Reveals Your True Financial Independence Number
Most people calculate financial independence using the 4% rule—withdrawing 4% of their net worth annually without depleting it. But that’s a backward-looking metric. The ratio for return on net worth tells you what you need to earn from your assets to live comfortably. If your annual expenses are £60,000 and your ratio is 5%, you’d need a net worth of £1.2 million to cover those expenses without touching principal. If your ratio were 7%, you’d only need £857,000. The lower your ratio, the higher your financial independence number becomes—and that’s the real wake-up call. This is why ultra-high-net-worth families often structure their wealth to increase the ratio artificially. Private equity, family offices, and real estate syndications can push ratios into double digits, slashing the required net worth for financial freedom by millions. The ratio isn’t just a number—it’s the leverage that determines how much you need to retire on.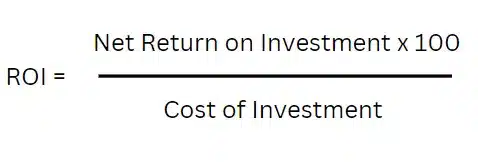
How These Facts Connect
The ratio for return on net worth isn’t a standalone number—it’s a system. It connects your spending habits, your investment choices, your tax strategy, and even your career decisions into a single, measurable outcome. The seven points above don’t exist in isolation; they’re interlocking pieces of a financial engine. For example, someone with a high ratio might afford to take a lower-paying job because their assets cover their lifestyle. Someone with a low ratio might feel forced to keep grinding at a soul-crushing job because their net worth isn’t generating enough to replace their income. The ratio also exposes the myth of the "average" investor. Financial media often celebrates the S&P 500’s 10% return, but individual portfolios rarely hit that due to fees, taxes, and behavioral errors. The ratio for return on net worth is the reality check: if your actual ratio is 3%, you’re not keeping up with the market—you’re falling behind it. This is why the most successful investors don’t just chase returns; they optimize the entire ecosystem around their net worth. Here’s how the key factors compare:| Factor | Low-Ratio Impact | High-Ratio Impact | Optimal Strategy |
|---|---|---|---|
| Investment Choices | Stagnant or low-yield assets (cash, bonds, low-dividend stocks) | Diversified growth (equities, private equity, real estate) | Balance risk and return; prioritize tax-efficient vehicles |
| Lifestyle Spending | High burn rate; little reinvestment | Moderate spending; aggressive reinvestment | Align expenses with ratio potential (e.g., £60k lifestyle vs. £100k) |
| Tax and Fees | High drag from capital gains, management fees, inflation | Minimized through tax-advantaged accounts and low-cost investments | Use trusts, Roth IRAs, and tax-loss harvesting |
| Career vs. Assets | Over-reliance on human capital; net worth grows slowly | Assets generate income; career becomes optional | Shift from "earn more" to "own more" |

Conclusion
The ratio for return on net worth is the financial equivalent of a car’s efficiency rating—it tells you whether you’re coasting or accelerating. The danger of ignoring it is that you might spend decades accumulating wealth without realizing it’s not working as hard as it could. The good news is that improving the ratio isn’t about drastic changes; it’s about small, compounding optimizations. Shifting £2,000 a year from lifestyle spending to investments at a 7% return could increase your ratio by 0.4% annually—but over 20 years, that’s the difference between a £1 million and a £1.5 million net worth. The ratio also forces a conversation about what wealth is really for. Is it a number on a statement, or is it the freedom to live on your terms? The answer lies in the ratio. Someone with a £3 million net worth but a 2% ratio might still feel trapped by their expenses. Someone with £1 million but a 6% ratio could retire early. The ratio doesn’t judge your income or your job—it judges your efficiency. And in the game of wealth, efficiency is the only thing that matters in the long run.Comprehensive FAQs
Q: How do I calculate my ratio for return on net worth?
A: Divide your total annual returns (dividends, rental income, capital gains, interest, etc.) by your current net worth. For example, if your net worth is £800,000 and your assets generate £40,000 a year, your ratio is 5%. Include all income streams—even side hustles or business profits—if they contribute to your net worth growth.
Q: Is there a "good" ratio for return on net worth?
A: There’s no universal benchmark, but here’s a rough guide: - Below 3%: Low efficiency; likely reliant on human capital. - 3–5%: Average for someone in accumulation phase. - 5–7%: Strong; suggests diversified, growing assets. - 7%+: Excellent; indicates optimized wealth structure. The "good" ratio depends on your life stage, goals, and risk tolerance.
Q: Can I improve my ratio without increasing my net worth?
A: Yes. Focus on: - Reducing expenses to free up capital for higher-yield investments. - Shifting assets into categories with better returns (e.g., moving cash to equities). - Minimizing fees and taxes (e.g., consolidating accounts, using tax-loss harvesting). - Generating passive income (dividends, rentals, royalties) to boost the numerator.
Q: Does the ratio for return on net worth account for inflation?
A: Not directly, but it should. If your ratio is calculated in nominal terms (e.g., £50,000 return on a £1M net worth = 5%), you must adjust for inflation to see the real return. For example, a 5% nominal return in a 3% inflation environment is only a 2% real return. Use the Fisher equation (real return = nominal return – inflation) for accuracy.
Q: How does debt affect the ratio for return on net worth?
A: Debt can increase or decrease your ratio depending on its use: - Good debt (e.g., a mortgage on a rental property yielding 6% while the loan costs 3%) can boost your ratio. - Bad debt (e.g., credit card interest at 18%) drags down your ratio by increasing your cost of capital. Always compare the after-tax cost of debt to the after-tax return of the asset it’s financing.
Q: Can the ratio for return on net worth be negative?
A: Yes. If your liabilities (debt, taxes, fees) exceed your asset returns, your ratio can dip below zero. For example: - A £1M net worth with £80,000 in annual expenses (lifestyle + debt) but only £60,000 in returns results in a -2% ratio. This is a warning sign that your wealth is shrinking in real terms.
Q: How often should I track my ratio for return on net worth?
A: At least quarterly, but ideally annually. Net worth fluctuates with market conditions, and income streams can change. Tracking it regularly helps you: - Identify leaks (e.g., underperforming investments). - Adjust spending in response to ratio trends. - Rebalance asset allocation to maintain efficiency. Automate calculations using spreadsheets or financial software to monitor trends over time.
