Where It All Began
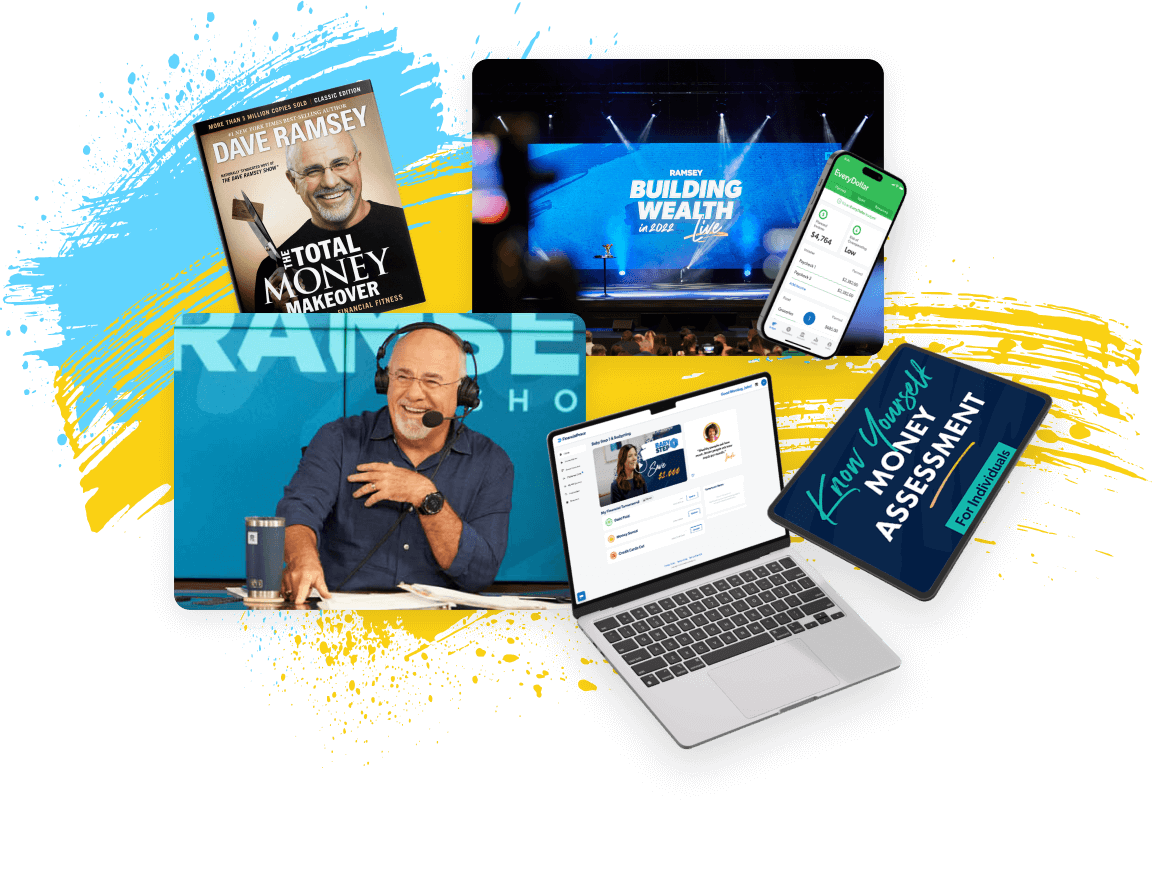
The story of the Ramsey Solutions Calculator starts not with technology, but with a man and a message. Dave Ramsey, a former financial planner turned radio host, had spent years advising clients who were drowning in debt. His frustration wasn’t with their circumstances, but with the tools available to them. Most calculators at the time were either too complex for average users or so generic they failed to address the emotional and psychological barriers to financial change. Ramsey’s solution? A tool that mirrored his own philosophy: clear, no-nonsense, and focused on behavior as much as numbers. The early versions of what would become the Ramsey Solutions Calculator were handcrafted in the late 1990s, long before the term "fintech" was common. Ramsey’s team developed a simple spreadsheet that applied his debt snowball method—a strategy where users pay off their smallest debts first for quick wins, then roll that momentum into larger balances. The calculator didn’t just show how long it would take to pay off debt; it showed how feeling progress could change a person’s relationship with money. That was the innovation: turning a mathematical exercise into a psychological tool.The Early Signs
Even in its rudimentary form, the calculator had an immediate impact. Users who struggled with traditional budgeting found relief in its straightforward approach. There were no hidden fees, no upsells, no confusing graphs. Just a clear path: input your debts, your income, and your monthly budget, and the tool would tell you exactly how to attack them. The feedback was overwhelmingly positive, but the real breakthrough came when Ramsey’s team realized something critical—people weren’t just using the calculator to manage debt. They were using it to plan for the future. By the early 2000s, the tool had evolved into a more comprehensive financial planning system. It now included features for tracking savings, retirement contributions, and even college funding. The shift was subtle but significant: the Ramsey Solutions Calculator wasn’t just about getting out of debt; it was about building a financial foundation. This expansion reflected Ramsey’s broader mission—to help people move from survival mode to thriving. The calculator became a bridge between immediate relief and long-term security.The Turning Point
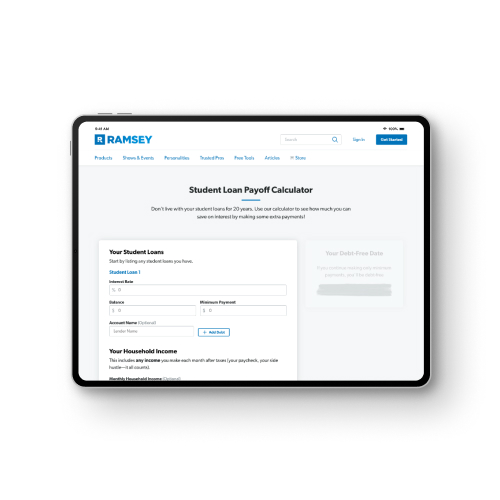
The moment the Ramsey Solutions Calculator transitioned from a niche tool to a mainstream resource came in 2005, when Ramsey’s organization, Ramsey Solutions, launched its first digital platform. Up until then, users had relied on static spreadsheets or manual calculations. The new online version was interactive, updated in real time, and accessible from anywhere. It wasn’t just a calculator anymore—it was a financial dashboard. What made the difference wasn’t the technology itself, but how it was integrated into Ramsey’s larger ecosystem. Users could now sync their progress with Ramsey’s books, podcasts, and live events. The calculator became the hub of a community where financial struggles were met with accountability and encouragement. This wasn’t just about numbers; it was about belonging to something bigger. The turning point wasn’t the tool—it was the culture it helped create."The calculator didn’t just show you where you were; it showed you how to get where you wanted to be. And for a lot of people, that was the first time they’d ever had a real plan." — Ramsey Solutions Developer, 2006
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| Late 1990s – Early 2000s | The calculator began as a manual spreadsheet applying the debt snowball method. Early adopters praised its simplicity, but it lacked integration with other financial tools. |
| 2005 – 2010 | Ramsey Solutions launched its first digital platform, making the calculator interactive and accessible online. This period saw the addition of savings and retirement planning features. |
| 2015 – Present | The tool expanded into a full financial planning suite, including mobile apps, automated syncing with bank accounts, and advanced goal-tracking. User engagement surged as the tool became more intuitive. |
Lessons From the Journey
- Simplicity Wins: The calculator’s success proves that financial tools don’t need to be complex to be effective. Many users abandon sophisticated software because it’s overwhelming—this tool kept it basic.
- Behavior Over Math: The real power lies in how it frames financial decisions. Users don’t just see their debt; they see their progress, which motivates action.
- Community Drives Adoption: The tool’s integration with Ramsey’s broader resources (books, podcasts, events) created a sense of accountability that standalone calculators lack.
- Adaptability Matters: As financial needs evolved, so did the calculator. What started as a debt tool now includes retirement, college savings, and even emergency fund planning.
- Trust Is Non-Negotiable: Ramsey’s reputation for transparency—no hidden fees, no upsells—built loyalty that generic financial tools struggle to match.
- Mobile Access Changed Everything: The shift to apps and real-time syncing made the tool accessible to a younger, more tech-savvy audience.
Where Things Stand Today
The Ramsey Solutions Calculator today is a far cry from its spreadsheet origins. It now operates as part of a comprehensive financial planning suite, complete with mobile apps, automated bank syncing, and customizable goal-tracking. Users can input their entire financial picture—debts, savings, investments, and even side hustle income—and receive a tailored plan. The tool has also expanded into niche areas, such as helping small business owners manage cash flow or families plan for major expenses like weddings or home renovations. What hasn’t changed is the core philosophy: financial freedom starts with a plan. The calculator remains free to use, with premium features available for those who want deeper insights. This accessibility has kept it relevant in an era where many financial tools are gated behind paywalls. Industry estimates suggest that millions of users rely on it annually, making it one of the most trusted names in personal finance software.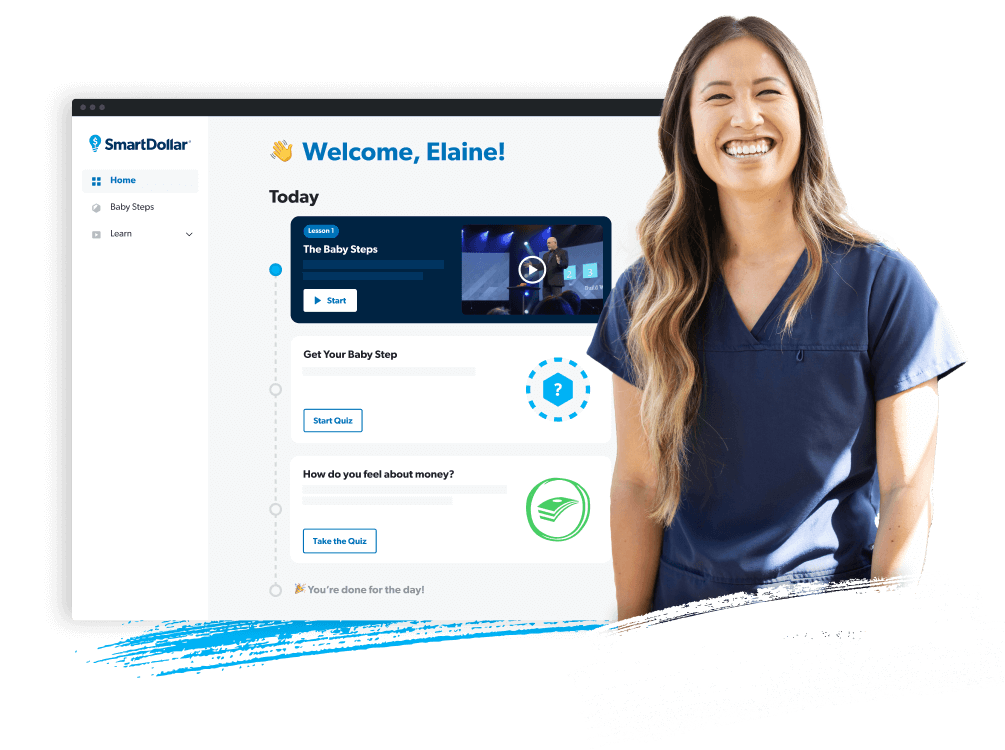
Conclusion
The Ramsey Solutions Calculator didn’t just solve a problem—it changed how people think about money. It took a concept that once seemed daunting (budgeting, debt payoff, saving) and made it feel achievable. Along the way, it proved that financial tools could be both powerful and approachable, a rare combination in an industry often dominated by complexity. For many, it was the first step toward a life free from financial stress. As the tool continues to evolve, its legacy isn’t just in the numbers it crunches, but in the lives it’s helped transform. Whether it’s a single parent paying off credit cards, a young professional saving for a home, or a retiree planning for the future, the calculator remains a constant—a reminder that financial health is within reach, one step at a time.Comprehensive FAQs
Q: Is the Ramsey Solutions Calculator really free?
The basic version of the calculator is free to use, but Ramsey Solutions offers premium tools and resources for a fee. These include advanced planning features, coaching programs, and access to exclusive content. The free version covers core functionalities like debt payoff and budgeting.
Q: How accurate is the calculator compared to other financial tools?
The calculator’s accuracy depends on the data users input. Unlike some tools that rely on algorithms or market predictions, the Ramsey Solutions approach is rule-based, meaning it follows a clear methodology (like the debt snowball) rather than making assumptions. This makes it more predictable for users who prefer transparency over automated suggestions.
Q: Can I use it for business finances, or is it only for personal use?
While the calculator was designed for personal finance, Ramsey Solutions has expanded its tools to include basic business financial planning, such as cash flow tracking and debt management for small businesses. However, it’s not a full accounting system—users with complex business needs may require additional software.
Q: Does the calculator sync with my bank accounts?
Yes, the premium version of the calculator allows users to automatically sync with their bank accounts, pulling in transactions for easier tracking. The free version requires manual input, which can be time-consuming but ensures users stay engaged with their financial habits.
Q: What’s the difference between the debt snowball and debt avalanche methods in the calculator?
The debt snowball method prioritizes paying off the smallest debts first for quick psychological wins, while the debt avalanche focuses on the highest-interest debts to save money long-term. The calculator lets users choose which method aligns with their goals—behavioral (snowball) or mathematical (avalanche).
Q: How often should I update my information in the calculator?
For the most accurate results, users should update their information monthly, especially if their income, expenses, or debts change. The calculator’s real-time features (in premium versions) make this easier, but even manual updates ensure the plan stays aligned with current financial reality.
Q: Can I use the calculator if I don’t have any debt?
Absolutely. The calculator isn’t just for debt payoff—it’s also a powerful tool for savings, retirement planning, and goal-setting. Users without debt can input their savings targets, investment allocations, and other financial goals to create a comprehensive plan.
