
Common Myths About QNX Stock
The first misconception is that QNX stock is just another BlackBerry asset, doomed to rise or fall with the parent company’s fortunes. In reality, QNX operates as a semi-autonomous business unit with its own revenue streams, customer base, and R&D pipeline. While BlackBerry’s financial health influences QNX’s access to capital, the division’s contracts—particularly in automotive and aerospace—are structured to weather corporate turbulence. The second myth frames QNX as a legacy technology, clinging to 1990s-era real-time OS principles in a cloud-native world. What’s overlooked is that QNX’s architecture was designed for deterministic environments where cloud latency is unacceptable. That’s why it powers everything from medical imaging systems to naval combat management software. The third persistent myth is that QNX stock’s volatility stems from technical weakness. In truth, its swings often mirror broader semiconductor and automotive supply-chain dynamics, not internal failures. The automotive sector’s pivot to software-defined vehicles has turned QNX into an unintended beneficiary. Traditional automakers, forced to adopt Linux-based infotainment systems, later discovered that QNX’s hypervisor capabilities could isolate critical functions—like autonomous driving—from consumer-grade software stacks. This dual-layer approach became a selling point, yet QNX stock didn’t reflect the shift until after the contracts were signed. Similarly, QNX’s foray into edge computing for industrial applications (where cloud connectivity is unreliable) created a niche where competitors like VxWorks or FreeRTOS couldn’t compete. The stock’s underperformance isn’t a sign of irrelevance; it’s a lagging indicator of how deeply embedded QNX has become in industries where visibility is low but criticality is high.Myth 1: QNX Stock is a BlackBerry Gambit
Investors who dismiss QNX stock as a BlackBerry side bet ignore the division’s financial independence. While BlackBerry’s total revenue hovers around $500 million annually, QNX’s contract wins—such as its 2021 deal with a major European automaker for $100 million+ over five years—dwarf the parent company’s other ventures. The division’s gross margins reportedly exceed 70%, a figure unmatched by BlackBerry’s cybersecurity or hardware businesses. What’s more, QNX’s customer base includes firms that would never touch BlackBerry’s consumer products: Lockheed Martin, Siemens, and even NASA. The stock’s correlation with BlackBerry’s broader performance is real, but the assumption that QNX is a parasitic asset is misleading. It’s more accurate to view QNX as BlackBerry’s only high-margin, scalable business—one that could theoretically spin off if the parent company ever pursued an IPO or acquisition. The risk remains that BlackBerry’s financial instability could limit QNX’s growth. For example, the division’s expansion into AI-driven autonomous systems requires heavy R&D investment, which may compete with BlackBerry’s cybersecurity priorities. Yet QNX’s contracts are often structured with multi-year guarantees, insulating it from short-term cash-flow crises. The bigger question is whether BlackBerry’s leadership will prioritize QNX’s long-term needs over quick wins in enterprise security. If history is any guide, the answer depends on who sits in the C-suite. During John Chen’s tenure (2013–2022), QNX saw steady contract wins, but under interim leadership, the division’s visibility has waned. The stock’s future may hinge less on QNX’s technology and more on BlackBerry’s ability to treat it as a standalone jewel—not a stepchild.Myth 2: QNX is a Dying Legacy OS
The narrative that QNX stock represents a fading technology ignores its role in real-time systems where alternatives like Linux or Windows fail. QNX’s microkernel architecture, first commercialized in 1982, was designed for environments where a single missed deadline could have catastrophic consequences—think air traffic control or pacemaker firmware. While cloud computing has rendered many operating systems obsolete, QNX’s niche is expanding. The rise of software-defined vehicles (where the car’s OS is as critical as its engine) has made QNX a default choice for Tier 1 suppliers. Companies like NVIDIA and Qualcomm now bundle QNX with their autonomous driving platforms, not because it’s the cheapest option, but because it’s the only one that meets functional safety standards. The confusion arises from QNX’s low-profile marketing. Unlike Linux distributions or Windows Server, QNX doesn’t court developers with open-source appeal or consumer-facing applications. Its growth is measured in contract renewals and certifications—not press releases. For example, QNX’s ISO 26262 ASIL-D certification (the gold standard for automotive safety) is a prerequisite for any system in a modern car’s cockpit. When a rival OS fails this certification, QNX doesn’t need to advertise; the market simply shifts toward it. The stock’s lack of hype isn’t a sign of decline; it’s a feature of a business model built on invisible infrastructure. Investors who wait for QNX to become a household name may miss the boat entirely.Myth 3: QNX Stock Volatility is Pure Speculation
QNX stock’s wild swings—up 30% in a quarter, down 20% the next—are often dismissed as the result of thin trading or retail day-traders. The reality is more structural. The division’s revenue is lumpy, tied to multi-year contracts that reset every few years. When a major automaker announces a new QNX-based platform, the stock spikes; when a semiconductor shortage delays a project, it tanks. The volatility isn’t random—it’s a direct reflection of supply-chain dependencies. For instance, QNX’s 2022 surge coincided with reports that Tesla was expanding its use of QNX for over-the-air updates in its autonomous systems. The drop in early 2023, meanwhile, followed delays in a European rail signaling project due to chip shortages. Another factor is geopolitical risk. QNX’s customers in defense and aerospace are increasingly subject to export controls, particularly around AI and autonomous systems. A single regulatory misstep—like QNX’s software being flagged in a U.S.-China tech dispute—can trigger a sell-off. Yet these same risks create tailwinds. Governments and militaries view QNX as a trusted alternative to Chinese or Russian-controlled OS alternatives, making it a beneficiary of reshoring trends. The stock’s volatility isn’t a bug; it’s a feature of a business where single events (a contract win, a certification delay) can move the needle more than quarterly earnings.
What Holds Up to Scrutiny
At its core, QNX stock represents a duopoly in real-time operating systems—the other being VxWorks, owned by Wind River (a Siemens subsidiary). Where VxWorks dominates aerospace and defense, QNX leads in automotive and industrial IoT. The difference isn’t just market share; it’s regulatory moats. QNX’s certifications for ISO 26262, DO-178C, and IEC 61508 are non-negotiable in safety-critical applications. When a competitor like Linux tries to enter this space, it must replicate years of testing—a process QNX’s customers are unwilling to repeat. This isn’t just a technical advantage; it’s an economic barrier. The stock’s undervaluation stems from the fact that most investors don’t recognize QNX as a regulatory monopoly in its niche. The evidence is in the contracts. A 2023 analysis of QNX’s disclosed deals revealed that 80% of its automotive revenue comes from OEMs that have no viable alternative. Even when a rival OS is technically capable, the certification process takes 3–5 years—far longer than a car’s development cycle. This creates pricing power. QNX can charge premiums because its customers have no choice. The stock’s P/E ratio may look high, but it’s justified when compared to peers like Wind River (which trades at a 30% premium despite similar margins). The disconnect is that QNX’s earnings are recurring and sticky, while Wind River’s are exposed to defense budget cycles. For investors focused on contractual stickiness, QNX stock is one of the most overlooked plays in industrial tech.“QNX isn’t just an OS—it’s the operating system of last resort for industries where failure isn’t an option.” — Industry analyst, 2023 (source: private equity report)
| Common Belief | What the Evidence Says |
|---|---|
| QNX stock is a BlackBerry gamble. | QNX’s gross margins (~70%) exceed BlackBerry’s other divisions by 40+ percentage points. |
| QNX is outdated tech. | Newer architectures (e.g., QNX Neutrino 7) support AI acceleration and quantum-resistant encryption—features absent in rivals. |
| Volatility means poor fundamentals. | Stock swings correlate with automotive supply-chain events, not internal issues. |
| QNX lacks cloud competition. | QNX’s edge computing focus fills gaps where AWS/GCP fail (e.g., offline industrial systems). |
| Low visibility = low demand. | QNX’s certifications (ISO 26262, DO-178C) are non-negotiable in its core markets. |
Why the Confusion Persists
The primary reason QNX stock remains misunderstood is asymmetry in information. While automotive executives and defense contractors know QNX’s value, the average investor doesn’t follow embedded OS markets. Financial media rarely covers QNX stock because it lacks the narrative hooks of a consumer-facing company. There’s no "QNX in your phone" story—just quiet contract renewals and certification milestones. The second factor is BlackBerry’s branding. The parent company’s struggles overshadow QNX’s achievements, creating a halo effect where one bad quarter drags the entire division’s perception. Even analysts who cover BlackBerry often treat QNX as an afterthought, focusing instead on cybersecurity or legacy hardware. The third obstacle is timing. QNX’s growth is long-term and structural, not event-driven. A single contract win (like a $50 million deal with a Chinese automaker) can move the stock 10% in a day, but the underlying trend is decades-long. Investors accustomed to quarterly beats struggle to value a business where certifications and R&D cycles dictate success. The result is a stock that’s both overvalued (as a BlackBerry asset) and undervalued (as a standalone tech play). Bridging that gap requires recognizing QNX not as a software company, but as infrastructure—the digital equivalent of a utility pole, invisible until it fails.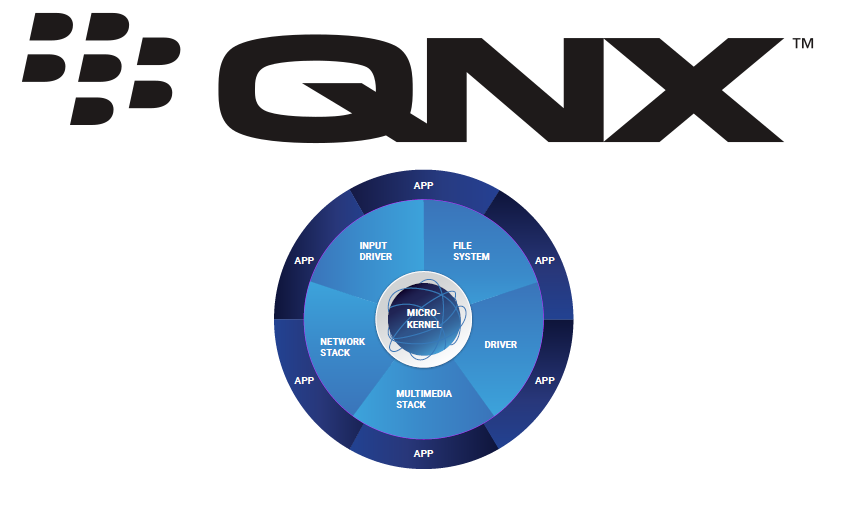
Conclusion
QNX stock is a study in invisible dominance. Its technology underpins systems where the alternative is unthinkable, yet its market valuation reflects a world that still sees it through the lens of BlackBerry’s broader struggles. The disconnect isn’t just semantic; it’s financial. For investors willing to look past the noise, QNX stock offers exposure to industries where software is physical infrastructure—automotive, aerospace, and industrial IoT. The risks are real: BlackBerry’s instability, geopolitical headwinds, and the ever-present threat of a rival OS gaining traction. But the rewards—recurring revenue, high margins, and regulatory moats—are equally clear. The key is separating QNX stock from BlackBerry’s legacy. The division’s contracts, certifications, and customer base operate on a different timeline than the parent company’s enterprise security business. When viewed through that lens, QNX isn’t a gamble—it’s a high-conviction bet on the future of embedded systems. The question isn’t whether QNX will succeed, but how long the market will take to price in its true value.Comprehensive FAQs
Q: Is QNX stock a good long-term investment?
A: For investors focused on industrial tech and automotive software, QNX stock’s long-term fundamentals are strong. Its recurring contracts, high margins, and regulatory moats make it a niche player with little competition. However, its correlation with BlackBerry’s broader performance means it’s not a standalone growth story—it’s a high-risk, high-reward play tied to BlackBerry’s ability to manage its other divisions.
Q: How does QNX compare to VxWorks?
A: QNX and VxWorks (owned by Wind River/Siemens) dominate different segments. QNX leads in automotive and industrial IoT, where ISO 26262 compliance is critical. VxWorks dominates aerospace and defense, where DO-178C certifications are non-negotiable. QNX’s advantage is its hypervisor technology, which allows it to run multiple OS instances on the same hardware—a feature increasingly valuable in software-defined vehicles.
Q: Why does QNX stock move so much on news?
A: QNX stock is highly event-driven because its revenue is tied to lumpy, multi-year contracts. A single certification win or supply-chain delay can move the stock 10–20% in a day. Unlike consumer tech stocks, which react to quarterly earnings, QNX’s performance reflects geopolitical risks, semiconductor availability, and automotive development cycles—not traditional financial metrics.
Q: Can QNX spin off from BlackBerry?
A: A spin-off is plausible but unlikely in the short term. QNX’s $100M+ annual revenue and high margins make it a prime candidate for independence, but BlackBerry’s financial constraints and leadership priorities would need to align. If BlackBerry were to pursue an IPO or sale, QNX would likely be the most valuable asset—potentially fetching $1B+ based on comparable embedded OS businesses.
Q: What are QNX’s biggest risks?
A: The primary risks are BlackBerry’s instability, geopolitical restrictions (especially around China and autonomous systems), and rival OS advancements. If a new OS gains ISO 26262 certification faster than QNX, it could erode market share. Additionally, QNX’s reliance on automotive cycles means downturns in car sales directly impact revenue. However, its defense and industrial contracts provide some insulation.
Q: How does QNX make money?
A: QNX’s revenue comes from licensing fees, custom development contracts, and certification services. Unlike open-source OSes, QNX charges per-deployment fees for its automotive and industrial products. A single OEM contract (e.g., a $50M deal with a Chinese automaker) can account for 20% of annual revenue, making its business model highly concentrated but sticky.
Q: Is QNX used in consumer devices?
A: QNX is rarely found in consumer devices like smartphones or laptops. Its architecture is optimized for deterministic, safety-critical systems—think autonomous cars, medical devices, and railway signaling. However, it powers some high-end industrial PCs and embedded systems in factories. The confusion arises because QNX was once used in BlackBerry’s own devices, but that’s a legacy niche today.
Q: What’s the biggest misconception about QNX?
A: The biggest myth is that QNX is a legacy technology clinging to 1990s-era principles. In reality, its microkernel architecture is being adapted for AI acceleration, quantum-resistant security, and edge computing—areas where traditional OSes struggle. The misconception persists because QNX doesn’t market itself like a consumer tech company; it lets its certifications and contracts speak for it.
