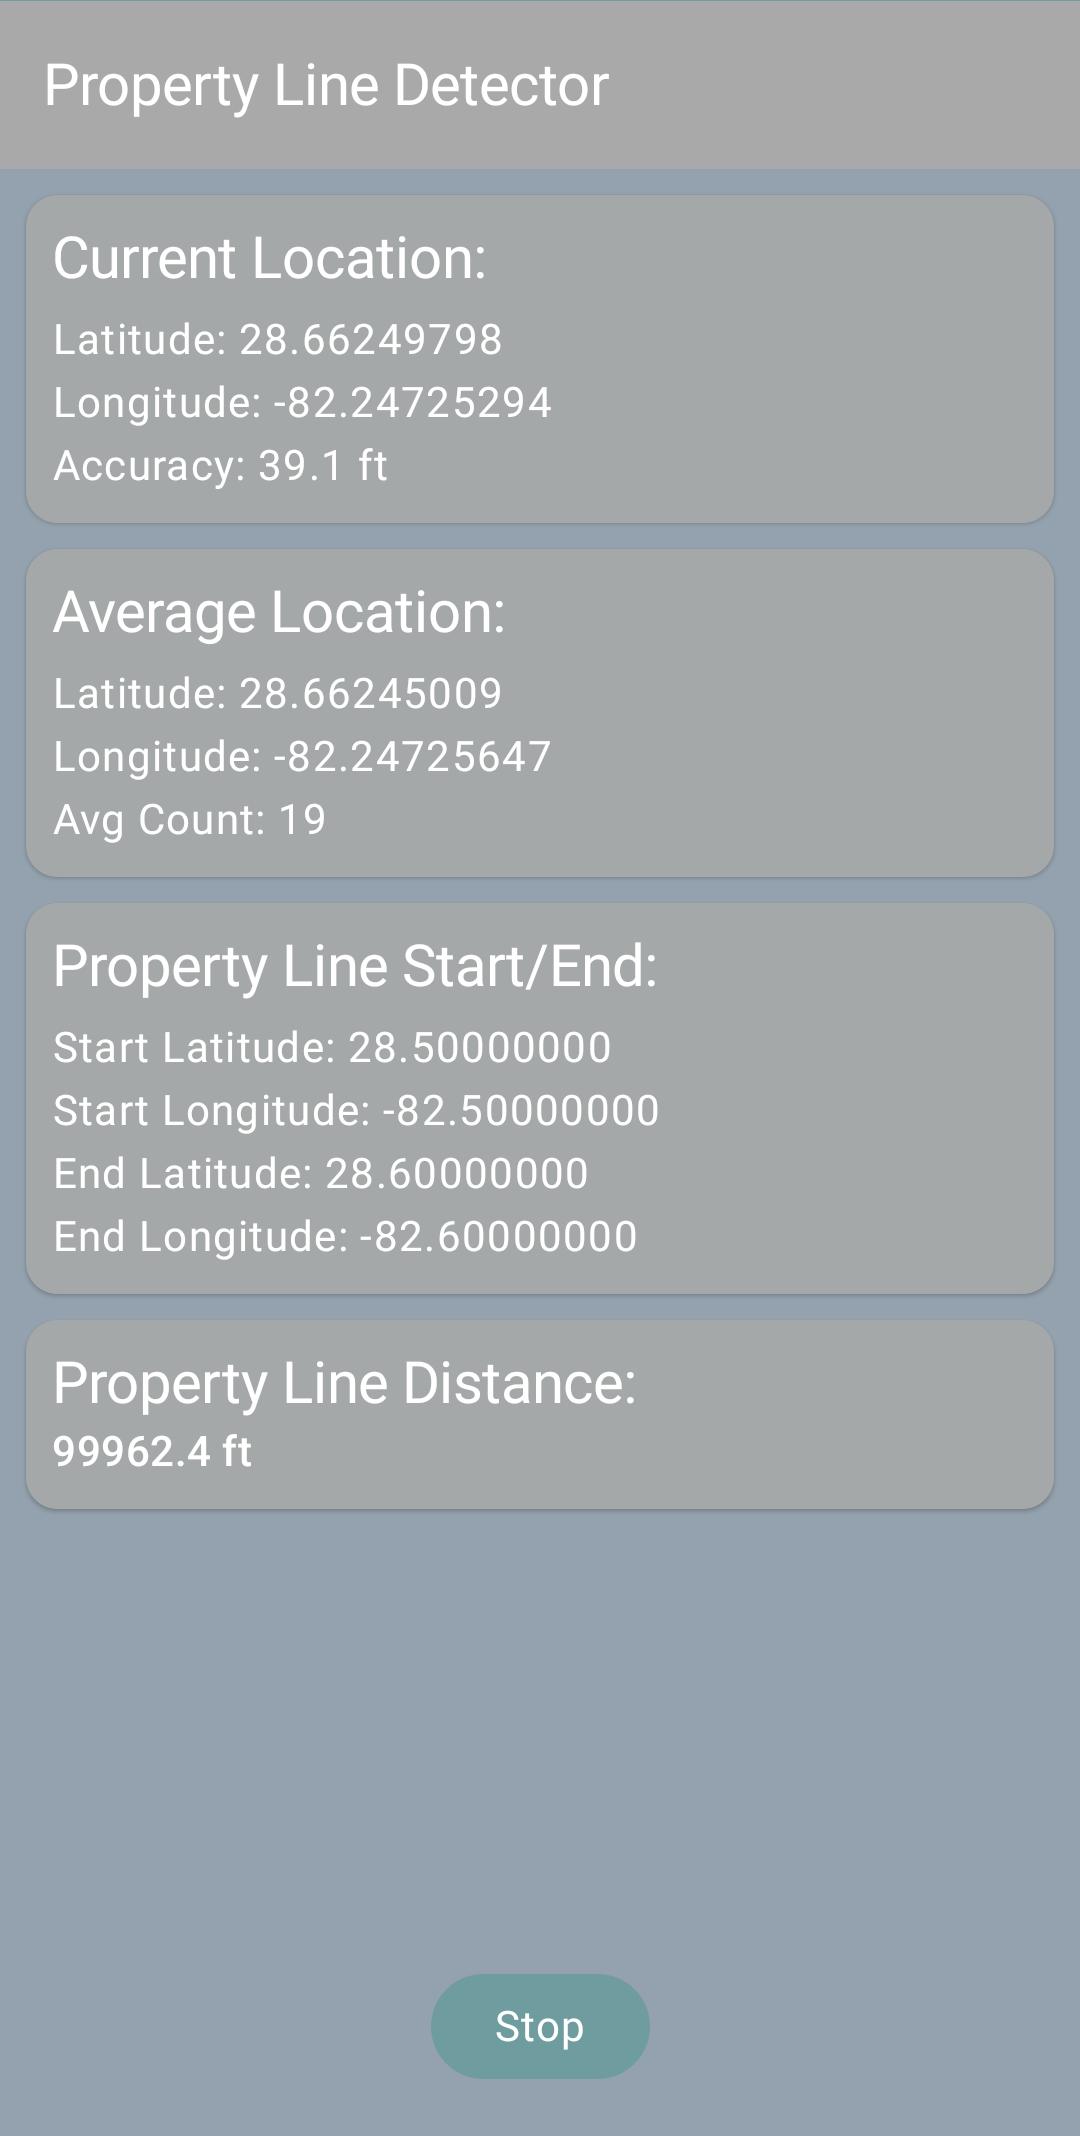
7 Things Worth Knowing About the Property Line App Ecosystem
The property line app landscape is a patchwork of precision tools and well-meaning but imperfect solutions. Navigating it requires clarity on what these apps can—and cannot—do, who stands to benefit most, and where the legal gray areas remain. Below are seven critical distinctions that separate the useful from the unreliable.1. Not All Property Line Apps Are Created Equal
The gap between a basic boundary checker and a professional-grade property line app mirrors the divide between a GPS app and a surveyor’s total station. At the low end, free tools like USGS TopoView or county assessor portals offer static PDFs of recorded plats—useful for a rough sketch but prone to errors from outdated data. Mid-tier apps, such as BoundaryScan or LandGrid, layer these with satellite imagery and sometimes LiDAR-derived elevation data to show potential encroachments. The top tier—used by commercial firms—includes Trimble’s SketchUp integration or Autodesk’s AutoCAD Civil 3D, which pull from ALTA/NSPS surveys (the gold standard for commercial transactions). The key difference lies in data sources. A property line verification app that relies solely on county records may show a boundary that’s been corrected in court but hasn’t been updated in the digital system. Meanwhile, apps with real-time integration (like OnX Hunt for rural properties) can flag discrepancies before they become disputes. The trade-off? Higher accuracy often means higher costs—some professional tools start at $500 for a single parcel analysis.2. Legal Weight Varies by Jurisdiction
Here’s where things get complicated. In Texas, courts have accepted property line app evidence in small claims cases, provided the app’s methodology is explained by an expert witness. In California, however, a judge dismissed a case where a homeowner used a land boundary app to argue a neighbor’s deck violated setback rules, ruling that the app’s crowdsourced corrections lacked chain-of-custody integrity. The lesson? Jurisdiction dictates credibility. Some states treat digitally verified property lines as admissible if cross-referenced with deeds, while others require notarized surveyor affidavits. The ALTA/ACSM Land Title Survey Standards (the industry benchmark) explicitly state that property line apps cannot replace licensed surveys for transactions over $500,000. Yet many homeowners use them for disputes under that threshold, gambling that the digital trail will hold up in court. The risk? If an app’s data is derived from a user’s incorrect input (e.g., misaligned GPS coordinates), the homeowner could face liability. Property line software is only as reliable as the data it ingests—and that data is often user-generated or third-party aggregated.3. Crowdsourcing Can Be a Double-Edged Sword
Apps like BoundaryBuzz or NeighborhoodBoundaries let users report and correct property lines based on photos, GPS traces, or even old family deeds. The community-driven approach has merits: in rural counties where assessor records lag years behind reality, these corrections can reveal long-standing but unrecorded boundaries. However, the system is vulnerable to gaming. A neighbor with a grudge might shift a line to justify a lawsuit. A seller might adjust boundaries to make a property appear larger before listing it. The most advanced property line apps now use machine learning to flag suspicious edits—such as sudden, large-scale boundary shifts in a single neighborhood. But even these systems can’t account for local customs, like the unwritten easements that exist in some rural communities. Blockquote: "In the Ozarks, we’ve got ‘oral grants’ where a family might say, ‘That creek bed’s yours,’ and it’s been that way for three generations—no deed, no survey, just trust. A property line app won’t catch that unless someone manually inputs it." — Mark R., real estate attorney in Missouri4. Commercial Users Have Different Needs Than Homeowners
A property line checker for a single-family home might prioritize ease of use and low cost, while commercial clients need scalability and audit trails. For developers, property line apps are often a pre-screening tool. Before buying a 10-acre plot, a firm might run it through multiple boundary apps to spot red flags—like overlapping easements or recorded but unenforced setback violations. If the initial checks pass, they’ll bring in a surveyor for the final due diligence. The biggest pain point for commercial users is data fragmentation. A property line verification app might show one boundary in county records, another in tax maps, and a third in historical deeds. Reconciling these requires layered analysis, which most consumer apps don’t support. Enterprise solutions, like Esri’s ArcGIS, can merge these datasets but cost thousands per project. The result? A two-tier system where homeowners get basic tools and professionals get specialized platforms.5. Accuracy Depends on Data Freshness
The single biggest variable in property line app reliability is how recently the underlying data was updated. County assessor offices often update property lines only when a deed is recorded—meaning a boundary change from 2010 might still show up as of 2005 in the digital system. Property line apps that pull from these sources can be years out of date. Even worse, some apps cache data locally, meaning users might see stale information even if the source has been corrected. The most accurate land boundary apps integrate with real-time feeds from county GIS departments or federal LiDAR programs. For example, NOAA’s Digital Coast provides elevation and floodplain data that can reveal unrecorded but physically present boundaries (like a natural watercourse that’s become the dividing line over time). However, these high-precision tools often require subscription fees or specialized training to use effectively.6. Insurance and Financing Are Starting to Recognize Them
Traditionally, mortgage lenders and insurers demanded licensed surveys for any property over $250,000. But as property line apps have improved, some institutions are relaxing these rules—provided the app meets specific criteria. Title insurance companies, for instance, now accept property line verification from certified apps (like BoundaryScan Pro) for refinances or small loans, reducing the need for full surveys. This shift is accelerating in states like Florida and Arizona, where boundary disputes are particularly common. The catch? Insurers still require that the property line app used be approved by their underwriting team. A generic boundary checker won’t cut it—it must be audited for accuracy in the specific region. Some lenders are even partnering with app developers to create white-labeled verification tools for their clients. The long-term implication? Property line apps could become standardized pre-approval tools, much like credit score checks are today.7. The Future May Lie in Blockchain
The next frontier for property line apps isn’t just better algorithms—it’s immutable records. Companies like Propy and ShelterZoom are experimenting with blockchain-based property registries where boundary changes are time-stamped and unalterable. The idea is to eliminate the "he said, she said" disputes that plague property line corrections. If a boundary is recorded on a blockchain, it can’t be retroactively edited by a disgruntled neighbor or a corrupt assessor’s office. The challenge? Adoption. Most property line apps today operate within existing legal frameworks, where paper deeds and court orders still hold sway. Convincing counties to transition to blockchain would require legislative changes—and the political will to phase out centuries-old land records systems. Still, pilot programs in Georgia and Sweden suggest that digital-only boundary management is coming. For now, property line apps remain a bridge technology, but the direction is clear: toward transparency and permanence.
How These Facts Connect
The property line app ecosystem reveals a fundamental tension: technology is democratizing access to boundary information, but it’s also exposing gaps in how we’ve traditionally managed land records. On one hand, these tools reduce costs and speed up resolutions for homeowners who’d otherwise spend thousands on surveys. On the other, they risk eroding trust when users rely on incomplete or outdated data—especially in court. The commercial sector’s adoption of these apps highlights another divide: businesses treat them as due diligence shortcuts, while individuals often use them as substitutes for professional advice. What ties these facts together is the evolving relationship between digital tools and legal systems. Courts are slowly accepting property line app evidence, but only under specific conditions—usually when the app’s methodology is vetted. Insurers and lenders are gradually integrating them into workflows, but with stricter controls than consumer apps allow. Meanwhile, blockchain and AI are pushing the envelope, promising unhackable records but requiring systemic change. The result? A hybrid future where property line apps coexist with traditional surveys, each serving a distinct role in the land ownership lifecycle. | Factor | Homeowner Use Case | Commercial Use Case | Legal Considerations | Data Source Reliability | Cost Range | |--------------------------|---------------------------------------|--------------------------------------|----------------------------------------|--------------------------------------|-------------------------------| | Primary Need | Dispute resolution, DIY verification | Pre-purchase due diligence, zoning | Admissibility in court, liability | County records vs. real-time feeds | $0 (free) to $5,000+ | | Key Risk | Relying on outdated or crowdsourced data | Missing unrecorded easements | App data not matching court records | Human error in data entry | High upfront cost for errors | | Best For | Small disputes, rural properties | Large transactions, urban plots | Cases with clear digital trails | Apps with GIS integration | Budget-conscious users | | Emerging Trend | Mobile-first, photo-based corrections | API integrations with lenders | Blockchain-backed boundary records | AI-driven discrepancy alerts | Subscription models | | Biggest Misconception| "Good enough for court" | "Replaces a surveyor" | "All apps are equally accurate" | "Public records are always current"| "Free tools are reliable" |
Conclusion
The property line app isn’t just a convenience—it’s a catalyst for change in how society handles land. For homeowners, it’s a first line of defense against encroachments; for developers, it’s a risk mitigation tool; for courts, it’s a growing body of evidence. Yet the wild west phase of this technology is giving way to structured adoption, where accuracy, legal weight, and integration with existing systems determine which tools survive. The blockchain experiments and insurer partnerships signal that this isn’t a passing trend—it’s a permanent shift in how property boundaries are verified, disputed, and enforced. The challenge now is balancing innovation with accountability. A property line app that helps a homeowner avoid a costly lawsuit is a success story—but one that fails to account for local customs or outdated records can create new problems. The future will likely see tiered solutions: basic apps for casual users, professional-grade tools for transactions, and blockchain-secured systems for high-stakes deals. Until then, the key for anyone using a land boundary app is simple: know its limits, cross-check with multiple sources, and consult a surveyor before making decisions that could alter a property’s value—or its very existence.Comprehensive FAQs
Q: Can I use a property line app to resolve a dispute in court?
A: It depends on the jurisdiction and how the app’s data is presented. Some courts accept property line app evidence if the app’s methodology is explained by an expert witness and the data is cross-referenced with deeds or surveys. However, crowdsourced corrections or outdated county records are often dismissed as unreliable. Always consult a real estate attorney before relying on app data in litigation.
Q: Are free property line apps accurate enough for buying land?
A: Free property line apps—like those using county assessor data—can give you a rough idea of boundaries, but they’re not accurate enough for purchases, especially for commercial properties. These tools often lack real-time updates, may contain user errors, and don’t account for unrecorded easements or local customs. For transactions, paid apps with GIS integration or a licensed survey are far safer.
Q: How do property line apps handle discrepancies between deeds and physical boundaries?
A: Most property line apps will flag discrepancies between recorded deeds and satellite/GPS data, but they don’t resolve them. For example, an app might show that a fence line doesn’t match the deed, but it won’t tell you who’s legally correct. Some advanced apps (like BoundaryScan Pro) include historical deed analysis, which can reveal past boundary adjustments, but they still can’t override court decisions. The best approach is to use the app as a starting point and follow up with a surveyor or attorney.
Q: Can a neighbor challenge a property line change made through a property line app?
A: Yes—but the challenge would likely focus on how the change was recorded, not the app itself. If a homeowner uses a property line app to report a corrected boundary and the county updates its records based on that, a neighbor could file a legal challenge if they believe the change was incorrect or fraudulent. Courts would examine whether the app’s data was reliable and if proper notice was given to affected parties. Crowdsourced edits are particularly vulnerable to disputes.
Q: Do mortgage lenders accept property line app verification instead of a survey?
A: Some lenders will accept property line app verification for smaller loans or refinances, but not for primary purchases—especially for properties over $250,000. Lenders that do accept app-based verification typically require the app to be on an approved list (e.g., BoundaryScan Pro, LandGrid Enterprise) and may still demand additional due diligence. Always confirm with your lender, as policies vary by state and loan type.
Q: How often are property line app databases updated?
A: Update frequencies vary widely by app and data source. County assessor records (used by many free apps) may only update when a deed is recorded, which can mean years of lag. Paid apps with GIS integration (like Esri or OnX) update monthly or quarterly, while real-time feeds (e.g., NOAA LiDAR) are continuous but require subscriptions. The best property line apps for accuracy combine multiple data sources and flag outdated information. Always check the app’s last update date before relying on it.
Q: Are there property line apps specifically for rural or agricultural land?
A: Yes. Apps like OnX Hunt (popular with landowners in Texas and the Midwest) and LandVision specialize in rural and agricultural properties, where boundaries are often defined by natural features (creeks, rock lines, old fence rows) rather than formal surveys. These apps integrate with USGS topo maps, LiDAR, and local soil records to show historical usage patterns that standard apps might miss. They’re particularly useful for timberland or ranch disputes, where oral agreements or long-standing practices define boundaries.
Q: What’s the most common mistake people make when using property line apps?
A: The biggest mistake is assuming the app’s boundary is definitive. Many users build fences, plant trees, or sue neighbors based solely on an app’s output—only to discover the line was incorrect or incomplete. Other common errors include: - Ignoring easements (apps often don’t show unrecorded ones). - Relying on satellite imagery alone (trees or shadows can misalign boundaries). - Not checking for pending legal actions (some apps don’t pull court records). The safest approach is to use the app as a guide, not gospel, and verify with a surveyor before taking action.
