The Complete Overview of Budgeting by Net Worth Percentage
Budgeting by net worth percentage reframes financial planning around asset-based proportions rather than income brackets. It’s not about cutting costs arbitrarily; it’s about allocating spending as a function of your total wealth. This method gained traction in niche financial circles before spreading to mainstream advisors, particularly among those managing portfolios with significant illiquid assets (real estate, private equity, or collectibles). The core idea is that as your net worth increases, your spending should scale proportionally—without requiring a corresponding rise in cash flow. For example, a young professional might cap lifestyle expenses at 5% of their net worth, while a retiree might adjust to 3% to preserve capital. What sets this approach apart is its anti-inflationary bias. Traditional budgets often inflate with salary growth, creating a cycle where spending outpaces savings. Budgeting by net worth percentage, however, ties discretionary funds to the value of what you own, not the velocity of your income. This matters especially in high-net-worth scenarios, where a fixed monthly allowance could become unsustainable if assets depreciate. The system also bridges the gap between liquidity and long-term wealth—you’re not just tracking bank balances, but the totality of your financial ecosystem.Historical Background and Evolution
The concept traces back to early 20th-century wealth management principles, where advisors emphasized spending in relation to total capital rather than fixed percentages of income. The 1930s saw the rise of "percentage-based living" among European aristocracy, who allocated expenditures as fractions of their estates’ value—a practice that survived into post-war financial planning. By the 1980s, American financial theorists like John Bogle (Vanguard founder) began advocating for similar frameworks, though not under this exact name. The modern iteration emerged in the 2010s, popularized by financial independence (FI) communities and digital nomads managing global assets. A pivotal moment came when tech entrepreneurs and remote workers—whose incomes fluctuated wildly—adopted net worth-based budgets to stabilize spending. The method’s flexibility made it ideal for those with non-traditional revenue streams, such as royalties, dividends, or crypto holdings. Today, it’s less about rigid rules and more about dynamic alignment: as your net worth grows, so does your capacity to spend, but only within predefined thresholds. The evolution reflects a broader shift from static budgeting to adaptive financial systems.Core Mechanisms: How It Works
The mechanics hinge on three variables: net worth, spending categories, and percentage allocations. First, calculate your net worth (total assets minus liabilities). Then, assign percentages to categories—say, 3% for discretionary spending, 2% for investments, and 1% for debt repayment. The percentages are fluid; a retiree might reduce discretionary spending to 1% to prioritize legacy planning. The system requires regular recalibration, typically quarterly or annually, to reflect market changes or life events (e.g., a home purchase or inheritance). The key innovation is automatic scaling. If your net worth jumps from £200,000 to £400,000, your £6,000 discretionary budget (3%) doubles to £12,000—without needing a salary increase. This mirrors how ultra-high-net-worth individuals operate: their spending isn’t tied to a monthly paycheck but to the liquidity of their entire portfolio. Tools like YNAB (You Need A Budget) or spreadsheets can automate the calculations, but the discipline lies in treating net worth as the anchor for all financial decisions.Key Benefits and Crucial Impact
Budgeting by net worth percentage isn’t just a tool—it’s a mindset that forces clarity on what wealth actually means. For those with complex asset mixes (e.g., rental properties, stocks, and crypto), it provides a unified framework where liquidity isn’t the sole determinant of spending power. The method also mitigates lifestyle inflation, a silent killer of long-term wealth. Traditional budgets often fail when income spikes; this system absorbs growth without encouraging profligacy. The psychological impact is equally significant. By tying spending to net worth, individuals avoid the trap of relative deprivation—comparing their income to peers rather than their own asset base. It’s a shift from "Can I afford this?" to "Does this align with my total wealth?" This perspective is particularly valuable in volatile markets, where paper losses can erode confidence in fixed budgets."Budgeting by net worth percentage is the financial equivalent of sailing by the stars—it keeps you oriented toward your destination, not the immediate horizon." — James Clear, behavioral economist
Major Advantages
- Adaptability: Adjusts automatically to market fluctuations or asset appreciation without manual intervention.
- Wealth Preservation: Prevents lifestyle inflation by linking spending to total capital, not income.
- Asset Diversification: Encourages viewing all assets (not just cash) as part of the budgeting equation.
- Psychological Resilience: Reduces stress from income volatility by focusing on net worth as the stability metric.
- Legacy Planning: Allows for intentional reductions in spending percentages as wealth grows, prioritizing inheritance or philanthropy.
Comparative Analysis
| Budgeting by Net Worth % | Traditional Percentage-Based Budgeting |
|---|---|
| Spending tied to total assets (liquid + illiquid). | Spending tied to monthly/annual income. |
| Adapts to market changes without manual adjustments. | Requires frequent recalibration with income shifts. |
| Ideal for high-net-worth individuals or complex asset portfolios. | Best suited for stable, predictable incomes. |
| Encourages long-term wealth focus over short-term liquidity. | Prioritizes immediate cash flow management. |
| Psychologically aligned with asset growth. | Can lead to lifestyle inflation with income increases. |
Future Trends and Innovations
The next frontier for budgeting by net worth percentage lies in AI-driven recalibration. Financial platforms could use machine learning to adjust spending thresholds in real time, factoring in market trends, life stages, and even emotional spending patterns. Blockchain-based asset tracking might further refine the method, allowing for granular percentage allocations across fractionalized assets (e.g., real estate or private equity). Another trend is the rise of "net worth circles"—communities where individuals share percentage-based budgets to normalize spending relative to their peer group’s wealth tiers. The biggest challenge remains behavioral adoption. Many still cling to income-based budgets, viewing net worth as a static number rather than a dynamic variable. Overcoming this requires education on how asset-based planning differs from traditional methods—especially for those with non-traditional wealth (e.g., crypto holders or digital nomads). As remote work and global asset portfolios become the norm, this method’s flexibility will likely position it as the default for the next generation of wealth managers.Conclusion
Budgeting by net worth percentage isn’t a one-size-fits-all solution, but it offers a rare blend of precision and adaptability. Its strength lies in treating wealth as a living entity—one that grows, shrinks, and evolves with the economy and personal circumstances. For those tired of budgets that feel rigid or irrelevant to their actual financial picture, this approach provides a refreshing alternative. The trade-off? It demands discipline in tracking net worth and recalibrating regularly. But for those willing to embrace it, the payoff is a financial strategy that scales with their life. The method’s future hinges on its ability to integrate with emerging technologies—whether through AI, blockchain, or hyper-personalized financial tools. As wealth becomes increasingly decentralized and asset classes diversify, percentage-based budgeting tied to net worth may well become the gold standard for those who refuse to let their spending outpace their growth.Comprehensive FAQs
Q: How often should I recalculate my net worth for this method?
Quarterly is ideal, but annual recalibrations work for stable portfolios. The key is consistency—fluctuations in illiquid assets (e.g., real estate) may require more frequent updates.
Q: Can I use this method if my net worth includes illiquid assets like property?
Yes, but you’ll need to estimate their current market value regularly. Tools like Zillow or professional appraisals can help, though the estimates should be conservative to avoid overestimating spending capacity.
Q: What percentage ranges are typical for discretionary spending?
Most practitioners recommend 1–5% for discretionary funds, with higher percentages for younger individuals and lower ones for retirees. The exact range depends on goals—aggressive savers might cap at 1%, while those prioritizing lifestyle may allow 3–5%.
Q: How does this method handle debt repayment?
Debt repayment is often treated as a separate percentage (e.g., 1–2% of net worth) or folded into discretionary spending if the goal is to eliminate debt quickly. The critical factor is ensuring the percentage aligns with your debt’s interest rate and repayment timeline.
Q: Is this method compatible with irregular income streams?
Absolutely. Since spending is tied to net worth—not income—it’s perfect for freelancers, commission-based earners, or those with seasonal work. The buffer comes from treating net worth as the stable reference point.
Q: What if my net worth drops due to market conditions?
The system is designed to handle this. If your net worth falls, your spending thresholds adjust downward automatically. The discipline is in maintaining the percentage structure even during downturns, rather than panicking and increasing spending.
Q: Can I combine this with other budgeting methods?
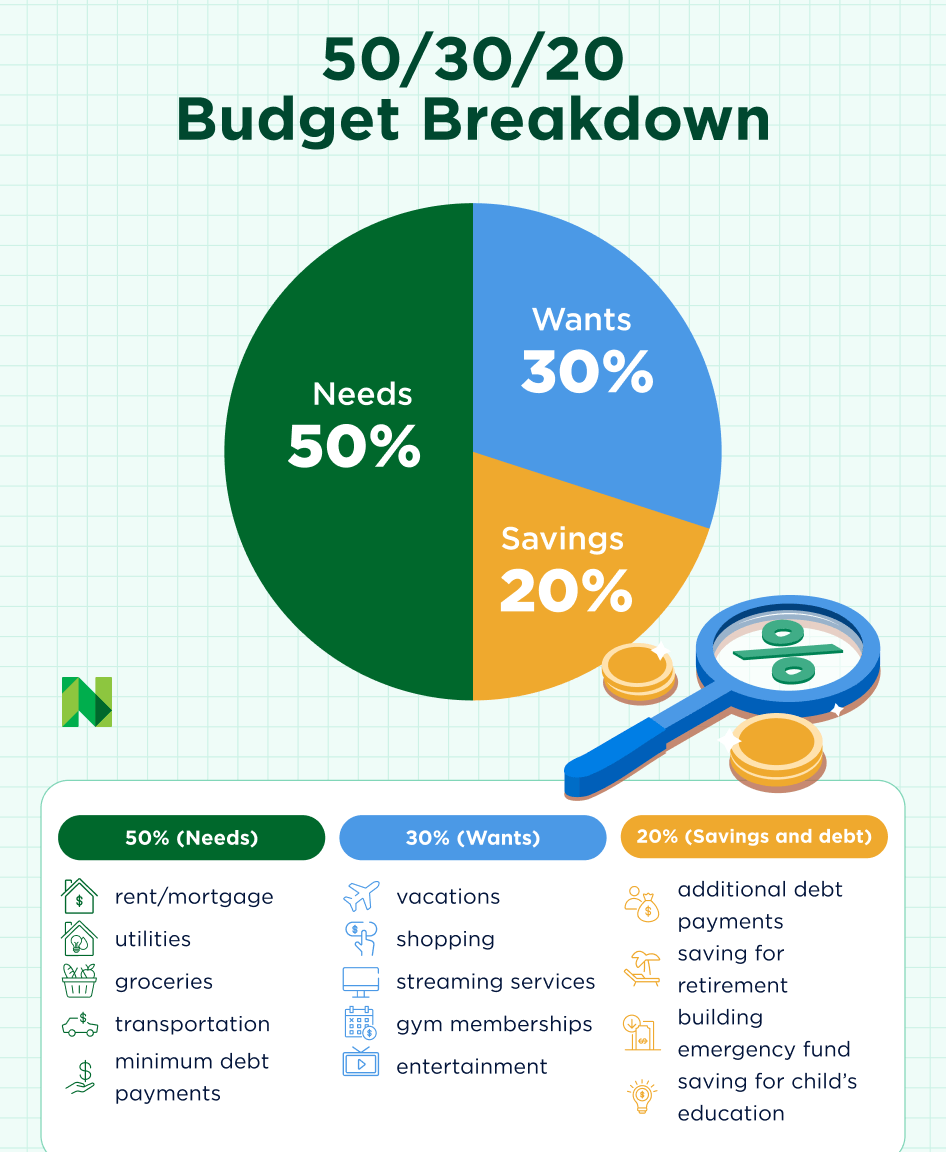
Yes, many use it alongside the 50/30/20 rule or zero-based budgeting. The net worth percentage approach often serves as the overarching framework, while other methods handle day-to-day allocations.
Q: Are there any industries or professions where this method is particularly effective?
It’s especially useful for entrepreneurs, remote workers, investors, and those with non-traditional income (e.g., royalties, dividends). Professionals in volatile fields—like tech or finance—also benefit from its adaptability to asset fluctuations.
