
The Complete Overview of Calculating Change in Net Worth Percentage
The foundation of how to calculate change in net worth percentage lies in two core components: defining net worth itself and establishing a reliable baseline for comparison. Net worth is the difference between total assets (cash, investments, real estate, intellectual property) and total liabilities (mortgages, student loans, credit card debt). The percentage change, however, isn’t merely about raw numbers—it’s about relative performance. A $100,000 gain on a $1 million portfolio yields a 10% increase, while the same gain on a $10,000 portfolio is 1,000%. Context matters. Most financial tools simplify this by using end-of-period snapshots, but seasoned analysts adjust for intra-year volatility. For example, a tech executive might see their stock options vest mid-year, inflating net worth without reflecting the underlying market risk. Similarly, a real estate investor’s property value could spike due to zoning changes rather than fundamental appreciation. These distortions require either manual adjustments or sophisticated tracking software. The choice depends on the asset’s liquidity and the holder’s risk tolerance. Industry standards vary by region. In the U.S., the Federal Reserve’s Survey of Consumer Finances uses a three-year rolling average to smooth out short-term fluctuations, while European central banks often annualize quarterly data to align with fiscal reporting cycles. The discrepancy highlights why how to calculate change in net worth percentage isn’t universal—it’s tailored to the investor’s time horizon and asset mix. A retiree focusing on preservation will prioritize stability over growth metrics, whereas a venture capitalist might care more about compounded returns over irregular intervals. The real challenge isn’t the arithmetic but the data integrity. Missing a side hustle’s revenue, underreporting a credit card balance, or failing to account for a gift from family can skew results by 10% or more. Even high-net-worth individuals with dedicated CFOs encounter this—according to a 2023 report by Wealth-X, 38% of ultra-high-net-worth families admit to discrepancies in their net worth tracking due to incomplete asset disclosure.Historical Background and Evolution
The concept of tracking net worth dates back to 18th-century mercantile ledgers, where merchants recorded assets and debts to assess solvency. However, the percentage-based change calculation emerged in the early 20th century as economists sought to normalize wealth growth across inflationary periods. John Maynard Keynes’ 1936 General Theory of Employment introduced the idea of "real wealth" adjustments, laying groundwork for modern net worth indexing. By the 1970s, personal finance gurus like George S. Clason (author of The Richest Man in Babylon) popularized simplified versions for individual investors, though without the percentage-change rigor used today. The digital revolution transformed this practice. Early spreadsheet tools like Lotus 1-2-3 allowed users to automate calculations, but it wasn’t until the 2000s—with the rise of platforms like Mint, Personal Capital, and YNAB—that how to calculate change in net worth percentage became accessible to the masses. These tools introduced features like goal tracking and scenario modeling, which implicitly rely on percentage-change analysis. Yet, even now, only 42% of Americans track their net worth annually, per a 2022 Northwestern Mutual study, suggesting a gap between available tools and adoption. The financial crisis of 2008 exposed a critical flaw: many investors relied on nominal (not inflation-adjusted) net worth changes, leading to overoptimism about recovery. Post-crisis, institutions adopted stricter methodologies, including: - Time-weighted returns (to separate performance from cash flows) - Monte Carlo simulations (to stress-test net worth under volatility) - Liability aging schedules (to project debt payoff impacts) These refinements turned net worth tracking from a static exercise into a dynamic forecasting tool.Core Mechanisms: How It Works
The core formula for how to calculate change in net worth percentage is straightforward: ``` ((Current Net Worth – Previous Net Worth) / Previous Net Worth) × 100 ``` For example, if net worth grew from $500,000 to $550,000, the change is 10%. However, the devil lies in the definitions. Assets must be marked to market (current value, not purchase price), and liabilities should reflect outstanding balances, not original amounts. A common mistake is including appreciated assets at cost—this inflates net worth artificially. Inflation adjustments further complicate the picture. A 5% nominal gain in a high-inflation year might translate to a 2% real gain. Financial planners often use the Consumer Price Index (CPI) to deflate net worth changes, though critics argue CPI understates true cost-of-living increases. The choice between nominal and real calculations depends on the investor’s goals: nominal for tax reporting, real for lifestyle planning. For businesses or high-net-worth families, the process extends to segmented tracking. A family office might calculate net worth changes separately for: - Liquid assets (cash, public equities) - Illiquid assets (private equity, real estate) - Human capital (earning potential, intellectual property) Each segment may use different valuation methods, requiring weighted averages to derive an overall percentage change.Key Benefits and Crucial Impact
Understanding how to calculate change in net worth percentage isn’t just about crunching numbers—it’s about aligning financial behavior with long-term objectives. For retirees, a 3% annualized decline might trigger panic, while a 7% gain could justify increased spending. For entrepreneurs, it signals whether a business’s growth is outpacing personal debt accumulation. The metric acts as a financial thermometer, revealing whether a strategy is heating up or cooling down. > "Net worth percentage changes are the financial equivalent of a pulse check—they tell you if your wealth is alive or in decline, long before the balance sheet does." — Morgan Housel, The Psychology of Money The impact extends beyond personal finance. Institutional investors use these calculations to evaluate fund managers, while governments rely on them to assess economic inequality. A 2023 study by the World Inequality Database found that households in the top 1% saw net worth grow by 6.8% annually (adjusted for inflation) over the past decade, compared to 1.2% for the bottom 50%. These disparities underscore why how to calculate change in net worth percentage isn’t just technical—it’s political.Major Advantages
- Risk assessment: A sudden drop in net worth percentage can indicate overleveraging or market exposure before it’s visible in absolute terms.
- Goal alignment: Tracking percentage changes forces investors to distinguish between nominal gains (e.g., a rising stock market) and real growth (e.g., increased purchasing power).
- Behavioral discipline: Visualizing percentage changes—via charts or dashboards—reduces emotional reactions to market volatility.
- Tax optimization: Accurate net worth tracking identifies capital gains triggers, helping investors time realizations for tax efficiency.
Comparative Analysis
| Method | Use Case |
|---|---|
| Nominal Net Worth Change | Short-term tracking, tax reporting, or high-inflation environments where real adjustments are impractical. |
| Inflation-Adjusted (Real) Change | Long-term planning, retirement projections, or comparing wealth across decades. |
| Segmented Net Worth (Liquid vs. Illiquid) | Portfolios with significant private assets (e.g., real estate, startups) where valuation is subjective. |
Future Trends and Innovations
The next frontier in how to calculate change in net worth percentage lies in artificial intelligence and blockchain. AI-driven tools are already predicting net worth trajectories by analyzing spending patterns, market trends, and even social media activity (e.g., luxury purchases). Blockchain, meanwhile, enables real-time, transparent asset tracking—critical for digital currencies and tokenized real estate. These innovations could reduce the human error margin in net worth calculations from ~15% to near-zero. Another shift is toward behavioral net worth metrics, which incorporate psychological factors like stress levels or sleep quality (correlated with financial anxiety). Wealth management firms are experimenting with biometric data to adjust net worth thresholds dynamically. For example, a 5% drop might trigger alerts only if the investor’s heart rate variability spikes, indicating emotional distress. Regulatory changes may also reshape the landscape. The SEC’s proposed rules on private fund liquidity could force more granular net worth disclosures, while GDPR-like privacy laws might limit how firms use personal financial data for predictive modeling. Investors will need to adapt their tracking methods to comply with evolving standards.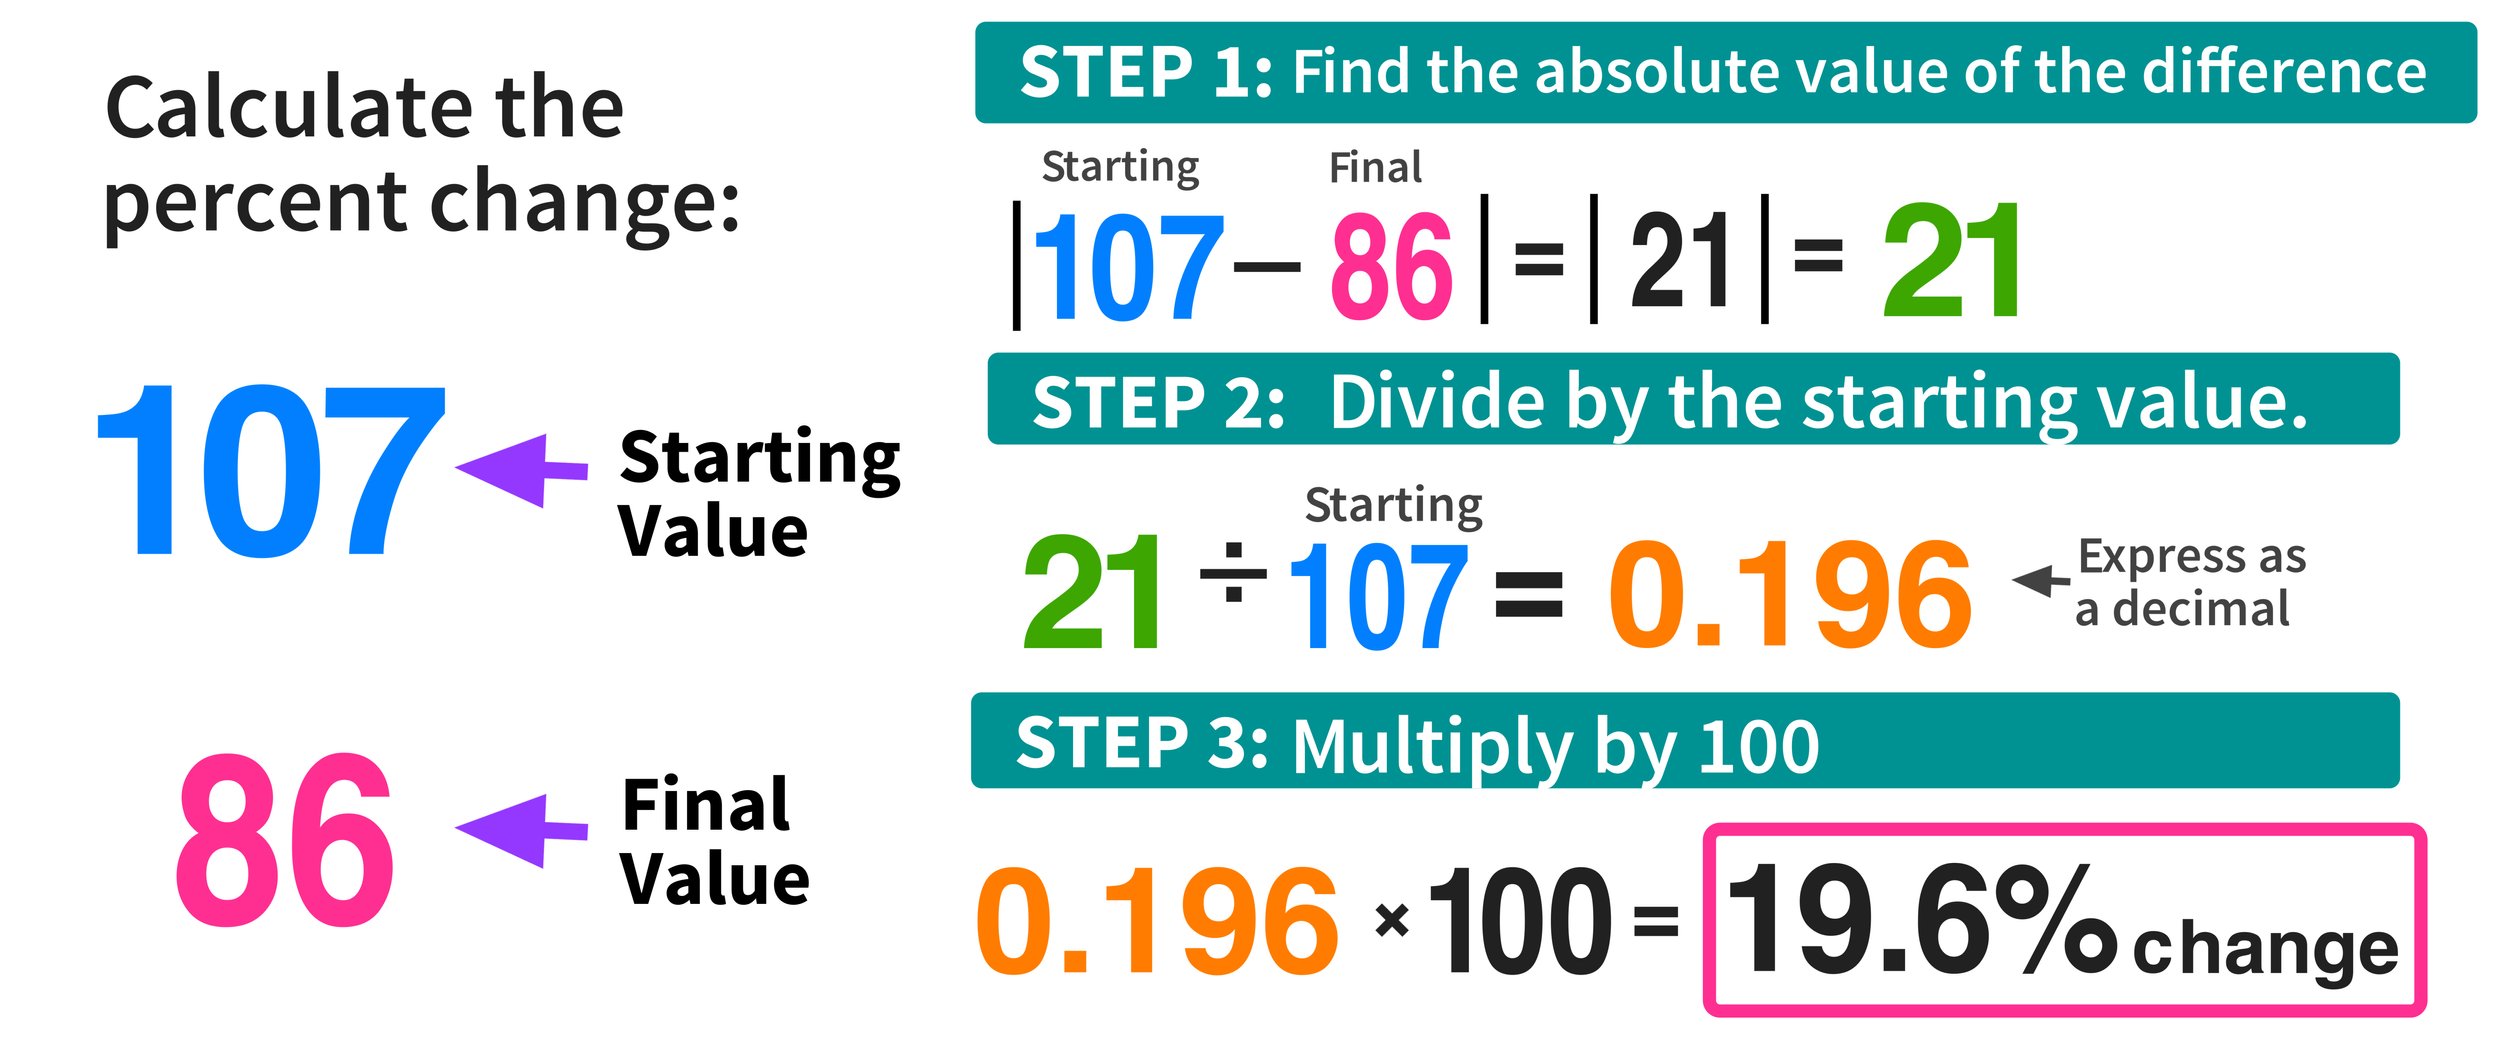
Conclusion
Mastering how to calculate change in net worth percentage isn’t about memorizing a formula—it’s about building a system that reflects reality. The best approaches balance precision with practicality, whether through automated tools or manual adjustments. The key is consistency: tracking the same assets and liabilities over time, using the same valuation methods, and accounting for inflation when relevant. For individuals, this discipline reveals opportunities—like identifying underperforming assets before they drag down the portfolio—or risks, such as lifestyle creep eroding gains. For institutions, it’s a competitive edge in performance attribution. In all cases, the metric serves as a mirror: showing not just where you’ve been, but where you’re headed.Comprehensive FAQs
Q: How often should I calculate my net worth percentage change?
A: Quarterly is ideal for most investors, as it captures market volatility without overwhelming you. High-net-worth individuals or those with volatile assets (e.g., startups, crypto) may track monthly, while retirees often suffice with annual reviews. The frequency should align with your liquidity needs—more frequent tracking helps with cash-flow management.
Q: Do I need to adjust for inflation when calculating net worth changes?
A: Yes, for long-term planning. Inflation erodes purchasing power, so a 5% nominal gain might only be 2% in real terms. Use the CPI or a sector-specific inflation index (e.g., housing costs) for accuracy. Short-term investors (e.g., traders) can skip this, but retirees or those saving for goals decades away should adjust.
Q: What if my net worth drops by 10% in a year—is that normal?
A: Not necessarily. A 10% drop could reflect market conditions (e.g., 2008, 2022), but it might also signal overconcentration in a single asset (e.g., a company stock). Compare it to benchmarks: if the S&P 500 fell 20% and your portfolio only 10%, you’re outperforming. If your drop exceeds the market’s, reassess risk exposure or valuation methods for illiquid assets.
Q: Can I calculate net worth percentage change without knowing exact asset values?
A: Yes, but with caveats. For liquid assets (cash, public stocks), use current market values. For illiquid assets (real estate, private equity), estimate based on comparable sales or appraisals. If precision is critical, hire a professional valuer. Approximations work for trend-spotting but aren’t reliable for tax or legal purposes.
Q: How do I handle gifts or inheritances in net worth calculations?
A: Treat them as one-time injections to net worth. If a parent gives you $100,000, add it to your assets and note the source. Gifts don’t affect percentage changes directly but can distort year-over-year comparisons. For inherited assets, subtract any estate taxes or debts incurred before adding the net value to your portfolio.
Q: Should I include my home’s value in net worth calculations?
A: Yes, but with context. Primary residences are illiquid, so their valuation can be subjective. Use recent comparable sales or a professional appraisal. If your home is your largest asset, its fluctuations will dominate net worth changes—consider whether this aligns with your financial goals (e.g., stability vs. growth). Some advisors exclude it for simplicity, but this can understate true wealth.
Q: What’s the best tool for tracking net worth percentage changes?
A: For most people, a spreadsheet (Google Sheets or Excel) with automated formulas is sufficient. Dedicated tools like Personal Capital, YNAB, or Mint offer built-in net worth tracking, while advanced users may prefer platforms like eMoney or Black Diamond for portfolio-level analysis. High-net-worth families often use family office software like Wealthbox or Redtail. Choose based on asset complexity and need for real-time updates.
